Cinemark Edges Past The Whisper As Record Q3 And Longer Windows Outweigh A Slip In Domestic Share
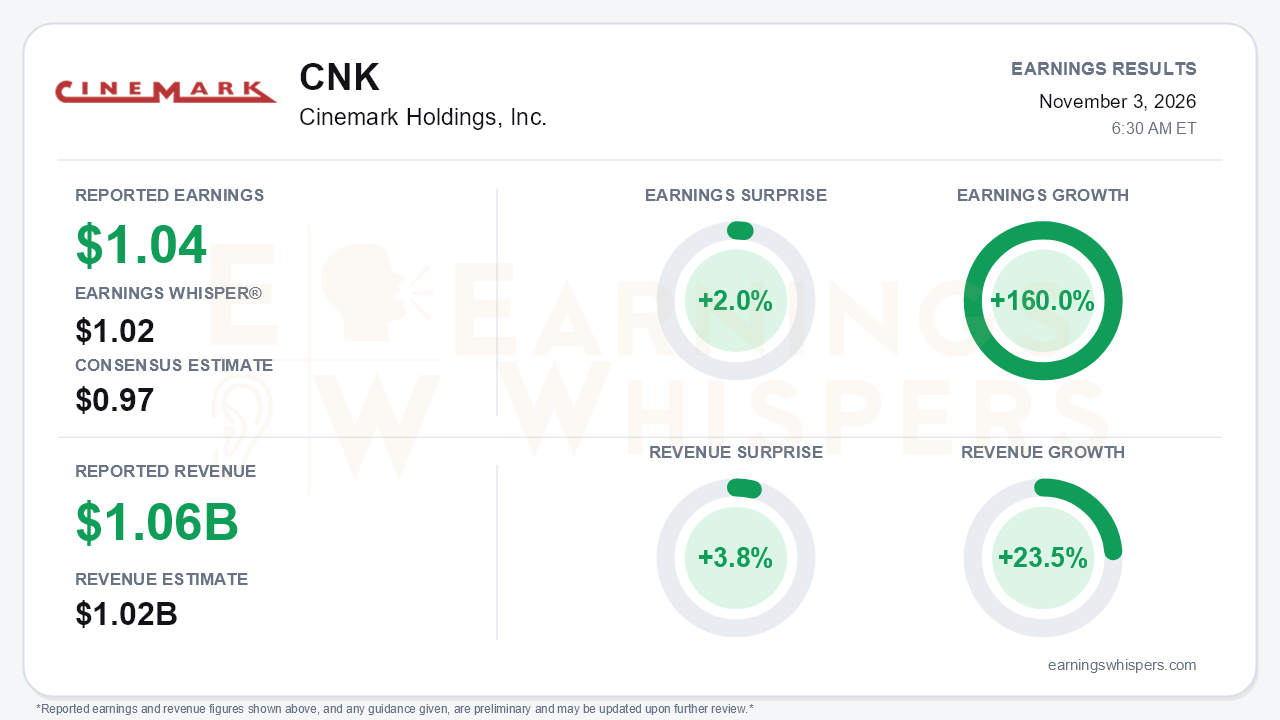
Cinemark Holdings (NYSE: CNK) delivered another record quarter. The more important development, though, was the call's shift from cautious optimism to an openly bullish multi-year view. Third-quarter earnings came in at $1.04 per share, ahead of the $0.97 consensus and slightly above the $1.02 Earnings Whisper number, a 2.0% beat. Revenue of $1.059 billion topped the $1.02 billion consensus by 3.8%. Year over year, earnings grew 160.0% and revenue grew 23.5%. Revenue growth was faster than the roughly 19% pace Cinemark posted in the first quarter. The EPS beat over the whisper was modest; the top-line upside and the structural industry news are what make this quarter notable.
The press release added little beyond the headline, directing investors to separately published executive commentary, so the substance came from the call. Management cited record third-quarter revenue of about $1.1 billion and adjusted EBITDA of $268 million, with adjusted EBITDA margin up 460 basis points year over year. The quality of the quarter is solid, but not every element is repeatable. Management said labor favorability tied to film outperformance will not recur. The comparison with the second quarter also matters. That period was Cinemark's first $1 billion-plus quarter, with $294 million of EBITDA and a 27.1% margin. Third-quarter EBITDA came in below that level, a sequential cooling that the 160% year-over-year earnings growth figure obscures.
Beneath the headline, pricing and spending per guest are running well ahead of the plan management laid out at the start of the year. Domestic average ticket price is tracking about 5% higher year to date against a 'modest' guide. Domestic concession per capita is up 5.5% against a 'moderate' guide, building on roughly 5% growth in FY25. Premium formats lifted box office about 50% and now account for 18% of the total, up from roughly 15% cited on earlier calls. Latin America turned around sharply. After falling short of expectations in the first quarter, the region posted a 25% attendance increase, its best quarter since Q3 2019.
The forward-looking catalysts are where the setup changed most. Cinemark endorsed the Skydance/Paramount-Warner Bros. combination after a consent decree committed the merged studio to film volume for five years and to 45-day theatrical windows. The average exclusive window has already stretched to about 42 days from 34 a year ago. Management said Universal, Sony, Warner Bros. and Lionsgate are moving toward 45-plus days in 2027. Netflix has announced six full theatrical releases through November 2027, and Amazon is nearing about 15 releases a year. Earlier calls took a 'watch and wait' stance on windows and streaming partners; that caution has given way to confidence about Q4 2026, 2027 and even 2028. Management said October ran ahead of expectations, and the fourth-quarter slate includes Hunger Games, Avengers: Doomsday and Dune: Part Three. Net leverage is now below the company's 2-3x target, leaving excess cash for buybacks, dividends or M&A. Management also signaled that capital spending could exceed the prior roughly $250 million normalized ceiling to accelerate premium-format investment.
Bears still have legitimate points. Domestic market share compressed year over year in the third quarter, reversing gains seen in the second quarter after a flat first quarter. Management expects fourth-quarter share to look similar to the third. Share remains more than 150 basis points above pre-pandemic levels, but the direction has turned. Fourth-quarter ticket-price growth should moderate against last year's Avatar 3D comparison, which added about $0.18. The 2027 Latin American slate looks a touch lighter than 2026's. Texas electricity rates, wage inflation and concession cost pressure persist. Studio consolidation remains a long-term risk despite the decree's protections.
Investor expectations rose considerably heading into the report. Earnings Whispers sentiment climbed from 0.47 to 0.73, a meaningful move further into positive territory. Shares were up 6.2% from the opening price after the July report, trading near $38.75 and about 23.6% above the 200-day moving average. The stock entered earnings about 4.4% below its October 22 52-week high of $40.53 and 15% above its September low. Most Earnings Whispers trend signals are positive, though the sequential growth reading is negative, consistent with the step down in EBITDA from the second quarter. With sentiment elevated and shares near the top of their range, the bar for upside surprises has risen.
The bottom line is that Cinemark beat on both lines, ran well ahead of its own pricing and concession framework, and gained real structural support from longer windows, studio volume commitments and new streaming-studio releases. Against that, domestic share is slipping and some third-quarter cost benefits will not recur. Sequential momentum also cooled from the second-quarter peak. The fundamental story improved more than the 2.0% beat suggests, but rising sentiment and a stock trading near its highs leave less room for error.
Read our earnings preview for Cinemark Holdings, Inc.: https://www.earningswhispers.com/article/CNK/21469
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 54 min | |
| 1 hour | |
| 6 hours | |
| 8 hours | |
| Nov-02 | |
| Oct-28 | |
| Oct-26 | |
| Oct-25 | |
| Oct-25 | |
| Oct-22 | |
| Oct-15 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-30 |
