JBT Marel Must Prove Its Food-Equipment Margin Stumble Was Temporary As Shares Slide
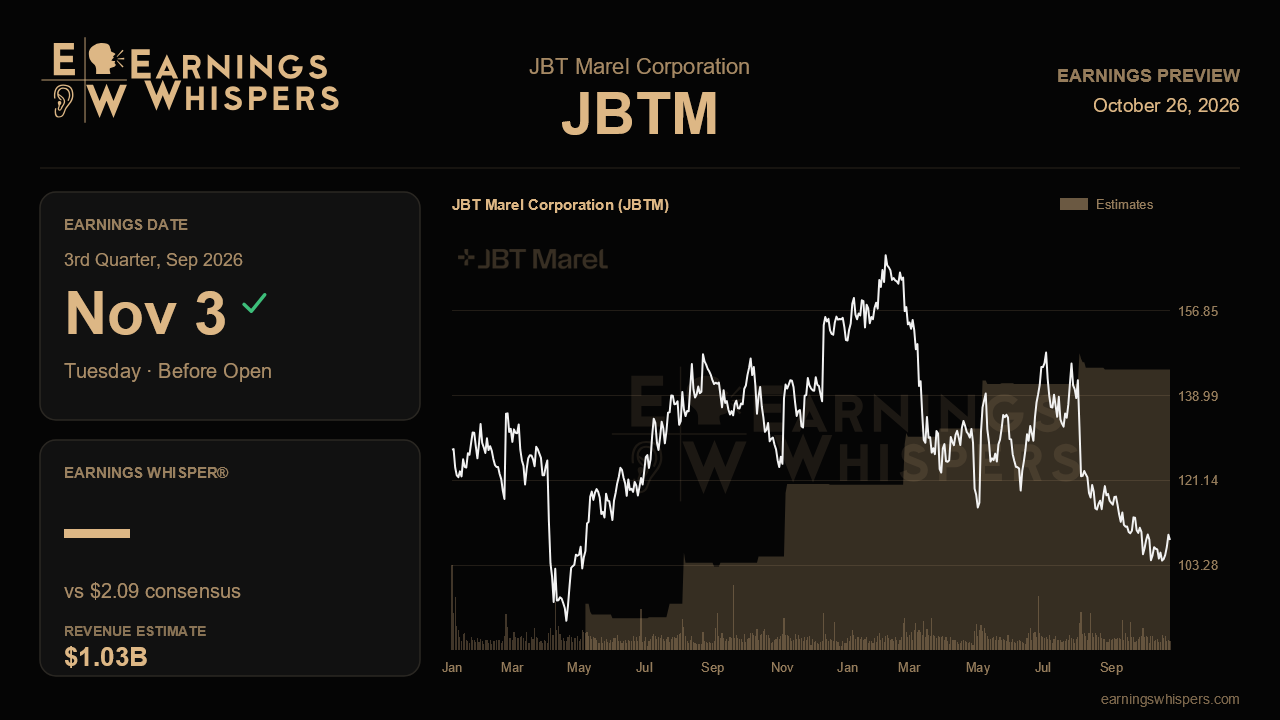
JBT Marel heads into its third-quarter report with a split personality. Customers keep ordering at a healthy clip, with bookings topping $1 billion for three straight quarters, yet the company stumbled on execution last quarter, and the stock has paid the price. Shares have fallen about 15% since the last report while the S&P 500 was essentially flat. That sets up a plain test for the November 3 release: can management show that last quarter's margin problems were a temporary cost of moving factories, or are they the start of something more durable?
The Street is looking for earnings of $2.09 per share on revenue of about $1.03 billion. That works out to roughly 8% earnings growth and about 3% revenue growth from a year ago, which is modest progress rather than a breakout. Those figures line up well with management's own third-quarter outlook of 2% to 4% organic growth and an EBITDA margin of 17% to 17.5%. The bigger tension sits in the full-year numbers. The company trimmed its 2026 earnings outlook to $7.85 to $8.35 per share from $8.00 to $8.50 and held revenue guidance at $3.99 billion to $4.065 billion. Consensus of $8.26 sits near the top of the lowered range, while the $4.03 billion revenue estimate lands near the midpoint. In other words, analysts are still giving management the benefit of the doubt on profitability, and that leaves less room for another slip, especially since management has described the recovery as weighted toward the fourth quarter.
The prepared food and beverage business is the swing factor. Last quarter its revenue was flat from a year earlier and came in about $20 million below plan, as factory consolidations caused production hiccups and logistics bottlenecks held up shipments. That reversed earlier promises that the segment's margins would improve year over year all year. The good news is that the demand side looks intact, with double-digit order growth in prepared foods. Validation this quarter would mean those delayed shipments turning into revenue, segment margins stabilizing, and evidence that roughly 1.3 million square feet of facility consolidation is being absorbed without fresh disruption. Another round of shipment delays or unrecovered cost leakage would challenge the idea that this was a one-quarter problem.
The protein business has been the steadier engine, posting 11% revenue growth and margins near 24% last quarter, although about 200 basis points of that came from tariff refunds that should not be treated as recurring. A margin closer to the low 20s would be a reasonable underlying result, not a warning sign. Investors should also want an update on the USDA poultry line-speed decision, which management framed as a multi-year tailwind given that fewer than 20% of more than 350 US lines run at higher speeds. Cross-selling synergy orders, already ahead of pace at $75 million over 18 months, and order intake relative to the $1 billion mark will indicate whether the poultry investment cycle is broadening or maturing. Cost inflation in logistics and metals, which has been outpacing price increases with a lag, and free cash flow conversion, which slipped to 58% year to date, round out the checklist.
Sentiment remains bearish, though slightly less so than ahead of the prior report. The chart reflects that caution. At about $108.59, the stock trades well below its 200-day moving average near $132 and only about 5% above its post-earnings low, a much lower range than the previous quarter's. Leverage now within the 2x to 2.5x target and a fresh $200 million buyback authorization give management tools to support the shares if results cooperate.
Ultimately, this report comes down to whether execution catches up with demand. Strong orders are not in question. What matters is whether prepared foods converts its backlog on time and at better margins, because a fourth-quarter-heavy plan with consensus near the top of guidance needs a clean third quarter to remain credible.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-21 | |
| Sep-16 | |
| Aug-25 | |
| Aug-17 | |
| Aug-06 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-21 | |
| Jul-14 | |
| Jul-07 | |
| May-14 |
