HNI Faces Proof Test On Office Demand Rebound And Bigger Steelcase Synergy Promise
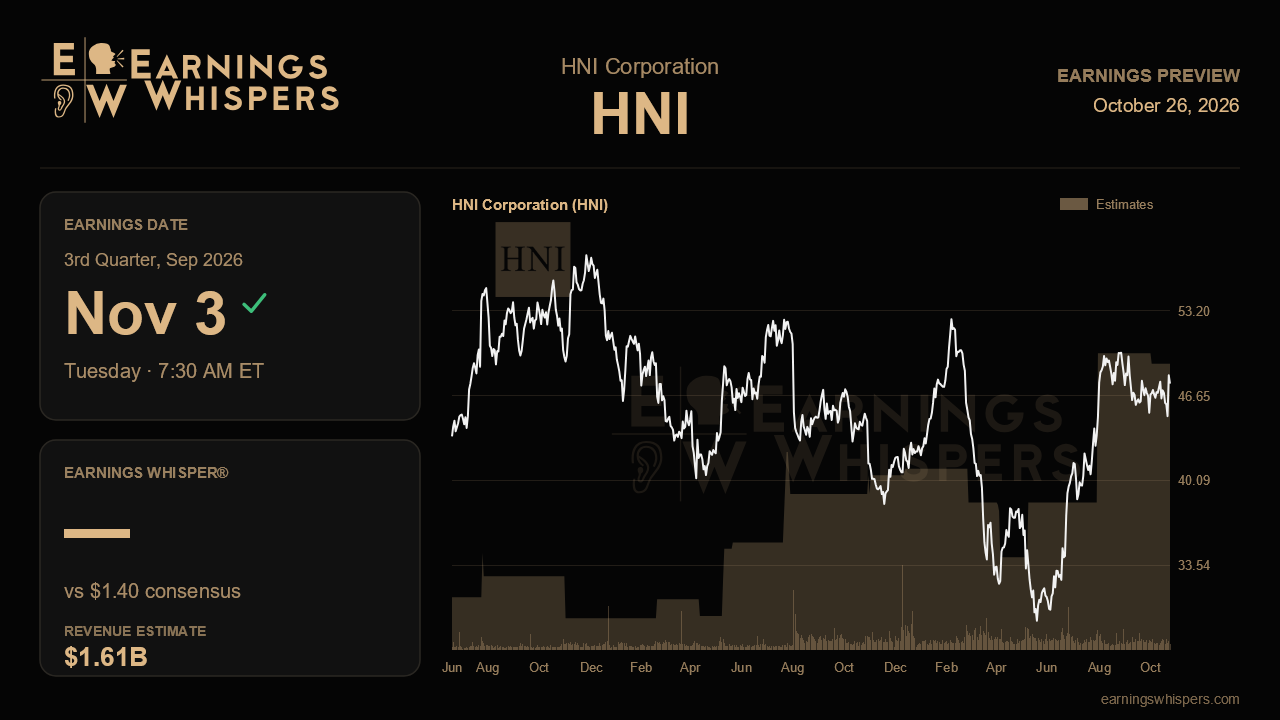
Three months ago HNI told investors that its early-year stumble was a pause rather than a turn. Workplace orders swung back to growth, backlog firmed, the full-year earnings growth target jumped, and management hinted that the Steelcase merger would deliver more savings than the $120 million it had been promising. The third-quarter report, due before the open on November 3, is the first real chance to see whether that rebound carried through the summer or was simply a catch-up from a weak January and February.
The Street's numbers sit squarely on management's own roadmap. Consensus calls for earnings of $1.40 per share, up about 27% from $1.10 a year ago, which lands right in the mid-to-high 20% growth range the company guided for the quarter. Revenue is expected near $1.61 billion, more than double the $683.8 million reported a year earlier. That headline growth rate is almost entirely the product of folding in Steelcase, so it says little about underlying health. The more telling comparison is sequential: sales are expected to rise from $1.47 billion last quarter, and that step-up needs to come from genuine organic demand rather than acquisition math.
That makes order data the centerpiece. Last quarter legacy workplace orders rose 5%, backlog grew 5%, and management said order growth had accelerated above that pace in the most recent five weeks, particularly in contract business. It then framed second-half legacy workplace growth at mid-to-high single digits. Validation would look like organic sales growth in that range, orders that held or built on the late-quarter acceleration, and Steelcase order trends running at least in line with the legacy business. A return to flat or low-single-digit orders would undercut the story, especially since management leaned heavily on improving office fundamentals, including four straight quarters of rising leasing activity and the strongest net absorption since 2019. If those leading indicators are real, they should increasingly be showing up in HNI's backlog.
Margins and synergies are the second test. The residential building products segment posted a 20.4% margin last quarter, a big improvement helped by tariff timing, and both segments were guided to expand margins this year. Residential volume, however, was expected to slip by low single digits in the back half, with price doing the work of holding revenue flat, so any erosion in pricing power there would hurt. On Steelcase, management said a bottom-up project list already exceeded $120 million and that a higher target would follow. A credible, quantified increase, paired with evidence that large Steelcase projects are not slipping, would strengthen the case that 20% to 25% full-year EPS growth is conservative. Tariffs remain a wildcard after weighing on operating margin by roughly 150 basis points last quarter.
Sentiment has warmed but remains cautious. Readings are still net bearish, though noticeably less so than ahead of the last report, and the stock has gained about 7.6% since then, beating the S&P 500 by more than four points. At $47.57, shares sit comfortably above their 200-day average of $41.80 and in the upper half of their post-earnings range, though still roughly 6% below the $50.41 high, so this is not a breakout setup. The trading range has also narrowed sharply from the prior quarter's wild swing, suggesting the market has moved from doubt to cautious acceptance.
Because consensus simply mirrors guidance, hitting $1.40 is unlikely to move the needle on its own. The question is whether organic workplace orders kept accelerating and whether management can put a bigger, more concrete number on Steelcase synergies. Deliver both, and the recovery narrative earns further credibility. Falter on orders, and the second-quarter rebound starts to look like a one-time recovery from a soft start.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-15 | |
| Sep-21 | |
| Aug-25 | |
| Aug-17 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-24 | |
| Jul-15 | |
| Jul-14 | |
| Jun-08 | |
| May-22 | |
| May-18 | |
| May-13 |
