HNI Beats Big And Raises Steelcase Synergy Targets, But An Unchanged Full-Year Guide Tempers The Upside
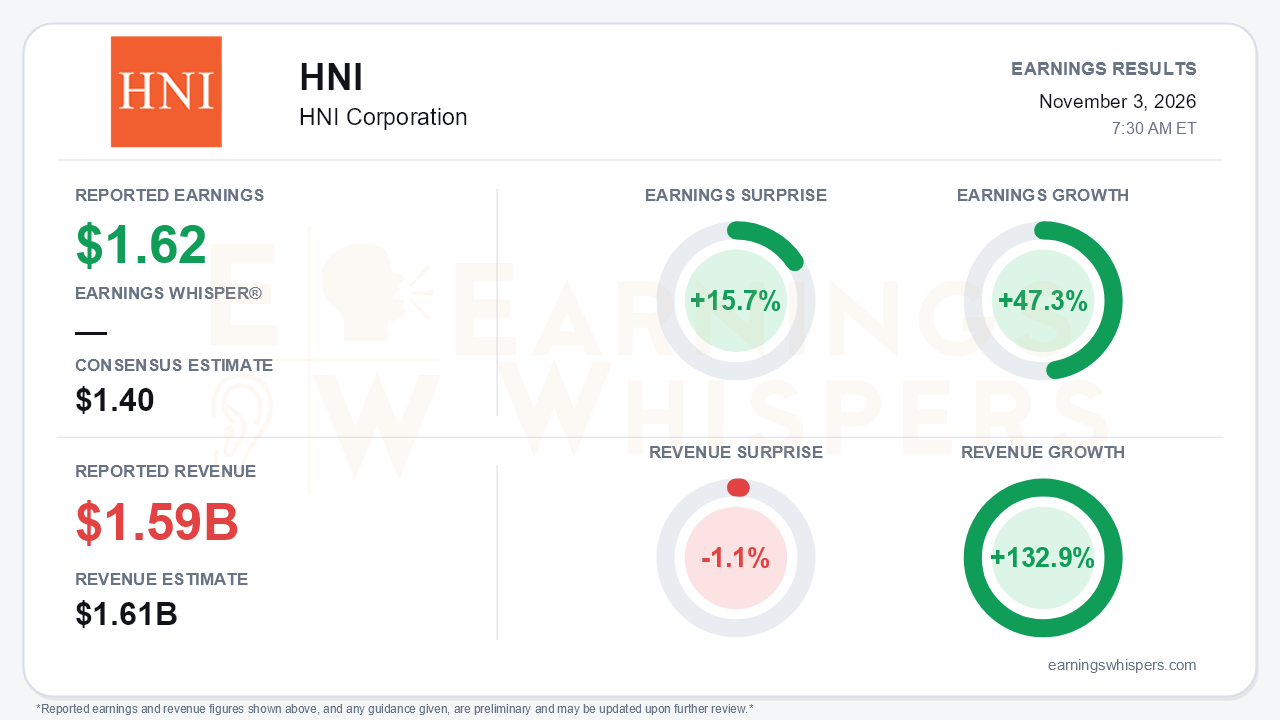
HNI Corporation delivered the kind of quarter that rewards investors who backed the Steelcase thesis. Third-quarter non-GAAP EPS of $1.62 beat the $1.40 consensus by 15.7% and grew 47.3% year over year. That growth far outpaced the mid-to-high 20% range management had pointed to on the second-quarter call. Revenue of $1.593 billion grew 132.9% on the Steelcase consolidation but missed the $1.61 billion consensus by 1.1%. The central tension is that HNI raised nearly every long-dated integration target while holding its 2026 EPS growth outlook at 20-25%. Steelcase's contribution this year was cut to EPS-neutral. The beat was emphatic, but it did not flow through to the full-year number.
The quality of the beat deserves scrutiny. Management said SG&A cost management, price-cost, productivity savings and investment timing more than offset slightly lower-than-expected volume growth. The volume shortfall was mainly in workplace, which modestly missed internal plans. Investment timing in particular tends to reverse rather than recur. The GAAP picture is also less flattering. GAAP EPS of $1.23 rose 39.8%, but consolidated GAAP operating margin fell 80 basis points to 8.6%. That decline reflects $24.8 million of Steelcase purchase-accounting amortization, $7.3 million of restructuring charges, and Steelcase's structurally thinner profitability (5.5% GAAP and 8.5% non-GAAP operating margin). The cleaner signal is in legacy HNI. Legacy Workplace Furnishings posted a record 16.2% non-GAAP operating margin, up 390 basis points. Residential Building Products expanded margin 180 basis points and grew operating profit 16% despite a weak housing market.
Beneath the headline, the top line clearly improved. Organic sales rose 5.6%, compared with slight growth in the second quarter and a 3% decline in the first. Both segments posted volume growth for the first time in this cycle: roughly 2% in workplace and 4% in residential. Workplace orders rose 6%, up from 5% in the prior quarter. Contract customers outpaced small and medium-sized businesses, and Steelcase orders ran ahead of legacy trends. Residential orders improved to 4% growth from flat, driven by double-digit gains in remodel-retrofit that offset softer new construction. Both segments reported continued year-over-year order growth over the most recent five weeks.
The forward story is a split between 2026 and 2027. On the positive side, Steelcase synergies were raised to at least $130 million from $120 million, and the original $120 million is now expected by the end of year four. Year-two accretion rose to $0.70 from $0.60. A pilot program to sell HNI brands through Steelcase dealers opens a revenue-synergy angle that was not previously part of the case. Leverage dropped to 2.0x from 2.4x, and the tax rate guide fell to roughly 24%. Management called the fourth quarter the combined company's margin trough and expects both sales growth and double-digit EPS growth in 2027.
The near-term offsets, however, are substantive:
- **Price-cost drag:** accelerating steel, diesel and fuel inflation creates a $0.10-0.15 headwind in the fourth quarter, with neutrality not expected until early-to-mid 2027.
- **International weakness:** Steelcase's EMEA business is softening amid war-related turmoil.
- **Slower legacy growth:** legacy workplace growth slows to low single digits in the fourth quarter, against a roughly three-point extra-week comparison.
- **Project and vertical softness:** large projects are being pushed out on installation-labor tightness, and education and state/local government demand is soft.
- **Housing:** management expects new construction to stay weak through 2027.
Cash generation also bears watching. Nine-month operating cash flow of $163.3 million trailed the prior year's $198.9 million, as working capital absorbed cash during integration.
Investors were not leaning bullish going in. Earnings Whispers sentiment improved modestly, from -0.45 to -0.38, but remained negative. Price action told a more constructive story. Shares had climbed 12.4% since the open after the July report, to $49.67. That left the stock about 18.5% above its 200-day moving average and just 2.4% below the inter-earnings high of $50.91, set the day before the release. Trend readings are broadly positive on price, momentum and AVWAP, while sequential growth is neutral. The stock therefore entered the report near the top of its range, with much of the improving narrative arguably already reflected. That makes the unchanged full-year guide and the Steelcase cut more consequential than the size of the beat suggests.
The bottom line is that HNI's third quarter strengthened the multi-year earnings case. Organic growth turned decisively positive, legacy margins hit records, and synergy and accretion targets moved higher. However, the beat leaned partly on cost timing, and 2026 Steelcase accretion has evaporated under inflation and international weakness. Holding the full-year guide steady signals that the fourth quarter will absorb much of the upside. The investment debate now rests on management's 2027 recovery: price-cost normalization, synergy capture and continued order growth all need to arrive on schedule.
Read our earnings preview for HNI Corporation: https://www.earningswhispers.com/article/HNI/21485
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-15 | |
| Sep-21 | |
| Aug-25 | |
| Aug-17 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-24 | |
| Jul-15 | |
| Jul-14 | |
| Jun-08 |
