Hamilton Lane's Evergreen Flows Face A Key Test After A 17% Slide
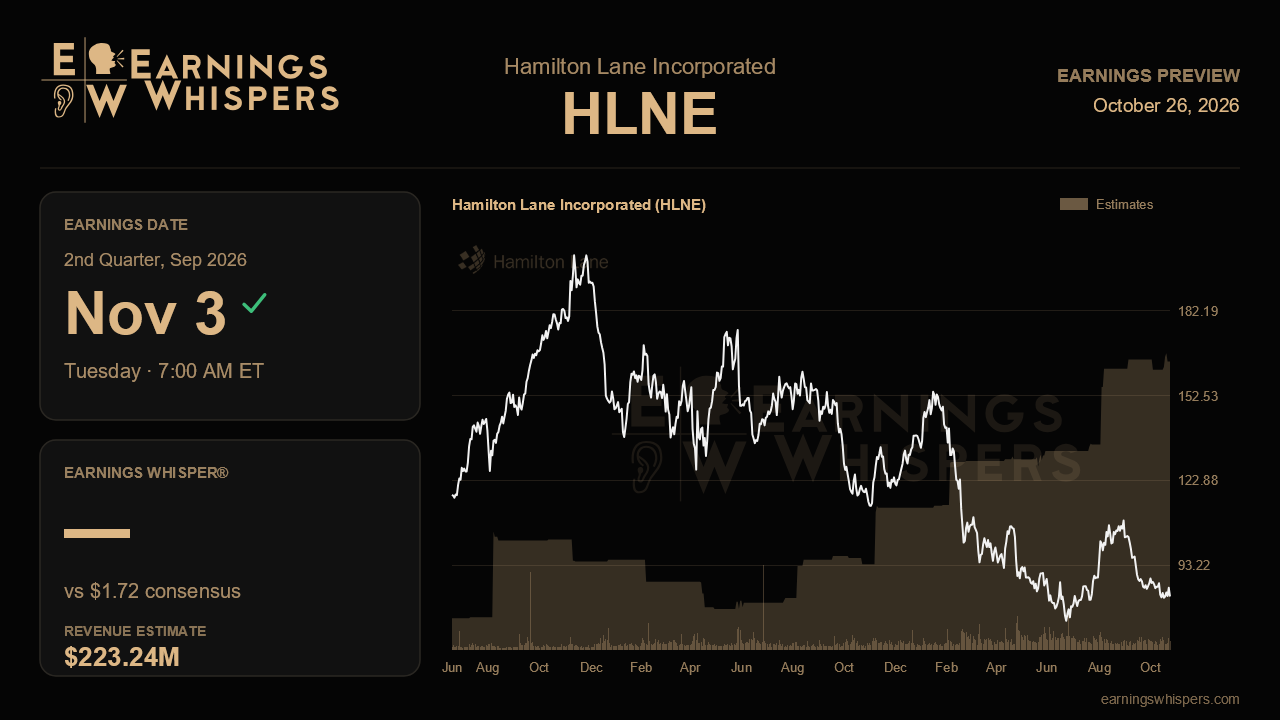
Hamilton Lane heads into its fiscal second-quarter report with a split personality. The closed-end fundraising machine is humming, margins are at records and fee rates keep creeping higher, yet the stock has fallen 17% since the last report while the S&P 500 was essentially flat. The reason is evergreen flows. Those perpetual vehicles have been the growth engine investors pay a premium for, and last quarter they cooled sharply. This report is largely about whether that cooling was a pause or the start of a trend.
The Street is looking for earnings of $1.72 per share on revenue of $223.2 million, up roughly 12% and 17% from a year ago. That is solid growth, but both figures sit well below last quarter's $1.94 and $275.3 million. The sequential step down makes sense: the June quarter was boosted by strong fee-related performance revenue, which drove fee-related earnings up 49% and lifted the FRE margin to 53% from the 50% level of the prior three calls. Performance fees are lumpy, so the more telling question is whether management and advisory fees, which rose 21% last quarter, keep compounding at a similar clip. Without formal guidance, the cleanest checkpoints are fee-earning AUM, which reached $83.7 billion, and the blended fee rate, which has climbed from 65 basis points to 69 as the mix shifts toward specialized funds. A margin that holds near the low-50s without a performance-fee tailwind would be meaningful evidence of operating leverage.
The evergreen numbers will carry the most weight. Net inflows slid to about $640 million in the June quarter from more than $1 billion, more than $1.2 billion and a record $1.6 billion in the three quarters before. For the first time, not every fund was positive, with the non-US multi-strategy equity fund in net outflow as clients rebalanced, harvested gains and redeemed to fund separate accounts. Management blamed a broad slowdown and investor jitters over negative private credit headlines, insisted the softness was temporary and said flows had already begun to swing back in July. A rebound toward the $1 billion range, with that non-US fund back in positive territory, would validate the call. Another quarter near or below $640 million would suggest the slowdown is structural, particularly since management already described newer US evergreen products as a grind until they reach roughly $1 billion in scale. Early traction from the third wire house platform and the six senior sales hires would help, though onboarding means that payoff may still be ahead.
The closed-end side offers the counterweight. Direct Equity Fund VI closed at $3.8 billion, more than 57% above its predecessor, Secondary Fund VII held a roughly $1.3 billion first close, and Venture Fund II's $370 million first close already exceeds 60% of its predecessor's total. With five strategies in market, further closes and progress on the inaugural GP-led secondary fund would reinforce that institutional demand remains healthy even if wealth channel flows wobble. Balance-sheet monetizations tied to Russell, Securitize and Canoe add optionality, though they speak more to capital flexibility than recurring earnings power.
Sentiment has soured noticeably, with the bearish reading deepening to roughly 30% from about 17% heading into last quarter. The stock trades at $82.27, far below its 200-day moving average near $99 and only about 3% above its post-earnings low of $79.69, after briefly reaching almost $110. That tells you the market has priced in meaningful disappointment, which lowers the bar somewhat but does not remove it.
Ultimately, the report hinges on whether evergreen inflows reaccelerate as management promised. Steady fee growth and closed-end momentum are likely to show up again. If flows confirm the July rebound, the recent selloff could look overdone; if they stall, the record margins may not be enough to change the conversation.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-12 |
Chubb Wealth and Hamilton Lane partner on private markets in Hong Kong
HLNE
Private Banker International
|
| Oct-06 | |
| Sep-30 | |
| Sep-29 | |
| Sep-21 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Aug-12 | |
| Aug-04 | |
| Aug-04 |
