Hamilton Lane Beats On EPS But Misses On Revenue As Evergreen Flows Re-Accelerate And FRPR-Driven Growth Cools
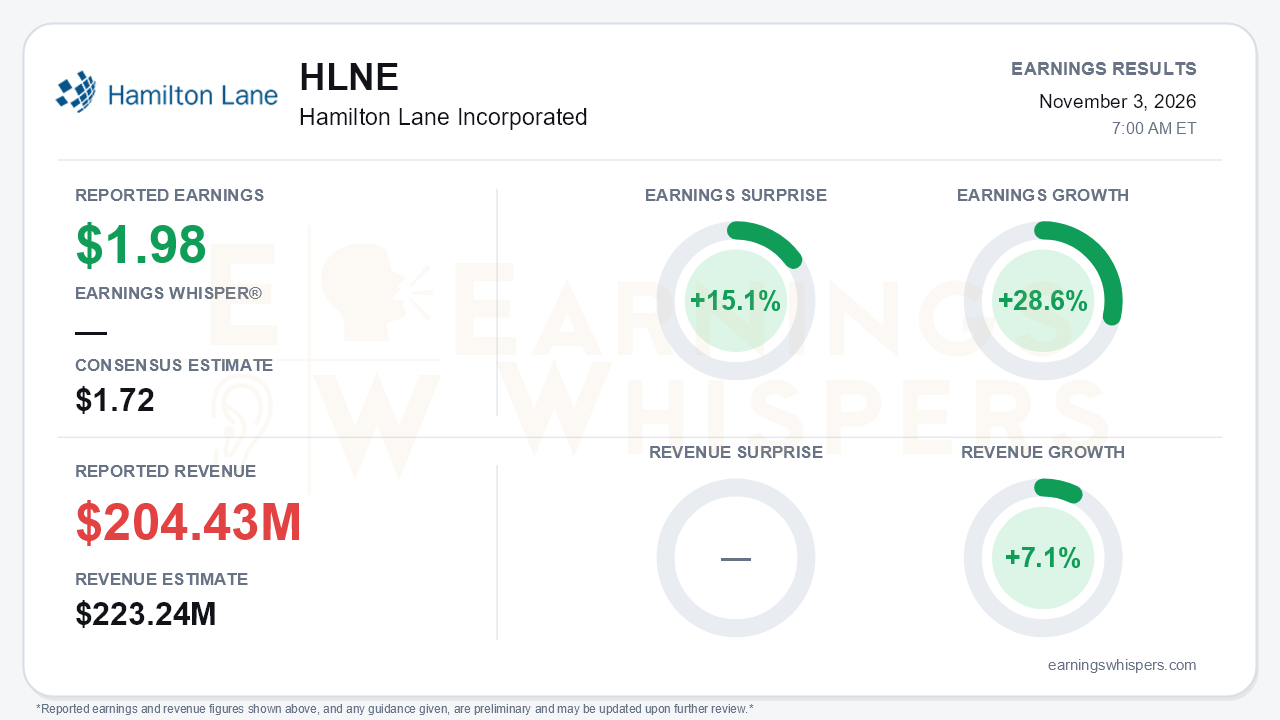
Hamilton Lane (NASDAQ: HLNE) delivered a split decision in its fiscal second quarter. Earnings of $1.98 per share beat the $1.72 consensus by 15.1% and grew 28.6% year over year. Revenue of $204.43 million, however, missed the $223.24 million consensus by 8.4% and grew just 7.1% year over year. That gap is the central tension of the quarter. The firm's asset-gathering engine is clearly working, led by re-accelerating evergreen flows and steady fee-earning AUM growth. But the outsized growth rates of earlier in the year, flattered by fee-related performance revenue (FRPR), are normalizing faster than the Street modeled.
The quality of the beat deserves scrutiny. The press release offered little beyond a dividend declaration, so the detail came from the call. Management noted that consolidated seed vehicles are adding noise to GAAP results and that the Securitize stake is being marked to market while under lockup. A $15.6 million Securitize gain was recognized, and further balance-sheet gains are flagged: roughly $17 million from Canoe next quarter and about $18 million from Russell in calendar Q1 2027. These gains are real value, but they are not recurring fee income. Investors weighing a bottom-line beat against a top-line miss should keep that distinction in mind. On a year-to-date basis, the slowdown is visible:
- Fee-related revenue growth cooled to 29% from 44% through Q1.
- Fee-related earnings growth fell to 34% from 49%.
- Management and advisory fee growth eased to 18% from 21%.
- FRE margin slipped to 52% from 53%, and the CFO cautioned that the FRPR-elevated margin is not expected to hold at Q1 levels.
The call nonetheless preserved a credible growth story underneath those decelerating comparisons. Total fee-earning AUM rose to $86 billion, up 12% year over year. That continues a steady climb from $79.1 billion three quarters ago, $82 billion last quarter-end and $83.7 billion in Q1. Specialized funds FEAUM topped $44 billion, up 25%, and the blended fee rate improved to 69 basis points from 67 basis points in the back half of fiscal 2026. The most encouraging data point was evergreen. Net inflows rose to about $800 million from roughly $640 million in Q1, with September alone contributing around $400 million. That is a meaningful recovery from the March outflow and soft April flagged two calls ago. Evergreen AUM reached about $21 billion, up 42% year over year, with no gates. Unrealized carry ticked up to about $1.6 billion after holding near $1.5 billion for three calls.
The forward catalyst list is unusually full:
- A new FactSet data and analytics partnership adds multi-year recurring revenue with an agreed floor, layered on data revenue already up 15% year to date.
- A Columbia Threadneedle partnership opens a public/private product channel.
- Secondary Fund VII held a roughly $1.3 billion first close and is already earning fees, with retroactive fees due on later closes.
- A first GP-led secondary fund, a segmented credit strategy and a third impact fund are in the market.
Bears have legitimate ammunition, though. Customized separate account revenue dipped slightly year over year on one-time true-ups, and SMA FEAUM grew only 2%. New contracted SMA mandates fell to $1.7 billion from about $3.6 billion in Q1. Expenses rose 27% year to date, with compensation up 26%, roughly matching revenue growth and limiting operating leverage. Evergreen flows remain sensitive to industry headlines. The leadership transition adds execution uncertainty: Mario Giannini retires March 31, Hartley Rogers becomes co-CEO and Erik Hirsch moves to Executive Co-Chairman. Management framed the change as evolutionary.
The market setup is more complicated than the EPS surprise implies. Shares entered the report at $87.84, down 11.3% since the open following the August report. They sit about 9.9% below the 200-day moving average and roughly 20% below the August 31 inter-earnings high of $109.88. They have recovered about 10% from the October 15 low of $79.69. Investor sentiment was roughly unchanged and mildly negative, moving from -0.167 to -0.160. That suggests expectations were already subdued rather than euphoric. The trend readings are mixed, with price and AVWAP trends still negative while sequential growth and momentum are neutral.
The bottom line is that Hamilton Lane's quarter was better beneath the surface than its revenue miss suggests, but less clean than its EPS beat implies. Evergreen re-acceleration, rising FEAUM and fee rates, new fundraising, and the FactSet recurring-revenue stream support the long-term thesis. Meanwhile, moderating FRPR-driven growth, a softer SMA pipeline, balance-sheet gains in the earnings mix and a CEO transition explain why a stock already trading below its 200-day average may need cleaner fee-revenue delivery to regain its footing. Management reaffirmed the $2.40 annual dividend target, an 11% increase.
Read our earnings preview for Hamilton Lane Incorporated: https://www.earningswhispers.com/article/HLNE/21484
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-12 |
Chubb Wealth and Hamilton Lane partner on private markets in Hong Kong
HLNE
Private Banker International
|
| Oct-06 | |
| Sep-30 | |
| Sep-29 | |
| Sep-21 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 |
