Hagerty Tests Its Raised 2026 Outlook As Underwriting Margins Face Scrutiny
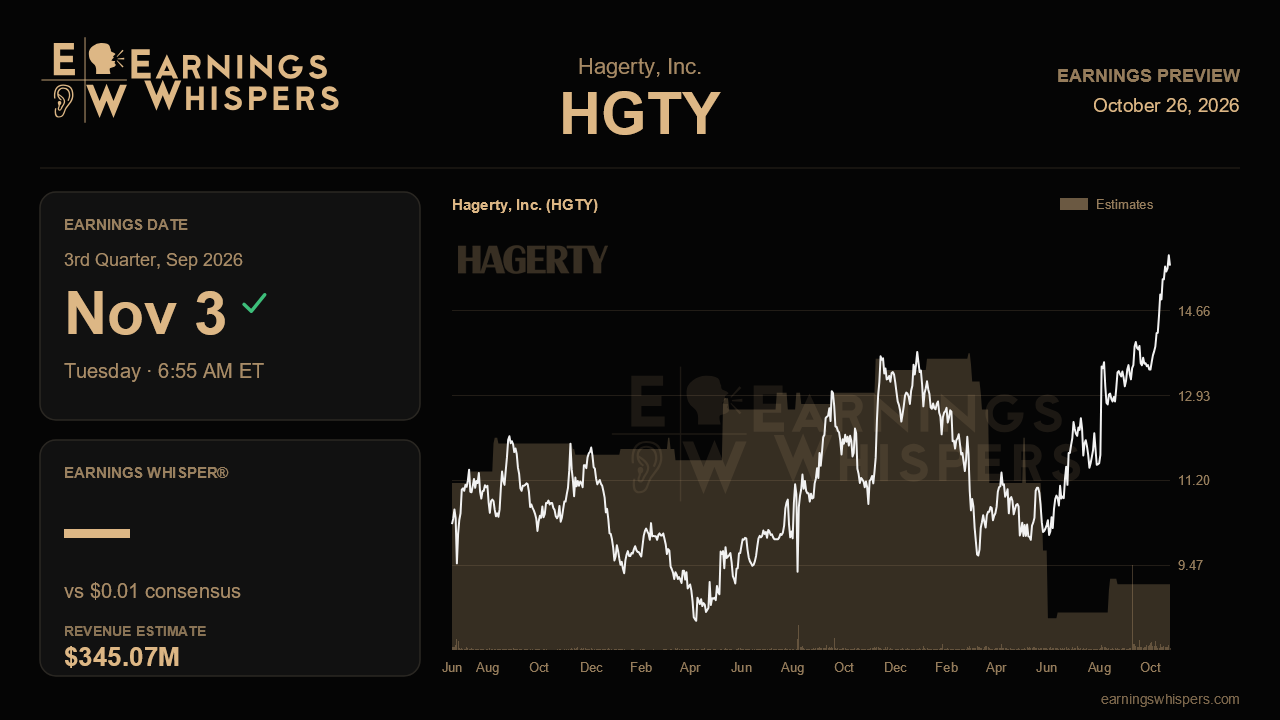
Hagerty heads into its third-quarter report with a split personality. The operating story has rarely looked better: written premium growth accelerated to 19% in the first half, member additions hit records, and management raised every major full-year target last quarter. The reported numbers, however, are expected to look ugly. That gap between momentum and optics, plus a stock that has run hard since the last report, makes this release a test of whether the underlying engine can keep outrunning accounting noise and a creeping loss ratio.
Wall Street expects earnings of about a penny per share on revenue of roughly $345.1 million when Hagerty reports before the open on November 3. That implies a 92% drop in EPS from the $0.13 earned a year ago and a 9% revenue decline from $380.0 million. Those figures look like contraction, but they need context. GAAP results remain distorted by the transition away from Markel as fronting carrier, which management said carries roughly $199 million in full-year transition cost, including $64 million of deferred seating commission amortization in the second quarter alone. The capitalization benefit from deferred acquisition costs also shrinks to about $15 million in the back half of the year and disappears in the fourth quarter, so headline profitability has fewer tailwinds from here.
The more useful yardstick is management's guidance. Hagerty lifted its 2026 revenue outlook to $1.325 billion to $1.340 billion from $1.28 billion to $1.30 billion, and the full-year consensus of $1.32 billion sits just below the bottom of that range. In other words, analysts are not fully buying the raise. The company also boosted adjusted EBITDA guidance to $270 million to $280 million from $236 million to $247 million and flipped its GAAP net income forecast from a loss of $41 million to $51 million to a profit of $18 million to $30 million. After three quarters of steadily rising targets, simply reaffirming may feel like a pause; another nudge higher, or at least a firm signal toward the top of the ranges, would validate the confidence on display last quarter.
The operating checklist is clear. Premium growth has been driven by policy count rather than rate, so new member additions and the distribution pipeline matter most. State Farm agents were selling in 37 states with 14 more in conversion, Progressive widened eligibility to cars 25 years and older, Enthusiast Plus expanded beyond Colorado into three more states in July, and the Liberty Mutual relationship is ramping. Evidence that these channels are compounding would confirm the narrative. The Bennetts acquisition, which triples UK scale, should also start to show up. On the other side of the ledger, retention slipped to 88% from a long-held 89%, and the combined ratio climbed to 90% from 87% with no reserve releases and management flagging inflationary pressure. Further erosion in either would challenge the idea that growth is coming without cost. Marketplace, which management said is already beating its near-breakeven plan on the strength of Broad Arrow auction sales, is another swing factor given its lumpy nature.
Expectations have shifted in an interesting way. The stock has gained about 23% since the last report while the S&P 500 slipped 2%, and at $15.58 it sits well above its 200-day moving average and within roughly 3% of its post-earnings high of $15.98, effectively testing a breakout. Yet sentiment has swung from mildly bullish to noticeably bearish, suggesting skepticism is building even as the shares climb.
Ultimately, this report hinges on underwriting discipline. If Hagerty can show the combined ratio stabilizing around its recent range while count-driven premium growth stays near 19%, the raised outlook looks credible and the near-zero EPS headline becomes an afterthought. If loss costs keep drifting higher and retention softens again, the rally will have priced in more than the quarter delivers.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-09 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 | |
| Sep-17 | |
| Sep-16 | |
| Sep-09 |
