Hagerty Beats And Raises Again, But A Reserve Release Does The Heavy Lifting As Premium Growth Cools
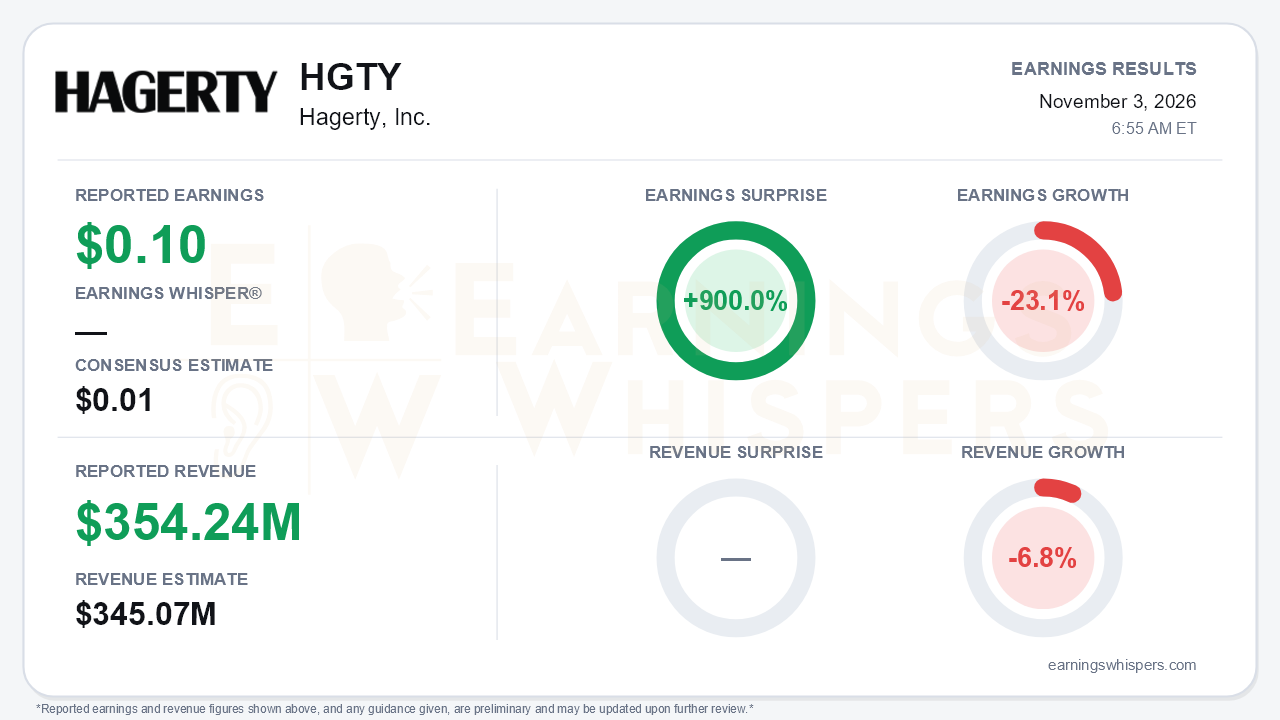
Hagerty delivered a large third-quarter beat on a thin earnings base and raised its full-year profit outlook for the second straight quarter. Earnings were $0.10 per share against a $0.01 consensus, a 900.0% surprise. Revenue of $354.24 million topped the $345.07 million estimate by 2.7%. Even so, earnings fell 23.1% year over year and revenue declined 6.8%. The central tension is the source of the upside. A meaningful share of the profit improvement came from favorable loss estimates and accounting tailwinds tied to the Markel transition, while the organic engine slowed across several fronts.
The headline numbers need some translation. Reported revenue is shrinking by design. Under the Markel Fronting Arrangement, Hagerty now keeps 100% of the premium and risk, so $138 million of intercompany commission revenue was eliminated in consolidation during the quarter. The 6.8% decline compares against the $380 million originally reported for the year-ago quarter. The company's recast presentation shows a 9% decline.
There is a similar wrinkle on earnings. The release shows adjusted diluted EPS edging up to $0.10 from $0.09. On a GAAP basis, net income fell to $36 million from $46 million and diluted EPS slipped to $0.08 from $0.11, partly because the prior year included a sizable tax benefit. The underlying economics look much stronger:
- Adjusted EBITDA rose 64% to $97 million.
- The Hagerty Re combined ratio improved to 79.7% from 89.6%.
- The loss ratio fell to 32.6% from 42.0%.
The quality of those margins deserves scrutiny, however. Both ratios were flattered by a $26 million reduction to current-accident-year loss estimates.
That reserve benefit also shapes the guidance story. Full-year adjusted EBITDA guidance moved to $305-$315 million from $270-$280 million, and GAAP net income guidance rose to $48-$60 million from $18-$30 million. Yet per the call, roughly $26 million of the $35 million EBITDA raise reflected the reserve release, leaving only about $9 million from operations.
Management tied the lower loss estimates to fewer physical-damage and liability claims and a 40% larger in-house claims team. That is a credible operational explanation, but investors should not extrapolate a sub-80% combined ratio. A further issue looms for 2027: a $52 million EBITDA benefit this year from capitalizing MGA acquisition costs will not repeat, which complicates next year's bridge.
Beneath the profit upgrade, growth is clearly decelerating:
- **Written premium:** Quarterly growth slowed to 16% from 19% in the second quarter and 18% in the first. Management partly blamed tougher comparisons. Full-year guidance now sits at the high end of 16%-17%.
- **Net new policies:** Analysts noted net new policies in force were slightly below the prior year.
- **Retention:** Retention eased to 88.2% from 88.6%.
- **Drivers Club:** Paid membership growth cooled to 6% from 10%.
- **Marketplace:** Revenue fell 6% after rising 48% in the prior quarter. Auction sales jumped 65% and private sales 88%, but lower inventory sales more than offset that strength.
Management also flagged a soft personal auto and home market that is slowing new business at partner carriers. Notably, it warned that high-end collector car prices may "take a breather" after a strong multiyear run, and said 2027 planning will not assume continued Broad Arrow and private-sales momentum.
The growth pipeline still offers real catalysts:
- **State Farm:** Classic Plus is now selling in 41 states, up from 37, with conversions underway in 26 states versus 14 last quarter.
- **Bennetts:** The acquisition of the UK's second-largest specialty motorcycle broker closed October 8, giving Hagerty a broader European base.
- **Barrett-Jackson:** The auction house named Hagerty its official insurance partner.
- **Productivity:** AI-driven automation lifted member-service productivity by about 20%.
- **Drivers Club redesign:** A shift toward free and trial memberships rolls out next year.
The balance sheet also strengthened. Unrestricted cash reached $461 million against $247 million of debt, and operating cash flow climbed 48% to $280 million.
The transitional cost runoff is the cleanest forward tailwind. Markel-related amortization fell from $89 million in the first quarter to $64 million, then $36 million, and should drop to roughly $10 million in the fourth quarter. That should allow GAAP earnings to converge with adjusted results.
The market setup is more complicated than the surprise implies. Shares closed at $15.89 ahead of the report:
- up 25.5% since the open following the August release;
- nearly 32% above the 200-day moving average;
- within 1% of the $16.00 52-week high set October 27.
Investor sentiment moved the other way, slipping from mildly positive (0.08) to mildly negative (-0.14). Investors appear to have been growing more skeptical even as the stock rallied into the print. Price-based trend readings remain constructive, but a stock trading near its highs leaves less room for a raise that leaned on reserves.
The bottom line is that Hagerty's quarter validated the economics of the Markel transition, with rising cash generation and fading transitional charges. But the quality of the beat and the guidance raise is weaker than the headline suggests. Premium, membership and marketplace growth all decelerated, and management was openly cautious on 2027. Bulls can point to State Farm expansion and the coming GAAP earnings normalization. Bears have legitimate ammunition in reserve-driven upside, a non-recurring $52 million tailwind and a stock already priced near its highs.
Read our earnings preview for Hagerty, Inc.: https://www.earningswhispers.com/article/HGTY/21483
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-09 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 |
