Louisiana-Pacific's Siding Rebound Faces Its Proof Point As OSB Losses Deepen
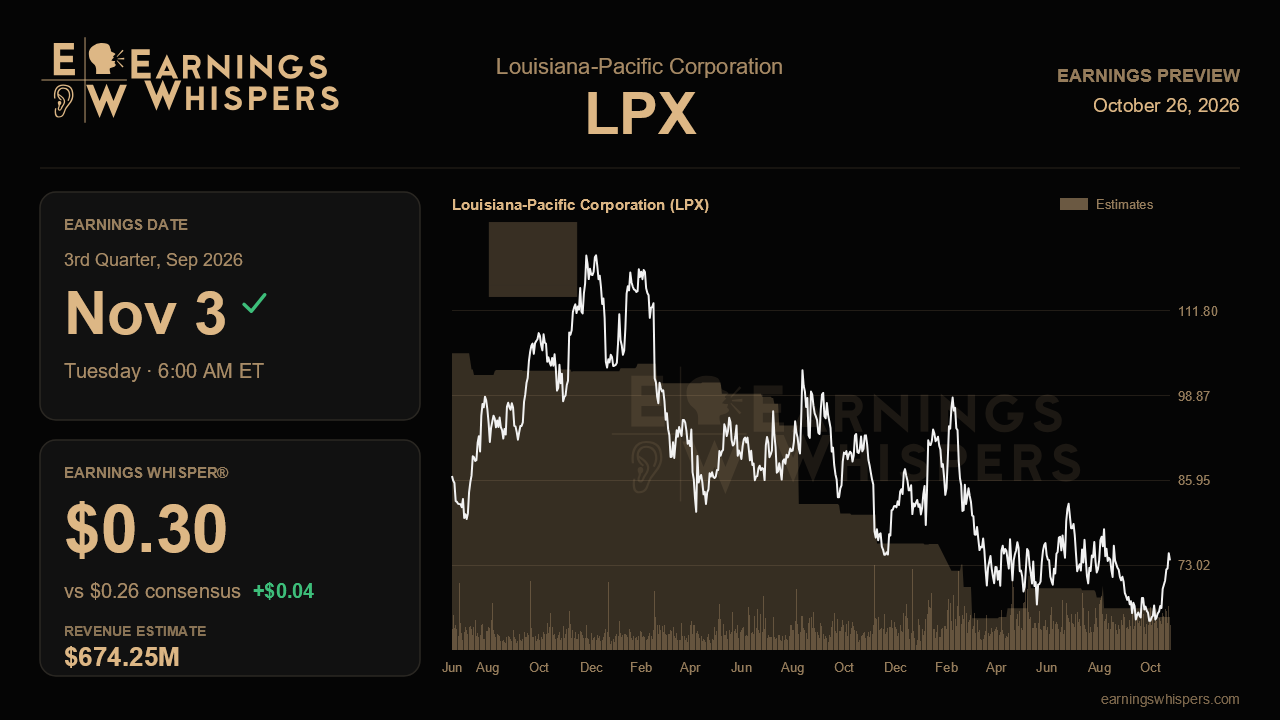
Louisiana-Pacific heads into its third-quarter report with a split personality. Its siding business, the franchise that justifies the stock's valuation, is supposed to be back in growth mode after a bruising destocking cycle. Its oriented strand board business, meanwhile, has gone from roughly breakeven to a serious money loser in the span of two quarters. When the company reports before the open on November 3, the question is whether the siding recovery management promised in the summer actually showed up, and whether it was large enough to keep OSB from swallowing the story.
The Street is braced for a weak bottom line. Consensus calls for earnings of $0.26 a share, down about 28% from the $0.36 earned a year ago, on revenue of $674.3 million, up a modest 1.7%. That combination says plenty: the top line is holding up, but mix is moving the wrong way as OSB losses dilute siding profits. The whisper number sits at $0.30, a meaningful cushion above consensus for a figure this small, suggesting that some investors expect the siding guidance to land at the upper end or OSB pricing to prove less punishing than feared.
Management's last call set out a clear scorecard. Executives guided third-quarter siding revenue to $460 million to $470 million, with the low end matching the prior record, and said the segment would return to year-over-year growth in both volume and revenue. That was a sharp improvement from the spring, when they had warned of a roughly 10% second-quarter volume decline. The supporting evidence was encouraging: channel inventories had normalized, distributor sell-through hit a five-quarter high, order intake beat four of the prior five quarters, and shed volumes jumped about 30% sequentially. Validation this quarter means siding revenue inside or above that range, margins near the 25% to 26% full-year target, and continued mid-single-digit growth in expert finish, the premium prefinished line where new capacity at Green Bay and Bath is ramping. The company also flagged an opportunity in distributor disruption, aiming to sign new committed siding partners by October 1 without any coverage gap. Any sign of lost shelf space during that handoff would undercut the share-gain narrative.
The second-quarter siding margin of 26% came despite equipment failure at Dawson Creek, flooding at Swan Valley and higher freight costs. Management called those timing issues and said mills were back to steady state, so a clean quarter should show margin recapture. If freight, which management tied to constrained capacity and crude prices, keeps nibbling at profitability, that explanation will look less like a one-off.
OSB is where the risk sits. Guidance has slid at each call, and the third quarter was pegged at about a $45 million EBITDA loss, with the full year near negative $120 million. Prices had already fallen about 6% since May and ended the second quarter below the company's own guidance algorithm, near 20-year inflation-adjusted lows. Another downward revision for the fourth quarter would extend a troubling pattern; stabilization would be a relief. The $70 million capital spending cut, concentrated in deferred OSB maintenance, protects cash but deserves scrutiny for its longer-term cost. A CFO transition, with Aaron Howald now in the seat, adds a fresh voice to the outlook.
Sentiment has warmed noticeably, with bullish readings at 32% versus under 5% before the last report, yet the stock has merely tracked the market, slipping 1.7% against a 2.1% decline for the S&P 500. At $73.76, shares sit below the 200-day average of $75.65 and in the upper half of the post-earnings range of $62.18 to $79.48. Ultimately, this report turns on one thing: whether siding delivers record-level revenue with intact margins. If it does, OSB looks like a cyclical drag on a healthy franchise. If it doesn't, the recovery thesis loses its anchor.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-06 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Sep-15 | |
| Sep-08 | |
| Sep-03 | |
| Sep-01 | |
| Aug-27 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-31 | |
| Jul-09 |
