Louisiana-Pacific Beats As SmartSide Returns To Volume Growth, But A Thin Q4 Guide And OSB Retrenchment Temper The Turn
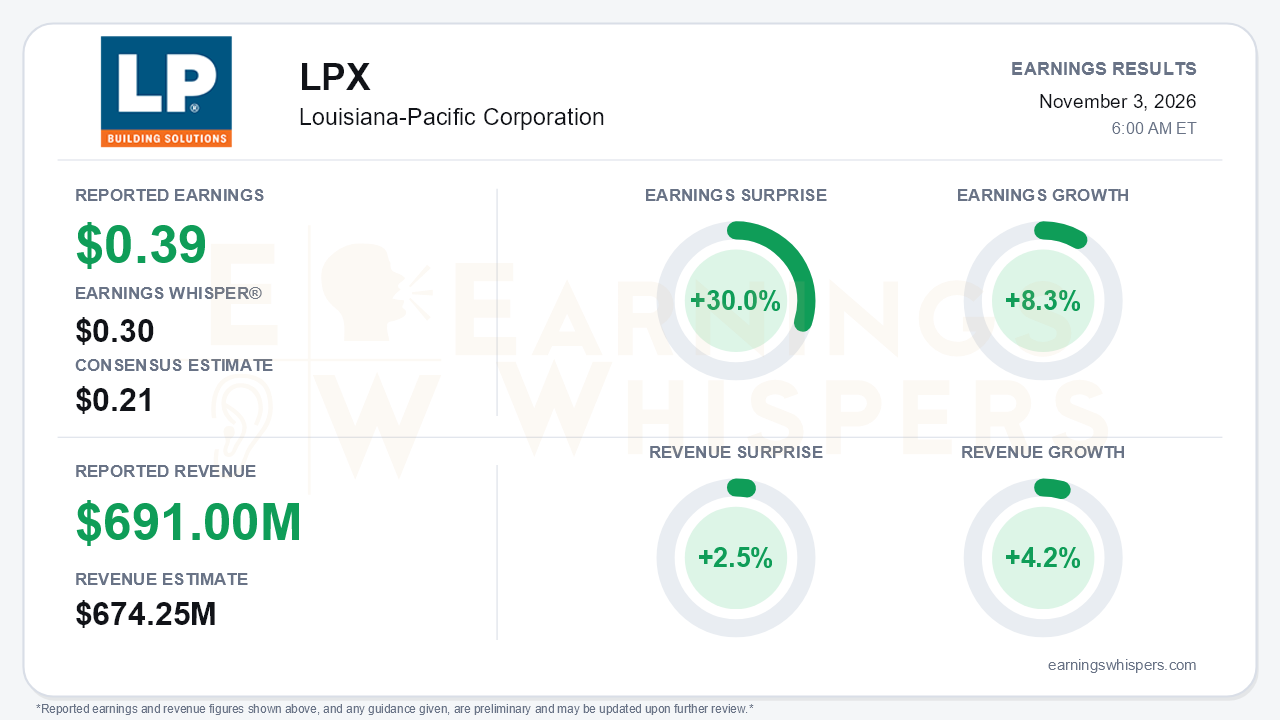
Louisiana-Pacific delivered the quarter siding bulls needed. Adjusted EPS of $0.39 beat the $0.21 consensus by 30.0% and cleared the $0.30 Earnings Whisper, while revenue of $691.0 million topped the $674.25 million estimate by 2.5%. More importantly, the direction of growth changed. Adjusted earnings grew 8.3% and revenue grew 4.2% year over year, a sharp break from a nine-month period in which sales fell from $2.14 billion to $1.93 billion and adjusted EPS dropped from $2.76 to $1.17. SmartSide drove the turn, posting record net sales of $473 million, up 7%, and returning to positive unit growth. That is the central development. The central tension is that the profit pool did not expand alongside the top line, and the fourth-quarter outlook points to a tougher stretch before 2027 pricing arrives.
The quality of the beat deserves scrutiny. Consolidated adjusted EBITDA was flat at $82 million, and gross profit fell to $114 million from $129 million as cost of sales rose faster than revenue. The EPS upside came largely from below the gross line. SG&A fell to $76 million from $95 million, and stock-based compensation was halved to $6 million. OSB's loss narrowed to $24 million from $27 million only because of $14 million in lower inventory reserve adjustments, a benefit management expects to fall away. GAAP EPS of $0.32 versus $0.13 looks more impressive than it is, because the year-ago quarter carried a $13 million impairment. Cash generation was a genuine positive. Operating cash flow rose to $112 million on an inventory drawdown, and cash climbed to $265 million from $228 million at the end of the second quarter.
Beneath the headline, siding's trajectory clearly improved. Volume rose 2% after declines of 18% in the first quarter and 11% in the second. Revenue beat the $460-470 million guide management set in the second quarter. ExpertFinish distributor sell-through rose 8% year over year and 13% sequentially, and management characterized channel inventories as lean and fourth-quarter orders as true end-use demand. Margins tell a less flattering story. Segment EBITDA of $119 million, roughly a 25% margin, rose just $2 million, as $23 million of net price gains were mostly absorbed by $19 million of raw material, freight and labor inflation. Full-year ExpertFinish shipments are now expected to be roughly flat, versus the mid-single-digit growth guided earlier in the year.
Guidance improved at the margin. Full-year siding revenue is now $1.66-1.67 billion, with the low end raised, and siding EBITDA is $415-425 million. The full-year OSB loss estimate improved to about $95 million from $120 million, and consolidated EBITDA guidance is $270-280 million. The fourth quarter is the soft spot. Management guided siding to $390-400 million in revenue and $80-90 million in EBITDA, about a 22% margin, which is below normal seasonality. It also expects siding price-cost to turn negative on MDI resin, paper overlay and freight inflation. OSB's loss is expected to deepen to roughly $35 million, which helps explain why consolidated fourth-quarter EBITDA is guided to just $30-40 million. Management framed the siding guide as deliberate conservatism after last year's fourth-quarter pull-forward.
The catalysts lean toward 2027. The overhauled SmartSide distribution network, anchored by Specialty Building Products plus exclusive regional partners, adds more than 100 locations and a sales force larger than LP's own. Taylor Morrison's vendor award bundles siding and OSB, and a 2027 list increase is expected to net about 3.5-4% from January. Management pointed to promising builder and manufactured-housing RFPs and a strong start to 2027. Bears have legitimate ammunition as well. The Jasper OSB mill was curtailed indefinitely and Maniwaki was idled temporarily, single-family starts are still declining, and mortgage rates are pressuring builders. The distribution changeover adds two to three quarters of inventory load-in noise.
Investor sentiment became meaningfully more positive heading into the report, rising from 0.05 to 0.33. The stock, however, has gone nowhere on net. At $75.58, it was up just 0.8% from the open after the August report and sat 0.5% above its 200-day average. That flat result masks a round trip: shares slid to a 52-week low of $62.18 on October 1, then rallied 21.6% to sit 4.9% below the quarter's high. AVWAP readings are positive while other trend signals are neutral, consistent with a stock that has repaired damage rather than broken out.
The bottom line is that Louisiana-Pacific proved SmartSide demand has turned, beating estimates and posting its first siding volume growth of the year. Even so, flat EBITDA, a non-recurring OSB inventory benefit and a below-seasonal fourth-quarter guide mean the earnings recovery is still a 2027 story built on pricing, distribution gains and cost relief.
Read our earnings preview for Louisiana-Pacific Corporation: https://www.earningswhispers.com/article/LPX/21495
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-06 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Sep-15 | |
| Sep-08 | |
| Sep-03 | |
| Sep-01 | |
| Aug-27 | |
| Aug-05 |
