Leidos Must Prove Defense Momentum Can Outrun A Shrinking Health Margin
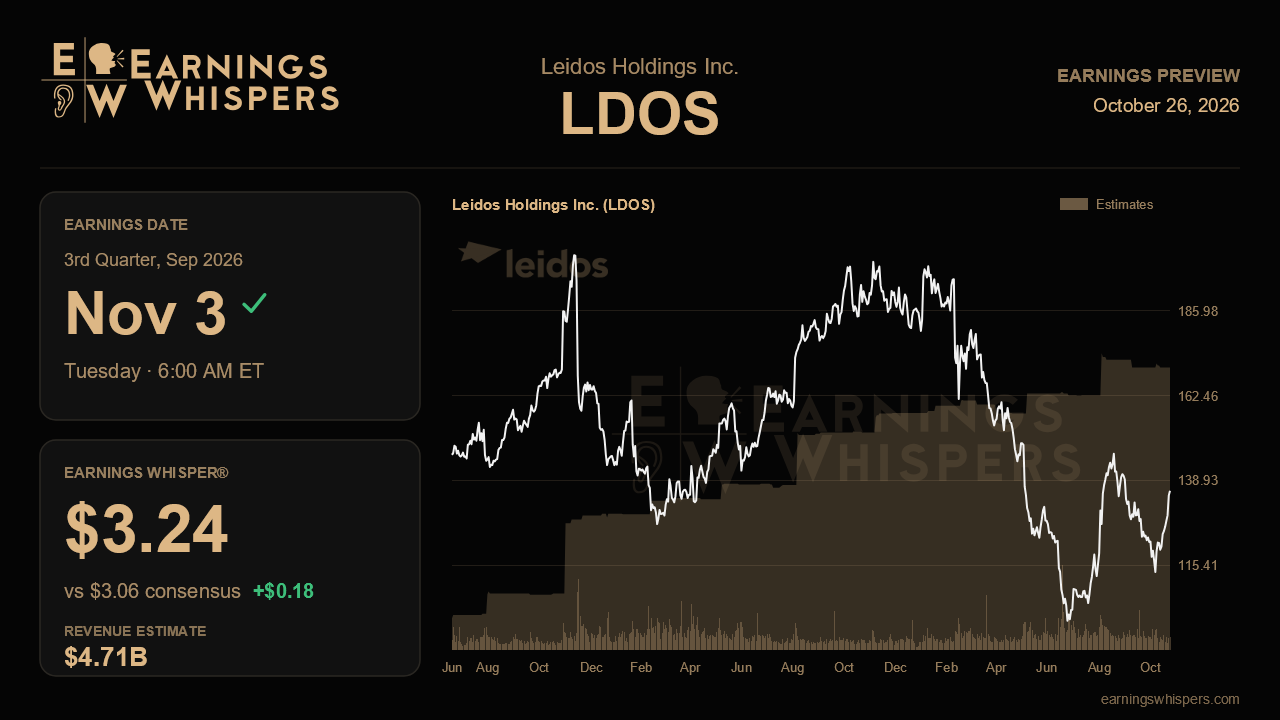
Leidos heads into its third-quarter report with a split personality. Its defense technology business is finally accelerating, bookings are piling up and cash is pouring in. Meanwhile, its once-lucrative health franchise is being deliberately marked down. The question for November 3 is whether the defense upswing is strong enough to keep earnings growing while the health business resets. On the Street's math, that is not yet happening.
Analysts expect earnings of $3.06 a share on revenue of $4.71 billion. That implies sales growth of about 5.4% from a year ago but earnings growth of just 0.3%, essentially flat against the $3.05 earned in the same quarter last year. The gap is no accident. The year-ago period included a record health operating margin of 25.7%, and management has said health margins will run near 20% for the rest of this year. That comparison is a built-in drag. The Earnings Whisper figure of $3.24 sits roughly 6% above consensus, a meaningful premium. It suggests the more engaged crowd expects something closer to last quarter's $3.26 than to the flat result the published estimates imply.
Guidance offers a useful frame. Management narrowed its 2026 outlook to $12.20 to $12.50 a share on revenue of $18.2 billion to $18.4 billion, lifting the low end of both. That followed a sizable revenue raise the prior quarter. It was the company's fourth consecutive increase. Consensus sits at $12.30 a share, a touch below the guidance midpoint. The full-year revenue estimate of $18.12 billion sits below the bottom of management's range. That leaves the Street looking conservative, which helps explain why a modest beat is widely anticipated. It also raises the bar for what counts as genuinely good news. Another beat is likely needed just to keep pace, and a fifth raise would carry more weight.
The operating evidence that matters most is in defense. Last quarter, organic defense growth jumped to 6% from roughly flat, with a 2.2 times book-to-bill. Management said defense, excluding the airborne surveillance business in transition, should grow at a double-digit rate this year. Sustaining that pace would validate the narrative, and so would converting those bookings into revenue. A slip back toward low single digits would challenge it. Progress on newer catalysts also deserves attention. These include the munitions framework agreement worth more than $1 billion and the Navy unmanned surface vessel program, where a production award could come in the fourth quarter. Sensor payloads for Golden Dome satellites and the sovereign AI partnership with CoreWeave add further optionality. Any update on the $12 billion defense pipeline will show whether management's newly aggressive posture is translating into awards.
On the risk side, health is the swing factor. The VA suspended exam incentive payments for all vendors through the rest of its fiscal year, and the Regions recompete still lacks a draft solicitation. If health margins land near the guided 20%, that headwind is contained. If they fall further, the diversification story weakens. The insourcing pressure on the military health records work and possible budget disruption at year-end are also worth monitoring, particularly for Intel and Digital. Cash flow should stay strong after last quarter's record $761 million in free cash flow. Lower capital spending helps, though it also hints at slower investment in defense capabilities.
The market has already leaned in. Shares have gained about 8.9% since the last report while the S&P 500 was flat. Sentiment, though still net bearish, has softened from the prior quarter. Yet the stock, at about $136, remains below its 200-day average near $143 and well short of its post-earnings high of $147.33. Enthusiasm, in other words, remains measured. Ultimately the report hinges on one thing. Defense growth and margins need to show they can carry earnings forward while health resets. If they can, the guidance range looks beatable. If not, flat earnings may start to look like the new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 |
