Leidos Beats On Tax And Buybacks And Raises EPS Guidance, But Stalling Organic Growth And A Flat 2027 Warning Cloud The Outlook
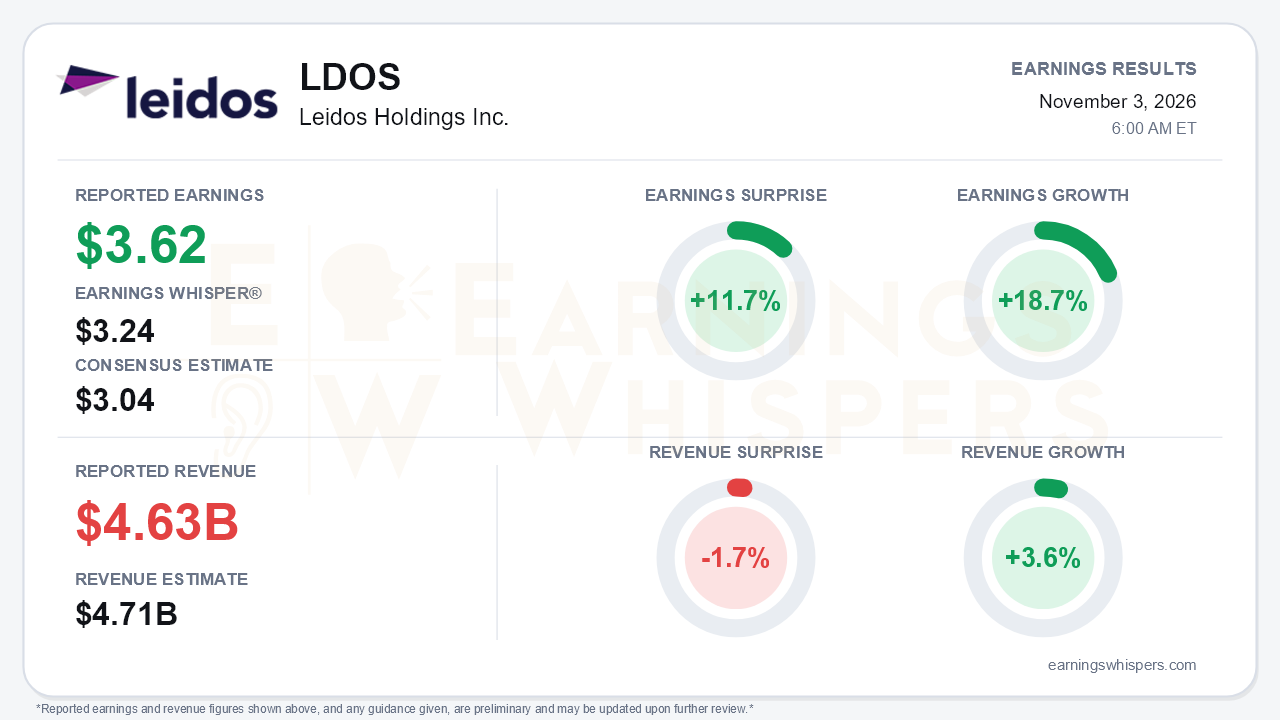
Leidos (NYSE: LDOS) cleared the bar comfortably on earnings and missed on the top line. Non-GAAP EPS of $3.62 topped the $3.04 consensus by 11.7%, beat the $3.24 Earnings Whisper number, and grew 18.7% year over year. Revenue of $4.63 billion rose 3.6% but fell 1.7% short of the $4.71 billion consensus. Management raised full-year EPS guidance for the third straight quarter. The central tension is that the earnings beat came mostly from below the operating line, while organic growth nearly stalled. On the call, the CFO also said for the first time that 2027 will not be a bottom-line growth year.
The beat itself deserves scrutiny. GAAP pretax income was essentially flat at $482 million versus $484 million a year ago. Non-GAAP pretax income rose only about 2%. Two things widened that into 19% EPS growth:
- Income tax expense fell to $69 million from $115 million, helped by a larger federal research credit and lower unrecognized tax benefits. The non-GAAP effective rate was 15.1%, which management does not expect to repeat at that level.
- Diluted shares fell to 125 million from 130 million after $504 million of third-quarter repurchases.
On the operating side, adjusted EBITDA margin edged up to 13.9% from 13.8%, aided partly by favorable contract estimate adjustments. Net interest expense climbed to $67 million from $51 million after debt rose to $6.0 billion to fund the ENTRUST deal. Free cash flow of $476 million was solid, with year-to-date free cash flow of $1.5 billion already above the original full-year target. It was still down from $680 million in the year-ago quarter.
Beneath the headline, the portfolio is diverging sharply:
- **Health:** revenue fell 12% and operating margin compressed to 22.5% from 26.8% as managed health volumes stepped down.
- **Homeland:** revenue jumped 32%, including $142 million from ENTRUST and roughly 15% organic growth. Non-GAAP margin expanded to 11.3% from 7.5% on a richer commercial mix.
- **Intelligence & Digital:** posted record margins, but revenue grew just 1% as federal civilian IT cuts offset Intelligence Community gains.
- **Defense:** growth slowed to 3% from 6% organic in the second quarter.
Consolidated organic growth decelerated to roughly 1%, from 4% in Q2 and 3% in Q1. Excluding Health, revenue rose 9% and operating income 48%. That is the bull case in one line, but Health is too large to ignore.
Demand indicators were the strongest part of the report:
- Book-to-bill improved for a second straight quarter, to 1.2x from 1.1x in Q2 and 0.8x in Q1.
- Defense book-to-bill reached 1.9x.
- Funded backlog of $11.1 billion was up 22% year over year.
- The defense tech 12-month pipeline expanded to more than $14 billion from $12 billion cited on the prior call.
Wins spanned SDA missile-tracking payloads, Havoc Spear low-rate production, SLCM-N, and a first prime cyber operations award with CYBERCOM. Management is targeting munitions as a $1 billion annual business by 2030.
The forward picture is mixed:
- **EPS guidance** rose to $12.50-$12.70 from $12.20-$12.50.
- **Operating cash flow guidance** rose to about $1.90 billion.
- **Revenue guidance** fell to $18.0-$18.2 billion. That cut is largely a portfolio effect of deconsolidating the security and automation businesses into the Altaris joint venture, in which Leidos keeps a 41.5% stake. It is not an operational miss.
- **Fourth-quarter revenue** is expected to be roughly flat with Q3, reflecting cost-plus pressure and a full quarter of VBA changes.
- **Health margins** are guided to the high teens, down from about 20% cited last quarter.
- **Execution setbacks:** management acknowledged some award delays and losses, including the MUSV non-selection after the Q2 call had flagged a potential production award.
- **VBA recompete:** the draft RFP structure looks favorable, but the outcome won't be clear until roughly April-May 2027.
- **Budget assumption:** guidance assumes a continuing resolution through year end.
Bears have legitimate ammunition here: a flat 2027 bottom line follows a 2026 flattered by tax and buybacks.
The market had already priced in much of the good news. Shares closed at $144.16 the day before the report. That was 15.4% above the opening price after the August release and about 2% above the 200-day moving average. The stock also sat within about 2% of its inter-earnings high of $147.33 after a nearly 29% rebound from an early-October low. Investor sentiment remained negative but improved, moving from -0.58 to -0.44. Holders were less skeptical, not enthusiastic. Momentum and AVWAP trend readings are positive, consistent with the recent recovery. Still, a stock entering earnings near the top of its range leaves less cushion for a guide that pairs higher EPS with flat near-term revenue.
The bottom line is that Leidos delivered a high-quality demand quarter wrapped in a lower-quality earnings beat. Rising bookings, funded backlog and defense pipeline support a credible longer-term growth story. Near-term profit growth, however, is leaning on taxes, buybacks and Homeland strength while Health resets and organic growth slows to a crawl. Until the VBA recompete is resolved next spring, the debate is whether defense and Homeland momentum can fill a 2027 earnings plateau that management has now openly acknowledged.
Read our earnings preview for Leidos Holdings Inc.: https://www.earningswhispers.com/article/LDOS/21493
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 8 hours | |
| 8 hours | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 |
