Ferrari's Third Quarter Tests Whether Personalization Can Offset A Planned Cost Step-Up
Ferrari heads into its third-quarter report with a better story than its stock price suggests. Last quarter management raised its full-year targets, launched its first electric car on schedule and sold out a manual-transmission special series before most buyers could blink. Yet the shares have barely moved since, and the quarter now arriving is the one management itself flagged as carrying heavier costs. The question is whether the momentum built in the spring survives the expense bill of the autumn.
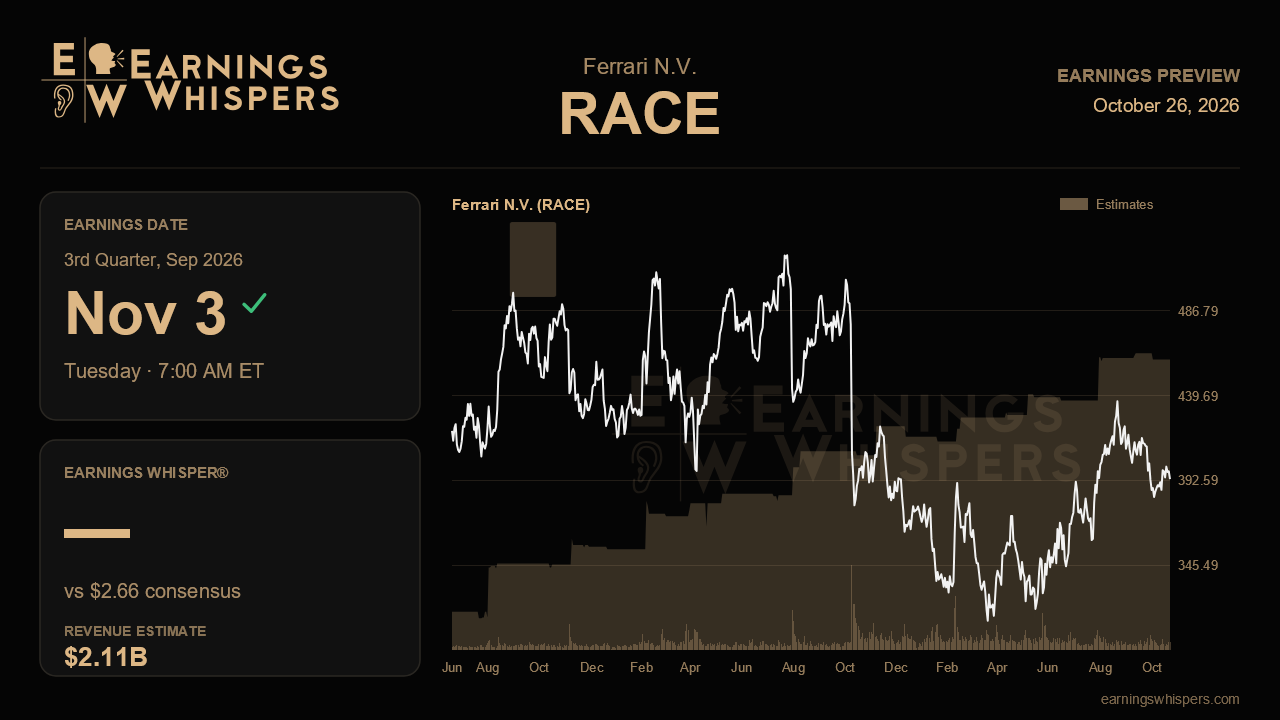
Wall Street is looking for earnings of $2.66 per share on revenue of about $2.11 billion when Ferrari reports before the open on November 3. That works out to EPS growth of roughly 6% and revenue growth of only about 2% from a year ago, a notably quieter pace than the $3.05 and $2.25 billion posted last quarter. Some sequential cooling is normal for a summer period that includes holiday production downtime, but the gap between modest top-line growth and faster profit growth tells you where the Street is placing its bet: on richer pricing and mix, not volume. For the full year, Ferrari now guides to earnings of about $11.10 per share on revenue near $8.72 billion, up from earlier targets of $10.84 and $8.60 billion. Consensus sits squarely on the revenue guide and slightly above the earnings guide at $11.19, which implies analysts expect Ferrari to keep doing what it usually does, which is clearing its own bar with a little room to spare.
The spring raise rested on two pillars, and both deserve scrutiny. The first is personalization, the high-margin bespoke content that ran above 20% of car and spare parts revenue last quarter, ahead of the glide path management had sketched toward 19%. Another quarter at or above that level would confirm that wealthy buyers are still spending freely on options, not just on base cars. A slip back toward 19% would suggest the second quarter was a high-water mark. The second pillar is currency. Management swapped a feared headwind for a modest tailwind by assuming a dollar-euro rate near 1.16. Because the profit raise was only about half as large as the revenue raise in euro terms, the company was candid that FX gains are partly eaten by hedging and costs, so a strong revenue print should not automatically be read as an equally strong margin print.
The cost side is where the quarter could disappoint. Management signaled higher SG&A, R&D and depreciation in the second half, with depreciation and amortization running above €700 million a year, plus Formula 1 expenses booked on the assumption of a first-place finish. Margins that hold close to last quarter's 31% EBIT level despite those charges would validate the bullish read. A sharper compression would invite questions about 2027, when Ferrari is largely unhedged on currency. Investors should also look for evidence that the year-over-year decline in Americas shipments was truly a model-changeover effect, as management argued, and for early commentary on Ferrari Luce orders and the two additional unveilings promised before year-end. Neither the EV nor the 12 Cilindri Manuale sits in the order book yet, so any update on how far the backlog now reaches beyond the end of 2027 would be meaningful.
The mood has soured even as fundamentals improved. Sentiment has slipped to mildly bearish from mildly bullish before the last report, and the stock is up less than 1% since then, trailing the S&P 500 by more than two points. At about $393, the shares sit above their 200-day average of roughly $368 but near the lower end of a post-earnings range stretching from about $381 to $437, after failing to hold the summer rally. That leaves expectations more subdued than the guidance raise would justify.
Ultimately, this report hinges on whether personalization and pricing can absorb the planned cost step-up without denting margins. If they can, Ferrari's improving narrative stays intact and the skepticism priced into the shares looks overdone. If costs win the quarter, the market's lukewarm reaction to the spring raise will look prescient.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 12 hours | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-25 |
