After A 39% Rally, Revvity Must Turn Its Record Instrument Backlog Into Third-Quarter Shipments
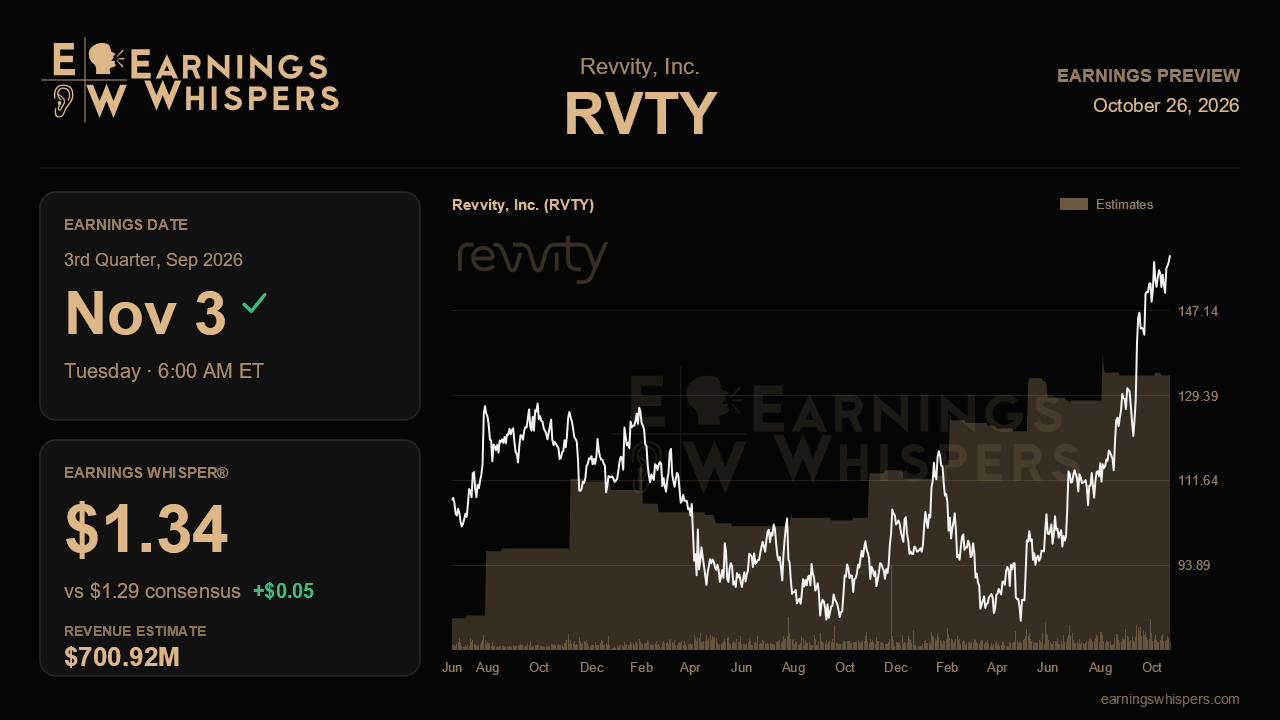
Revvity heads into its third-quarter report with a stock that has already priced in a good deal of the story it told last time. Since management raised its full-year targets for organic growth, operating margin and earnings in the same quarter for the first time this cycle, shares have climbed nearly 39% while the S&P 500 went nowhere. The report on November 3, before the opening bell, is less about whether the company can clear a modest bar. It is about whether the instrument backlog and AI-linked demand that powered that rerating start showing up as revenue.
The Street is looking for earnings of $1.29 a share on revenue of about $700.9 million. That implies roughly 9% earnings growth against a nearly flat top line, since revenue would be up only 0.3% from last year's $698.9 million. The Earnings Whisper sits a bit higher at $1.34, a sign that the market quietly expects another beat. The guidance comparison is also notable. Management now projects full-year earnings of $5.30 to $5.40 on revenue of $2.83 billion to $2.86 billion, yet consensus earnings of $5.25 sit below the bottom of that range, while the revenue estimate of $2.84 billion lands comfortably inside it. Analysts seem to have discounted part of the second-quarter upside, and with good reason. About half of that $1.41 beat came from roughly $16 million of one-time tariff refunds, and about a third came from tax timing that management said reverses in the fourth quarter. A cleaner third quarter will show how much of the earnings power is truly recurring.
The most important operating test is instruments. Management lifted its platform growth outlook to mid-single digits on what it called the strongest backlog in three to four years, led by double-digit order growth for the Opera Phoenix OptIQ high-content screening system and, notably, by orders from AI and other nontraditional drug-discovery customers. It also said production and shipment timing held back second-quarter instrument revenue and pushed that upside into the third quarter. That makes this report the natural place to collect. Visible instrument acceleration, along with evidence that OptIQ capacity is catching up with demand, would validate the narrative. Another quarter of timing explanations would raise questions about whether capacity is the real constraint.
Software is the second swing factor. Signals revenue fell about 20% organically last quarter on tough comparisons and contract timing, though recurring value still grew at a double-digit pace. Management expects a return to strong double-digit growth in the second half, and the third quarter should show at least the start of that turn. Diagnostics, which accelerated to 11% organic growth on mid-teens reproductive health and high-single-digit immunodiagnostics outside China, needs only to stay near that pace to remain the steady anchor. The underlying pharma and biotech business outside software grew only in the low single digits, so any sign of broader recovery there would be welcome upside. The gap between a 4% to 5% organic target and flat reported revenue also deserves a clear bridge, and the pending China immunodiagnostics divestiture is the obvious item to watch.
Sentiment has moved from roughly 20% bearish before the last report to essentially neutral, and the stock trades near $158.77, well above its 200-day average of about $110 and within 2% of its post-earnings high of $161.64. That puts shares at the edge of a breakout, but it also means the easy skepticism has been squeezed out.
In the end, the quarter comes down to conversion. If Revvity shows that last quarter's backlog and AI orders are becoming shipped instruments and that software is turning higher, the raised outlook looks conservative and the rally has support. If timing slips again, a stock priced for an inflection may have to settle for a recovery.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Oct-02 | |
| Sep-24 | |
| Sep-24 | |
| Sep-15 | |
| Sep-09 | |
| Aug-11 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-31 |
