Strata Critical Medical Needs Clinical Growth And Bolt-Ons To Offset A Soft Logistics Quarter
Strata Critical Medical heads into its third-quarter report with a business that is pulling in two directions. Its clinical services arm, boosted by three freshly closed acquisitions, has been gaining momentum, while its larger organ logistics operation is absorbing a lost chunk of customer flying and a seasonal lull. The stock has been marked down sharply since the last report even though management raised its full-year outlook. That makes this release a direct test of whether the clinical engine is strong enough to carry the company through a deliberately weak logistics quarter.
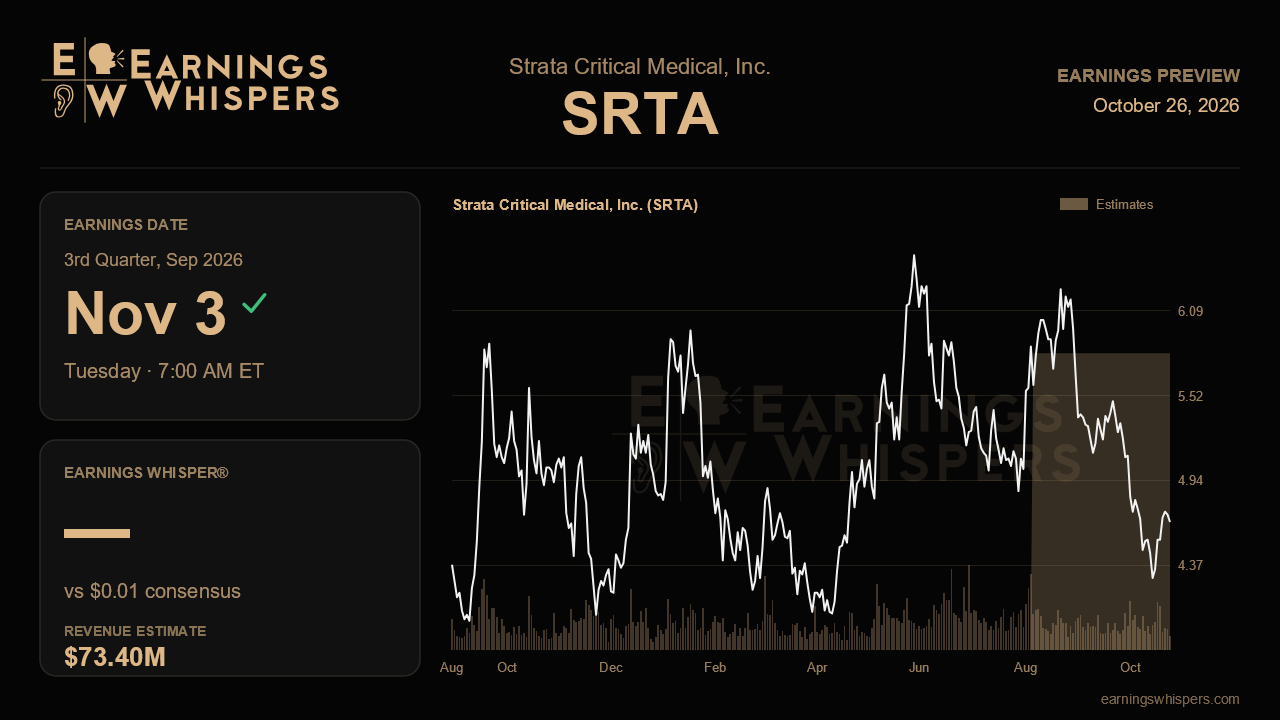
Wall Street expects earnings of about a penny a share on revenue of roughly $73.4 million, before the market opens on November 3. Against the year-ago quarter's loss of six cents and $49.3 million in sales, that implies revenue growth near 49% and a swing to modest profitability. The sequential picture is far less dramatic. Consensus sits only slightly above the $72.5 million reported last quarter, which tells you analysts have taken management's logistics warning seriously. Annual guidance calls for $285 million to $295 million in revenue and $33 million to $35 million in adjusted EBITDA. That outlook was raised last quarter from $260 million to $275 million, the latest step in a steady climb that began at $255 million to $270 million. A quarter near $73 million keeps the company on a reasonable path toward that range, but it leaves the fourth quarter to do meaningful lifting.
The swing factors come straight from the last call. Management guided logistics revenue down by a high-single-digit percentage sequentially. The reasons were a non-exclusive customer sharply cutting flights for one organ type, representing about 3% of logistics revenue, plus summer seasonality and fewer organs accepted at several transplant centers in July. Logistics gross margin slipped to 18.4% in the second quarter on fuel pass-through, short-trip mix, unscheduled aircraft maintenance and weaker ground margins, and the second-half target was trimmed to 18.5% to 20%. A print inside that band, with maintenance costs easing, would support management's view that the pressure is temporary. A reading below 18.5% would suggest the problems run deeper than one customer.
On the clinical side, the bar is higher. Organic clinical revenue jumped 15.1% sequentially last quarter, transplant clinical rose nearly 24%, and segment gross margin reached 26.1%. The Louisville Perfusion, Ohio Valley and Heart and Lung Transplant National Recovery deals were billed as adding more than $20 million in revenue and $6.3 million in annualized EBITDA. Clinical is expected to represent about 40% of second-half revenue. A first full quarter of contribution should show up clearly in segment revenue and margin. Continued gains in normothermic regional perfusion adoption, which reached about 59% of DCD donors, along with early traction from the Statline placement takeover, would reinforce the growth story. Integration hiccups or margin dilution from the new businesses would undercut it.
Sentiment has warmed noticeably, moving to mildly bullish from clearly bearish heading into the prior report. The share price tells a colder story. The stock has fallen about 13.7% since the last release while the S&P 500 was flat. At $4.66 it trades below its 200-day moving average of $5.13 and sits nearer the $4.21 low of its post-earnings range than the $6.33 high. The market appears to be discounting the logistics softness and the cash costs of rapid dealmaking more heavily than the raised guidance.
The central question is whether consolidated adjusted EBITDA margin can hold near last quarter's 10.9% despite the logistics dip. If clinical growth and acquisition contributions keep margins intact, and management reaffirms its annual targets alongside the $17.5 million Joby earn-out, the improving narrative survives. If logistics erodes further and drags margins down, the stock's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-21 | |
| Jun-24 | |
| Jun-02 | |
| May-07 | |
| May-06 | |
| Apr-30 | |
| Apr-20 | |
| Apr-13 |
