Strata Critical Medical Misses On EPS But Posts Record Cash Flow As Logistics Demand Softens
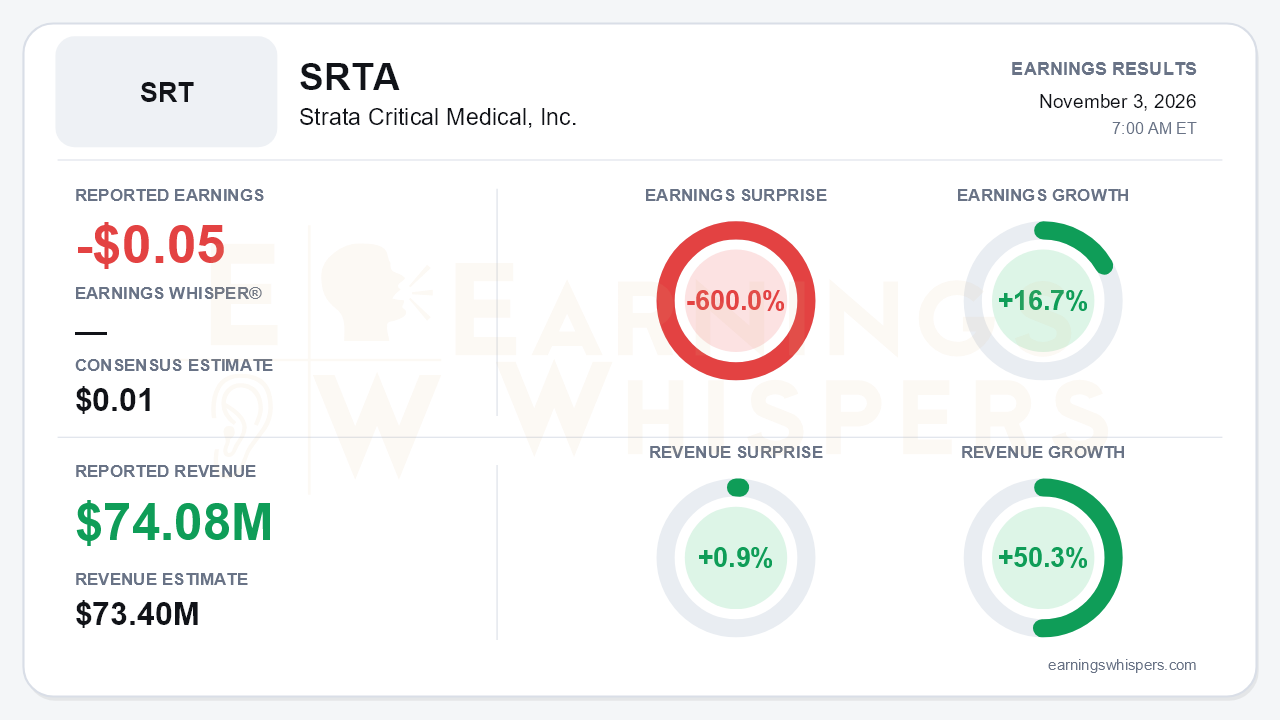
Strata Critical Medical's third quarter looks like a miss in the Earnings Whispers numbers but reads better operationally. The company reported a loss of $0.05 per share, compared with consensus for a $0.01 profit, a -600.0% surprise. Revenue of $74.08 million beat the $73.4 million consensus by 0.9% and grew 50.3% year over year. The loss still improved 16.7% from a year ago. On a GAAP basis, the loss from continuing operations was $0.09 per share versus $0.12, or $7.6 million versus $9.7 million. Beneath that loss, adjusted EBITDA more than doubled, free cash flow set a record, and management announced its first buyback. The central tension is whether margin and cash-flow gains can outrun softening transplant logistics, the company's largest segment.
The quality of the quarter is mixed. Headline growth is mostly acquired. Clinical revenue rose to $29.2 million from $2.8 million, driven by the Keystone deal and three Q2 acquisitions. On a pro forma basis, which management notes is not an organic measure, revenue grew just 8.5%. Logistics revenue fell 3.5% year over year and 6.9% sequentially to $44.9 million. The GAAP loss reflects large non-cash items:
- $5.5 million of intangible amortization, up from $0.4 million
- $5.0 million of stock-based compensation
- a $2.6 million fair-value charge
- a $1.3 million realized loss on Joby shares received from the Passenger divestiture
On the company's adjusted measures, results were clearly better:
- Adjusted EBITDA reached $9.6 million at a 13.0% margin, up from $7.9 million (10.9%) in Q2 and $6.4 million (9.5%) in Q1.
- Free cash flow hit $8.6 million, versus $2.9 million in Q2.
- Adjusted SG&A fell sequentially to $8.9 million despite three Q2 acquisitions; the call noted it has been roughly flat for four quarters.
The margin story is the quarter's strongest element. Logistics gross margin rebounded 240 basis points sequentially to 20.8%, above the 18.5-20% second-half guide. That puts it back over the 20% target that the call described as a 2027 goal, earlier than management expected. Clinical revenue grew 20.3% sequentially, and the call cited like-for-like year-over-year growth above 30% and share gains in a seasonally weak quarter. Clinical gross margin, however, slipped to 25.6% from 26.1% on staffing and training investments. That falls short of the 27-28% second-half level management had previously expected, so the improvement is concentrated in Logistics recovery and overhead leverage rather than broad-based.
The forward picture is where bears have legitimate ammunition. A tweak to OPTN lung allocation cut lung trip distances about 20% year over year, and industry trip distances fell roughly 10%. Shorter trips pressure owned-aircraft economics. October industry transplant volumes were down low single digits, with no typical seasonal uptick yet. Management now guides Q4 Logistics flat, after previously expecting a recovery toward Q2 levels. The lost non-exclusive customer continues to weigh. The final OPO rule and potential decertifications are a further watch item, though the call put Tier 3 exposure near 3%.
The release reiterated 2026 guidance:
- revenue of $285-295 million
- adjusted EBITDA of $33-35 million
- free cash flow before aircraft of $15-22 million
Earnings Whispers characterizes the outlook as raised and in line with estimates. The company itself described it as reiterated, and after raises in prior quarters, this time there was no increase.
The offsets are capital-driven. The first $15.3 million Passenger earn-out arrived, with up to $27.5 million more possible by Q1 2027. Management said it can accelerate M&A at mid-single-digit cash-flow multiples and has acquired more than $6 million of annualized EBITDA in 2026. It also reiterated 2027 targets for high-teens organic and 30%-plus total EBITDA growth. A new cardiothoracic locum tenens line and the $20 million buyback add optionality. Cash and short-term investments did decline to $41.6 million from $58.8 million at the end of Q1 after acquisitions.
The market had been treating the stock harshly heading into the print. Shares closed at $4.28 the day before the report, down 20.7% since the open following the August report. That left them 16% below the 200-day moving average and about 32% below the August 27 high of $6.33. The stock sat just 1.7% above its October low of $4.21. Investor sentiment improved meaningfully, rising from -0.21 to -0.02, which is close to neutral but not yet positive. The trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Strata delivered a quarter whose cash generation and margin trajectory are better than the EPS miss implies, and the buyback signals management's confidence. A stock near its lows with improving sentiment, however, still has to contend with flat Q4 Logistics guidance, shrinking trip distances, a clinical margin that missed its second-half target, and an outlook that was held rather than raised.
Read our earnings preview for Strata Critical Medical, Inc.: https://www.earningswhispers.com/article/SRTA/21516
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-21 | |
| Jun-24 | |
| Jun-02 | |
| May-07 | |
| May-06 |
