TransAlta Faces Alberta Price Slump As Colorado Deal And Data-Center Path Near Payoff
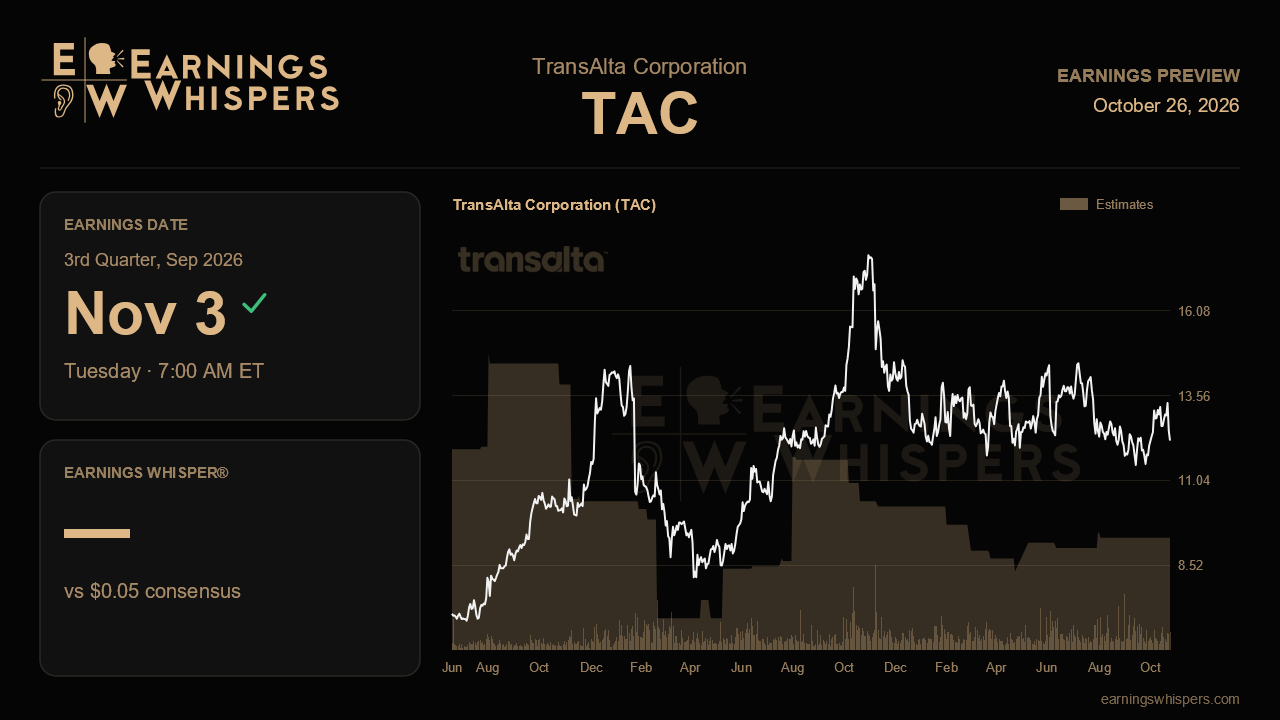
TransAlta heads into its third-quarter report with a split personality. The strategic story has rarely looked more concrete, with a US$1 billion contracted acquisition in Colorado slated to close this quarter and Alberta finally publishing rules that could put its idle gas-steam fleet to work for data centers. Yet the cash engine that pays the bills today, merchant power sales in Alberta, keeps weakening. When the company reports before the open on November 3, the question is whether the long-dated wins are arriving fast enough to offset a soft spot market and a credit agency that has started to look over management's shoulder.
The Street is looking for earnings of $0.05 a share, which would compare with a loss of a penny a year ago. That works out to a 600% gain on paper, but the math flatters a tiny base, and the figure is well below the $0.13 earned in the second quarter. That step down partly reflects seasonality, but it also reflects pricing. Alberta spot power averaged just $29 per megawatt-hour last quarter, down from $32 in the first quarter and $40 a year earlier, and management acknowledged prices were running below the midpoint of its own assumptions even as it reaffirmed, rather than raised, full-year guidance. Revenue also bears watching: the year-ago quarter brought in $446.6 million, while the most recent quarter produced $351.8 million, a reminder of how much merchant exposure has shrunk the top line.
The most important evidence will come from the businesses that weakened last quarter. Hydro EBITDA fell $39 million year over year in the second quarter on lower Alberta prices and fewer emissions-credit sales, and energy marketing slipped $16 million as volatility dried up, a sharper drag than the first quarter's $4 million decline. If both segments stabilize, the reaffirmed outlook looks safe. If they deteriorate again, the market will begin questioning whether guidance needs a trim before the Colorado contribution arrives. The hedge book offers some cushion for later years, with 2027 coverage expanded to roughly 6,600 gigawatt-hours at $64, and an update showing further additions would ease concern about the merchant tail.
On the growth side, investors should want a clear closing timeline for the Colorado peakers, which carry 27-year tolling contracts with full pass-through of fuel, maintenance and capital costs and roughly $110 million of annual EBITDA. Because the deal was excluded from guidance and is immediately accretive to free cash flow per share, confirmation that it closed or is about to close on schedule would validate last quarter's upbeat tone. Equally useful would be any sign that Alberta's system operator is moving to designate underutilized capacity under the June regulations. Management was candid that it cannot control that timing, so progress here is upside rather than a requirement, but silence would extend a catalyst that has already been years in the making.
The balance sheet is the quiet swing factor. S&P shifted its outlook to negative last quarter, with Centralia still offline ahead of a coal-to-gas conversion decision in early 2027. Commentary on leverage, asset recycling or the Brookfield hydro option will matter as much as the headline number.
The market has not given TransAlta much credit for its improved posture. The stock has fallen 5.1% since the last report, lagging the S&P 500 by more than seven points, and at $12.22 it sits below its 200-day moving average and closer to the bottom of its post-earnings range. Sentiment has also cooled, moving from roughly neutral to modestly bearish. That sets a low bar, but the verdict will rest on one issue: whether Alberta's merchant weakness has bottomed enough for the contracted growth to carry the story, or whether it is still eroding the foundation faster than the new pieces can be laid.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-22 | |
| Oct-05 | |
| Oct-02 | |
| Sep-14 | |
| Aug-14 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-29 | |
| Jun-30 | |
| Jun-15 | |
| Jun-09 | |
| Jun-03 | |
| May-06 |
