TransAlta Beats Easily, But A Slipping Data Centre Timeline And Weak Alberta Power Prices Temper An Execution Quarter
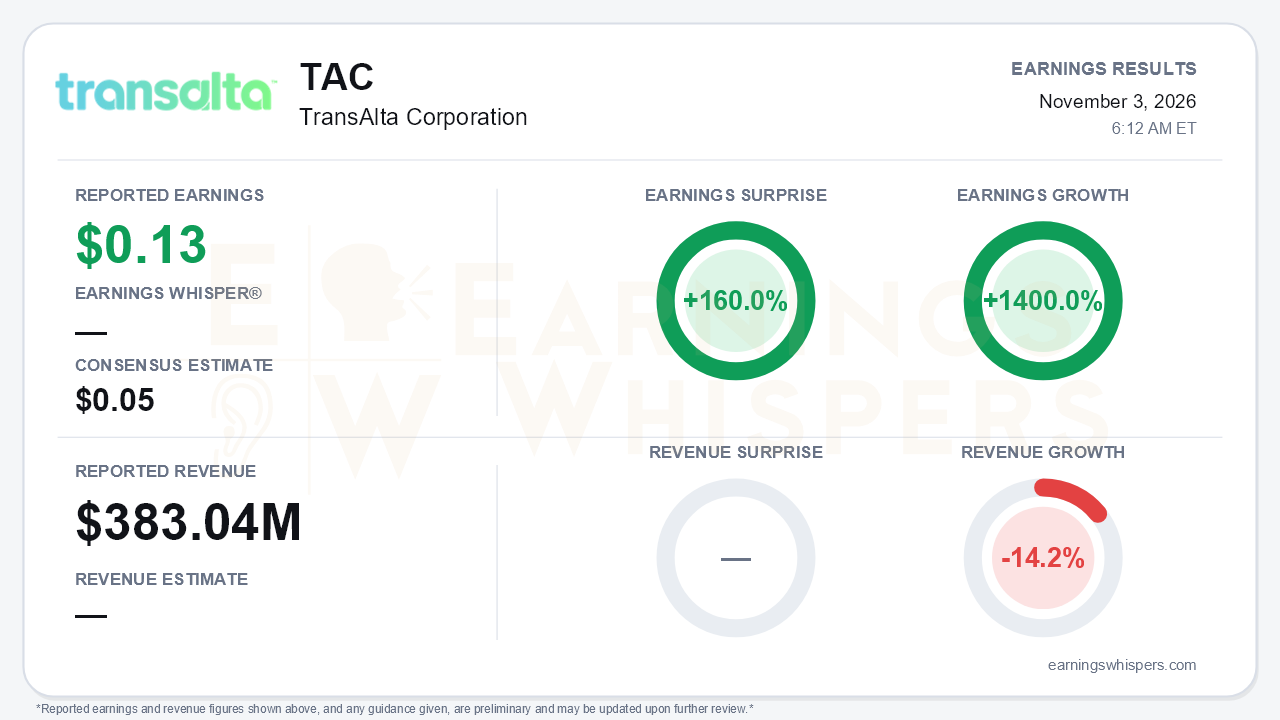
TransAlta delivered a decisive beat on reported earnings. Earnings Whispers puts the result at $0.13 per share against a $0.05 consensus, a 160.0% surprise. Earnings grew 1400.0% year over year even as revenue fell 14.2% to $383.04 million. The company reports in Canadian dollars, and its release shows adjusted net earnings of C$0.18 per share, compared with a C$0.02 loss a year earlier. On an IFRS basis it earned C$0.20 per share after losing C$0.20 per share in the third quarter of 2025. That swing from a loss to a solid profit is the headline. It is not the central story. The quarter showed TransAlta executing well on its portfolio strategy while its biggest catalyst, the Alberta data centre deal, slipped another quarter. Weak Alberta pricing also forced more thermal units into mothball status.
The quality of the beat deserves scrutiny. It came from margin and mix, not volume. Production fell to 5,260 GWh from 6,151 GWh, and revenue dropped to C$536 million from C$615 million. Adjusted EBITDA still rose to C$264 million from C$238 million. Gas segment EBITDA climbed to C$139 million from C$110 million, energy marketing rose to C$30 million from C$17 million, and corporate costs fell about 20%. Management credited hedging and optimization for realized Alberta prices well above spot, along with gains from its environmental credit portfolio. Cash generation tells a less flattering story. Free cash flow slipped to C$93 million, or C$0.29 per share, from C$0.35 a year ago. Funds from operations fell to C$0.46 per share from C$0.53. Some of the per-share erosion reflects roughly 19 million more shares outstanding after the June equity raise. Sequentially, the picture also cooled: adjusted EBITDA fell from C$291 million in the second quarter, and free cash flow dropped from C$143 million.
The call reinforced that TransAlta is managing a weak merchant market rather than benefiting from one. Alberta spot prices averaged about C$36 in the quarter, down from C$51 a year earlier. Realized merchant wind pricing was only about C$19. The company plans to mothball Battle River Units 4 and 5 from March 2027 and extended the Sundance 6 outage into 2029, a clear signal that near-term thermal economics remain poor. Operational trends were better. Availability improved to 92.6% from 90.2% in the second quarter, and ancillary service volumes jumped to roughly 2,800 GWh at an 11% premium, from about 900 GWh. The 2027 hedge book kept building, reaching 6,700 GWh at C$65, up from 6,600 GWh at C$64 last quarter. Management again reaffirmed its 2026 outlook of C$950 million to C$1.1 billion in adjusted EBITDA and C$350 million to C$450 million in free cash flow.
The forward catalysts are real but uneven in timing. Two transactions closed in October:
- The US$1 billion Colorado peaker acquisition, which management says adds roughly C$110 million a year of EBITDA under 27-year contracts.
- The US$305 million sale of a 49% stake in the Oklahoma wind portfolio to Ares.
Together they shift the mix toward contracted cash flow and begin the asset-recycling program flagged earlier in the year. Other projects also advanced:
- The Boreal Technology Hub at Keephills expanded to up to 1.6 GW of potential load from 1 GW.
- Keephills 1 redevelopment received regulatory approval.
- Centralia permits are expected by year-end, with a final investment decision targeted for 2027.
That is the central tension. Definitive agreements with Brookfield and CPP had been guided for 2026 on each of the prior three calls. Management now says they will "probably" come in early 2027, pending the system operator's decision on underutilized generation. Bears have legitimate ammunition here, along with a fourth U.S. Department of Energy order keeping Centralia Unit 2 available with cost recovery unresolved, and S&P's negative outlook as debt rises with the Colorado deal.
Investors were growing more cautious heading into the print. Earnings Whispers sentiment moved from roughly neutral at -0.02 to -0.14, a meaningful but not extreme deterioration. The stock has gone essentially nowhere, closing at $12.77 before the report, 0.9% below the open after the July release. Shares sat 1.3% below the 200-day moving average and about 6% below the October 21 inter-earnings high of $13.58. They had recovered nearly 12% from the September 28 low. Shorter-term trend readings were mildly constructive, with momentum and AVWAP positive while the price trend was neutral. Even so, the market has clearly been unwilling to pay up for the data centre optionality before contracts are signed.
The bottom line is that TransAlta delivered a clean earnings beat, reaffirmed guidance and closed deals that improve the quality of its cash flow. Its most valuable catalyst, however, moved further out, and its Alberta merchant business continues to shrink in the face of depressed prices. Until the Brookfield and CPP agreements are finalized, the stock is likely to trade more on that timeline and on balance-sheet discipline than on quarterly beats.
Read our earnings preview for TransAlta Corporation: https://www.earningswhispers.com/article/TAC/21520
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-05 | |
| Oct-02 | |
| Sep-14 | |
| Aug-14 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-29 | |
| Jun-30 |
