Sunoco Faces Steep Earnings Bar As Burnaby Refining Windfall Meets Its First Real Test
Last quarter Sunoco did something it had not done all cycle: it raised its full-year outlook, lifting 2026 adjusted EBITDA guidance by $400 million to a range of $3.5 billion to $3.7 billion. The catch is that much of the raise rested on its Burnaby refinery, the most volatile piece of the business. The third-quarter report, due before the open on November 3, will show whether that windfall was a durable step-up or a well-timed spike.
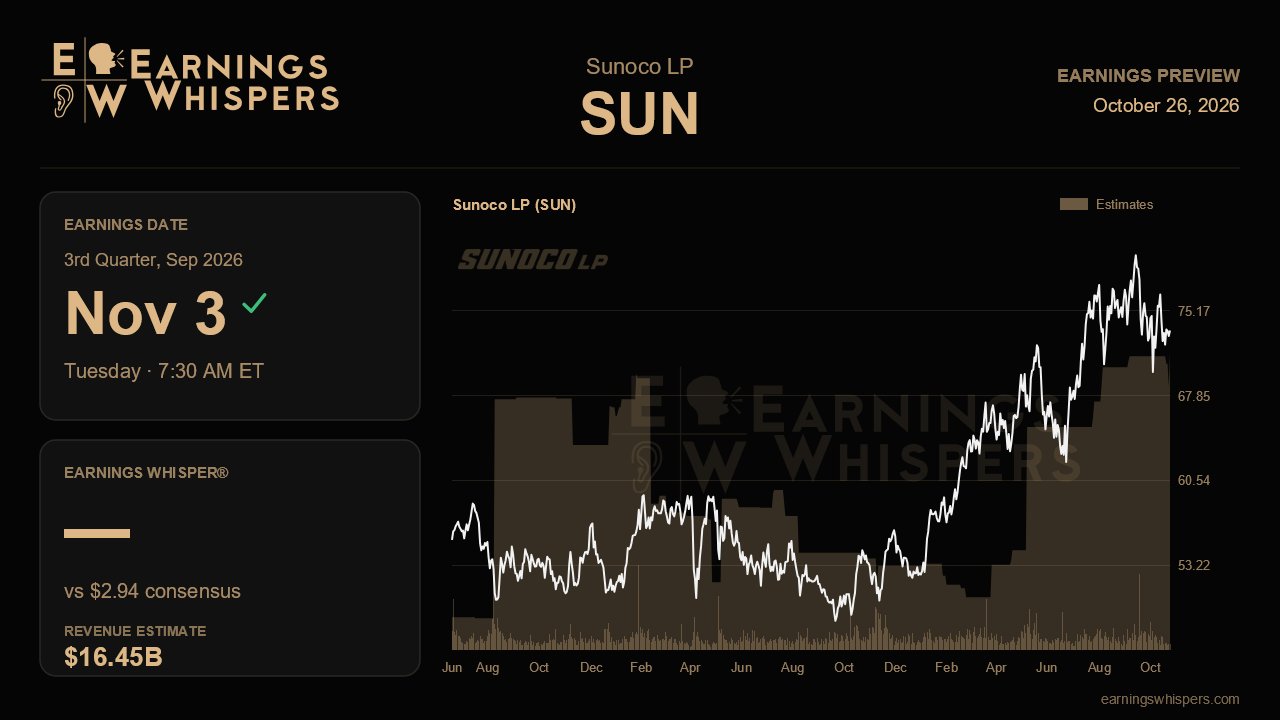
Wall Street is setting a demanding bar. Consensus calls for earnings of $2.94 per unit on revenue of $16.45 billion, which would be roughly 359% earnings growth and 173% revenue growth from a year ago. Much of that year-over-year jump reflects a far larger footprint after the Parkland deal, so the more telling comparison is sequential. Sunoco earned $0.94 on $14.26 billion of revenue last quarter, and the Street now expects roughly three times that profit on only modestly higher sales. That is a big leap. Anyone judging the print should look past the headline number to segment EBITDA and whether management reaffirms or narrows the upper half of its annual range.
Refining is the swing factor. The segment produced $175 million in the second quarter, up from about $43 million in each of the prior two quarters, as Burnaby ran above nameplate at 57,000 barrels a day after its turnaround. It earned margins above $40 a barrel while keeping operating costs under $10. Management was candid that forecasting cracks is not an exact science and that the width of its guidance range comes almost entirely from refining. A third quarter that keeps throughput near nameplate with healthy margins would validate the raise. A sharp margin retreat would make the high end of guidance look stretched, even if the rest of the portfolio performs.
The steadier businesses deserve equal attention, because they are what make the bullish case more than a crack-spread trade. Terminals have climbed for several straight quarters, reaching $115 million with a full quarter of Tankwood, and pipelines rose to $190 million. Fuel distribution held at about 17 cents a gallon, far above the roughly 10.5 cents of a year earlier. Management flagged two soft spots worth checking. Rising flat prices late in the second quarter typically squeeze per-gallon margins, and Canadian gasoline demand had slipped by low single digits. Holding margins in the mid-teens or better, alongside further terminal and pipeline gains, would show the improvement is broad-based. Investors should also look for confirmation that Parkland synergies remain ahead of schedule and that cash taxes ease in the second half, as promised.
Capital allocation is the other thread. Leverage fell to about 3.7 times, below the 4.0 times target, and coverage improved to 2.1 times after another distribution increase. Management upgraded its $500 million annual bolt-on acquisition target from a floor to a modest bar it expects to clear this year. It also signaled interest in larger North American pipeline and terminal assets. Any update on deal activity, and whether leverage stays below target while it happens, will shape how the market values the units.
So far the market has not paid for the upbeat call. The units are down 4.5% since the last report against a flat S&P 500, and sentiment has barely moved, hovering around 24% bullish. At $73.47, the stock sits above its 200-day moving average of $68.06 but in the lower half of its post-earnings range of $69.89 to $80.22, well short of a breakout. That skepticism leaves room for a positive reaction if results hold up. The central question is simple: can Sunoco show that its higher earnings base rests on terminals, pipelines and fuel margins, with Burnaby as a bonus rather than the foundation? A clean answer would keep the raised outlook credible, while a refining-led shortfall would revive doubts about how much of the step-up will last.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 52 min | |
| Oct-01 | |
| Oct-01 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Aug-18 | |
| Aug-11 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
