Sunoco Misses EPS Consensus But Posts Record EBITDA, Signals Beat Of Raised 2026 Guide As Refining Strength Carries Weight
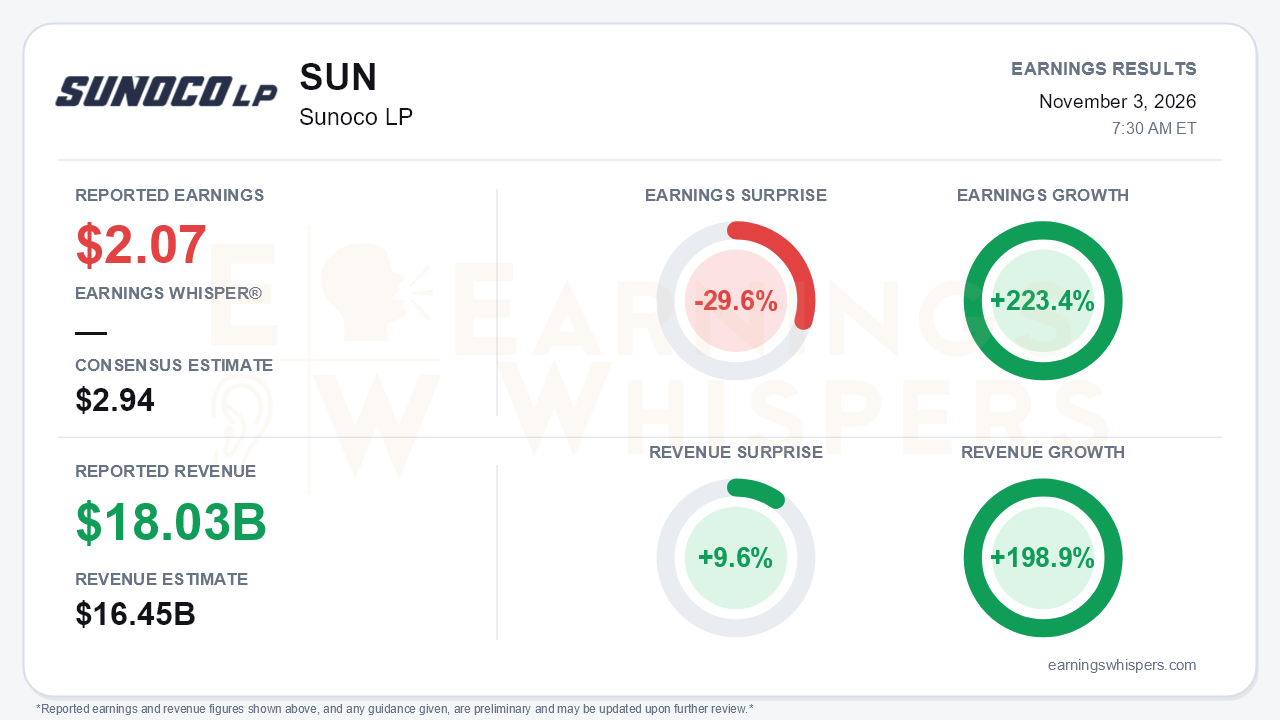
Sunoco LP's third-quarter headline and its underlying operating story point in opposite directions. Diluted earnings of $2.07 per unit fell 29.6% short of the $2.94 consensus. That is a sizable miss even as earnings grew 223.4% year over year. Revenue of $18.029 billion beat expectations by 9.6% and grew 198.9%. Yet adjusted EBITDA, excluding transaction costs, reached a record $1.06 billion. Management now expects full-year adjusted EBITDA to exceed the top of its $3.5-$3.7 billion range, a range that was already raised by $400 million last quarter. That is the central tension: a per-unit earnings miss alongside a cash-flow picture that keeps beating management's own targets.
The quality of the miss deserves scrutiny. GAAP net income rose to $499 million from $137 million, but a growing share of it no longer reaches common unitholders. Allocations to the Class D unitholder ($108 million) and preferred holders ($29 million) absorbed $137 million, leaving $362 million for common units. Income tax expense jumped to $106 million from $11 million as the Parkland-expanded footprint carried a heavier tax load. Those structural layers, created by the Parkland transaction, compress per-unit GAAP earnings in ways the EBITDA line does not show. The year-over-year comparisons are also overwhelmingly acquisition-driven. Fuel volumes nearly doubled to 4.2 billion gallons, and the Refinery segment, which did not exist a year ago, contributed $238 million.
The sequential trend tells a more useful story, and it is constructive but decelerating. Adjusted EBITDA climbed from $867 million in Q1 to $996 million in Q2 and $1.06 billion in Q3. The rate of improvement narrowed considerably this quarter. Refining did the heavy lifting, rising to $238 million from $175 million as realized margins topped $54 per barrel versus more than $40 in Q2. Fuel distribution EBITDA edged up to $532 million from $516 million, and Terminals improved to $124 million from $115 million. The softer spots were real, though:
- Pipeline EBITDA slipped to $166 million from $190 million in Q2, on lower joint-venture contributions from ET-S Permian and non-repeating FERC clawbacks.
- Fuel margin eased to 16.8 cents per gallon from 17.1 cents.
- Distributable cash flow, as adjusted, dipped to $588 million from $608 million.
- Demand stayed soft, with Canadian fuel demand down low-to-mid single digits and U.S. gasoline down low single digits.
Bears have legitimate ammunition. A meaningful share of this year's upside rests on refining cracks, which are cyclical. The volume backdrop in fuel distribution is flat to declining, so margin capture and cost cuts must carry growth. Management's response leaned on self-help and deal flow. It guided 2027 fuel distribution operating expenses lower as Parkland integration continues. It also argued that 2026 would have beaten the January guide even at mid-cycle cracks, and it framed 2027 as another record year. The $600 million Offen Petroleum acquisition closed, bringing 2026 bolt-on deals to about $1.5 billion, triple the $500 million floor. Rerouted MidCon product flows could also help the northbound pipeline system. Meanwhile, leverage fell to roughly 3.5x from about 4.0x in Q1, putting the partnership back at target in under a year. The distribution rose 1.25% to $1.0148, the eighth straight increase and more than 10% above a year ago. Formal 2027 guidance is not due until January, so the record-year claim remains a qualitative expectation.
The market had already turned skeptical before the print. Shares opened at $76.93 after the August report and ran to a 52-week high of $80.22 in mid-September. They then slid to $68.69 by the eve of this release, down 10.7% over the period, 14.4% below that peak and just 0.8% above the inter-earnings low set on November 2. The stock now sits essentially on its 200-day moving average, 0.3% above it. Investor sentiment stayed positive but weakened notably, falling from 0.24 to 0.11. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative. That mix fits a stock whose fundamentals keep improving even as its recent price action has been heavy.
The bottom line is that the EPS miss looks more like a product of Sunoco's post-Parkland capital structure and tax profile than a crack in the operating engine. Record EBITDA, an implied guidance beat, faster deleveraging and accelerating M&A argue the growth story remains credible. The open questions are durability and per-unit translation. Refining provided much of the quarter's lift, pipelines and core fuel demand softened, and DCF slipped sequentially. With shares back near their 200-day average and sentiment cooling, January's 2027 outlook becomes the real test of whether management's record-year confidence holds up at mid-cycle margins.
Read our earnings preview for Sunoco LP: https://www.earningswhispers.com/article/SUN/21518
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-01 | |
| Oct-01 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Aug-18 | |
| Aug-11 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 |
