Stevanato's Margin Story Faces A Third-Quarter Test As Balda Exit Mutes Reported Growth
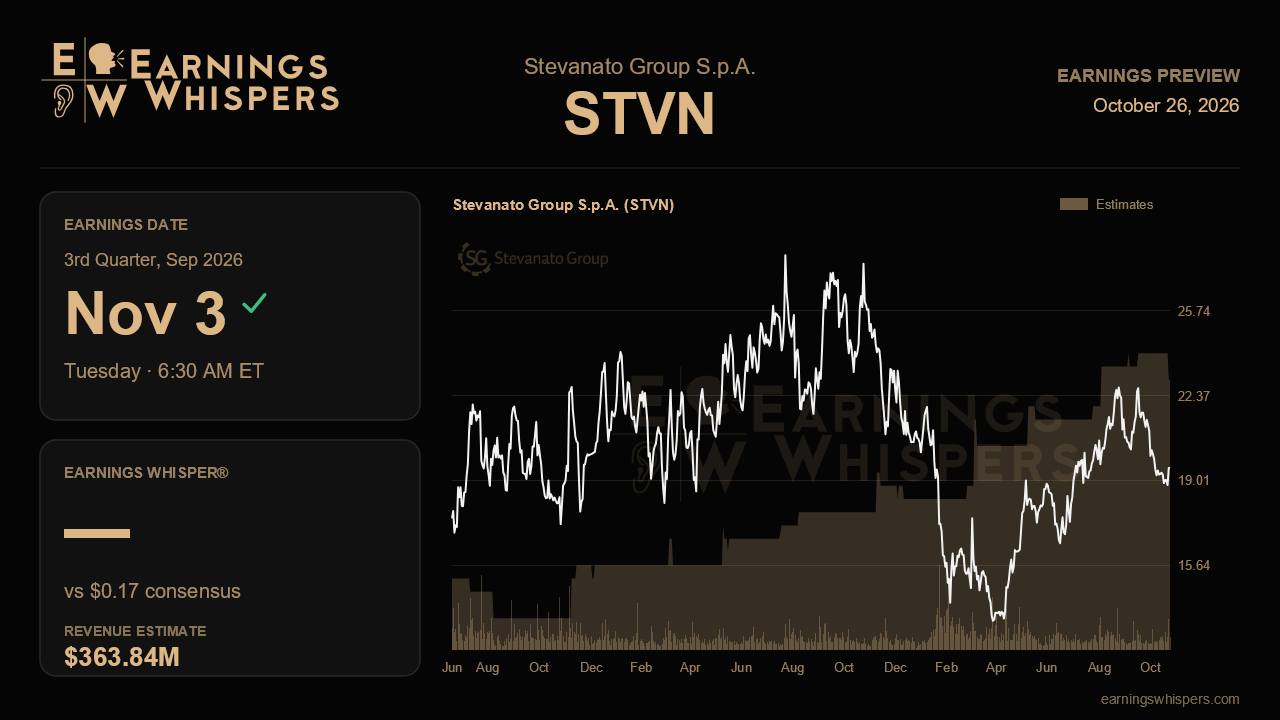
Stevanato Group heads into its third-quarter report with a story that sounds better than its headline numbers will probably look. Last quarter management lifted the midpoint of its full-year adjusted EBITDA outlook, celebrated European approval of its Alina pen, and pointed to a long-struggling engineering unit finally turning profitable. Yet the stock has slipped since then, and the Street is penciling in only low single-digit revenue growth. The question for this report is whether margin expansion and mix improvement can keep doing the heavy lifting while the reported top line stays sluggish.
Consensus calls for earnings of $0.17 a share on revenue of $363.8 million, up 6.3% and 2.7% respectively from the year-ago $0.16 and $354.4 million. That is modest growth, but context matters. The divestiture of Balda C. Brewer, the California contract manufacturer, removes roughly $15 million of annual revenue, which is why management trimmed the top of its full-year revenue range to $1.26 billion to $1.28 billion and cut reported growth expectations for the biopharma and diagnostic solutions segment to high single digits while saying organic growth remains double digit. Adjusted EPS guidance was narrowed to $0.60 to $0.62, with a higher tax rate near 28% absorbing some of the operating improvement. A quarter landing near consensus would keep the company on pace for that range, with the seasonally strong fourth quarter expected to carry the rest.
The more telling number will be the adjusted EBITDA margin. It reached 26% in the second quarter, up 280 basis points from a year earlier and well above the first quarter's 23.9%. The full-year outlook implies roughly 26.8% at the midpoint, so management needs the third quarter to at least hold the mid-20s and improve on the 25.7% posted a year ago. A margin that slides back toward first-quarter levels would raise doubts about the EBITDA raise, while another step up would suggest the shift toward high-value solutions, which hit 45% of revenue last quarter, is structural rather than seasonal. The GLP-1 share of revenue, recently around 22% to 23%, is another useful gauge, though the more important tell for diversification is biologics outside GLP-1, which grew only about 6% last quarter.
Engineering deserves close attention because it has been the persistent drag. Its operating margin flipped to a positive 2.9% in the second quarter, and management sounded cautiously optimistic about new orders, while conceding that sales cycles remain stretched. Evidence of order conversion, not just backlog commentary, would validate the turnaround. On the device side, the Alina pen's commercial launch is mostly a 2027 revenue story, but management flagged North American approval for the second half of this year, so any update on that timeline, along with progress on the RTU-400 cartridge line and early interest in the new DIORA pen, will shape how investors value the longer-term pipeline.
Cash flow is the potential sore spot. Free cash flow swung to negative $32 million last quarter on heavy capital spending tied to Alina and growth plants. Investors will want signs that capex intensity is peaking and that working capital is behaving.
The market has cooled on the stock. Shares are down 3% since the last report, lagging a flat S&P 500, and trading sentiment has faded to barely bullish from a more constructive reading a quarter ago. At $19.49 the stock sits above its 200-day moving average but much closer to the bottom of its post-earnings range than to the $23.25 peak, implying the initial enthusiasm over Alina has largely been given back. That lowers the bar somewhat. Ultimately, this report hinges on whether margins keep expanding while reported revenue absorbs the Balda exit. If they do, last quarter's EBITDA raise looks credible; if they stall, the narrative of a richer, more profitable mix starts to look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-26 | |
| Oct-20 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-21 | |
| Jun-08 | |
| Jun-03 | |
| May-07 | |
| May-07 | |
| May-04 | |
| Apr-23 |
