Stevanato Beats And Widens Margins, But A GLP-1 Customer Cut Pushes 2027 Toward Low-Single-Digit Growth
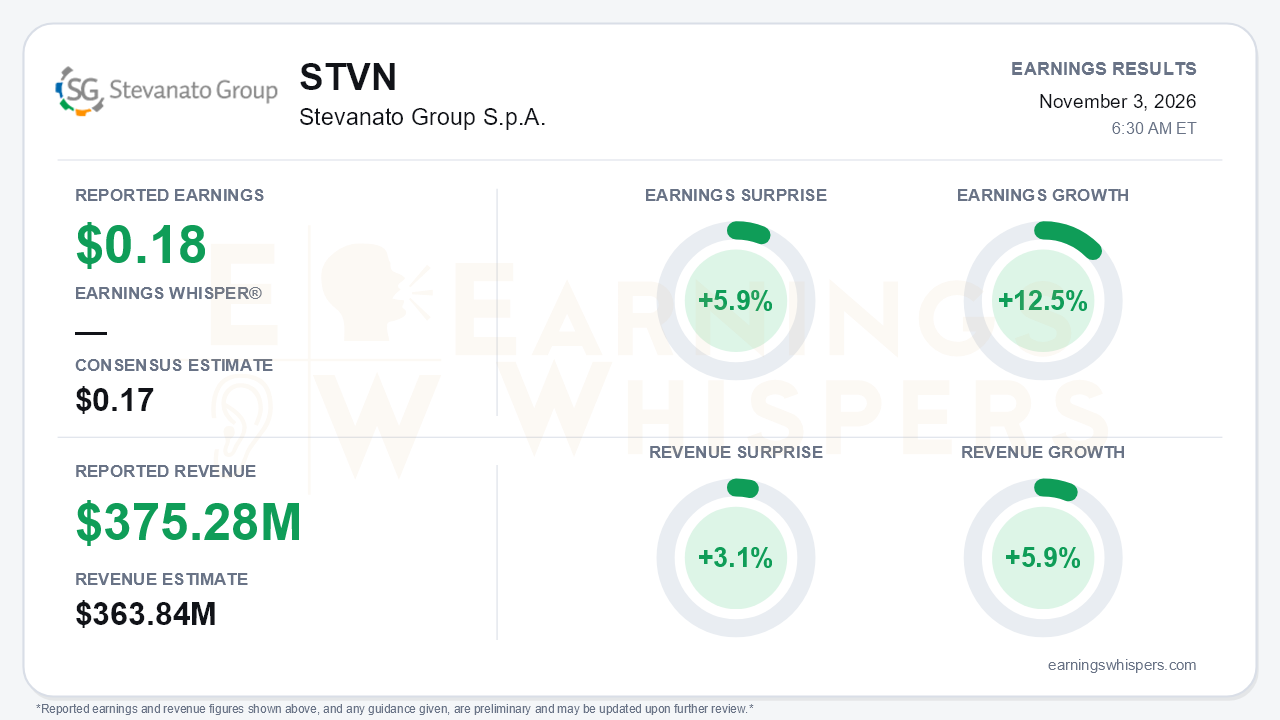
Stevanato Group's third quarter beat expectations, but the more important news was its 2027 outlook. On Earnings Whispers' dollar-normalized basis, the company earned $0.18 per share, beating the $0.17 consensus by 5.9%. Revenue of $375.28 million topped the $363.84 million estimate by 3.1%. Earnings grew 12.5% year over year and revenue rose 5.9%. In its own reporting currency, Stevanato posted revenue of €326.1 million, up 8% both reported and organically. Adjusted diluted EPS was €0.16, up 14%, and IFRS diluted EPS was €0.15, up 15%. The gap between the dollar and euro growth rates reflects currency translation, not a conflict in the underlying results. Full-year 2026 guidance was maintained. The central tension is that management also said one large GLP-1 customer is cutting volumes, which will slow 2027 growth to low single digits, well short of the long-range plan of high-single to low-double-digit growth.
The quality of the beat deserves scrutiny. Profitability was clearly better. Adjusted EBITDA margin expanded 150 basis points to 27.2%, up from 26.0% in Q2 and 23.9% in Q1, and adjusted operating margin reached 19.4%. Free cash flow swung to €21.7 million from roughly -€32 million in Q2. Growth composition was weaker. High-value solutions, the premium franchise, grew just 1% after gains of 16% in Q2 and 17% in Q1, and fell to 46% of revenue. The strength came from other containment and delivery solutions, up 23% organically. Bulk syringes and cartridges drove part of that gain, but so did variable compensation tied to lower GLP-1 volumes. In effect, some revenue reflected payments for the GLP-1 shortfall rather than product demand. Gross margin also slipped 10 basis points to 29.1% as European utility costs and higher depreciation offset gains at the Latina and Fishers plants. Engineering revenue fell 12%.
The call confirmed that GLP-1 exposure is shrinking quickly. GLP-1 therapies fell to roughly 17-18% of revenue from 22-23% in Q2. The same customer cutting syringe volumes is also delaying engineering orders. As a result, management lowered 2026 engineering revenue guidance to €124-134 million and is now assessing strategic options for its visual inspection and assembly business. The offset is real, though. Non-GLP-1 biologics grew more than 30% in the quarter, lifting year-to-date growth to 13% from about 6% at midyear. Management now expects the BDS segment to grow organically by double digits at the midpoint for 2026, up from high single digits previously. Management said it has made meaningful progress backfilling the lost GLP-1 revenue but expects normalization only in 2028.
Operationally, the capacity buildout is starting to pay off:
- Fishers broke even at the gross-profit level and shipped its first commercial EZ-fill vial order.
- The Fishers device cleanroom is complete, with commercial device volumes expected within months.
- The first high-volume Alba syringe line was qualified at Piombino Dese.
- Ready-to-use cartridges are reportedly booked for most of 2027.
The 2026 capex budget was cut to €230-240 million from €270-290 million. That should support free cash flow, but it also suggests the company needs less capacity near term than once planned. Two execution risks remain for the fourth quarter. High-value mix must reach roughly 50% to hit the 47-48% full-year target. Energy costs also continue to rise faster than price increases can pass them through.
Investor sentiment heading into the report became more positive, rising from 0.11 to 0.22 on the -1 to +1 scale. That is a meaningful improvement but still only mildly positive, and it was measured before the 2027 commentary. Shares closed at $19.74 before the release, down 1.8% from the opening price after the August report. The stock sat about 9% above its 200-day moving average but 15% below its September 18 high of $23.25. It was also only 6.6% above the October 16 low of $18.51, meaning much of the late-summer rally had already unwound. The internal trend readings are mixed: sequential growth is positive, while AVWAP remains negative.
The bottom line is that Stevanato delivered a clean beat, steady 8% organic growth and real margin expansion. It also showed encouraging non-GLP-1 demand and progress on its new plants. Bears still have legitimate ammunition. High-value growth nearly stalled, part of the quarter's revenue came from shortfall compensation, and a single-customer GLP-1 cut has reset 2027 to low-single-digit growth. The investment case now depends less on 2026 delivery and more on how quickly biologics, Alba and device programs can fill the GLP-1 gap.
Read our earnings preview for Stevanato Group S.p.A.: https://www.earningswhispers.com/article/STVN/21517
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 9 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-21 | |
| Jun-08 | |
| Jun-03 | |
| May-07 |
