Versant's Sports Cost Air Pocket Arrives As Battered Stock Tests Its Advertising Recovery
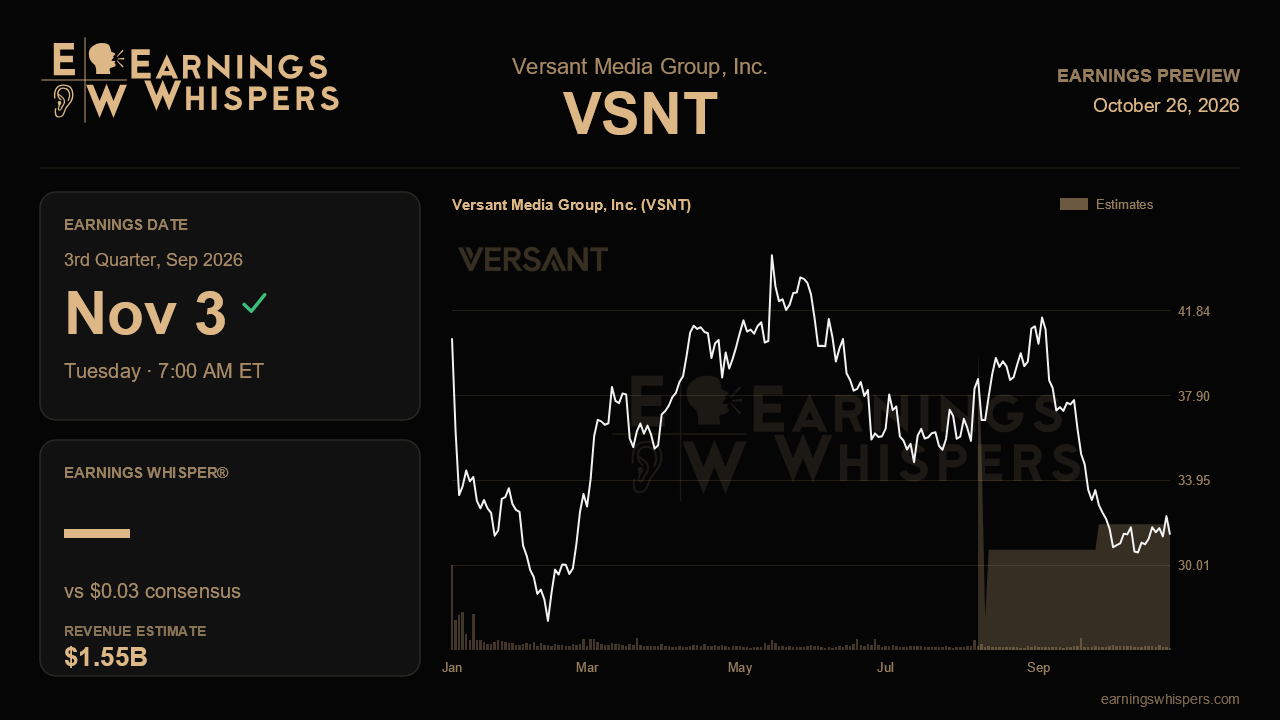
Versant Media Group heads into its third-quarter report with a peculiar setup: management told investors three months ago that the back half would look worse on paper, and the market appears to have sold the stock as if that warning were news. Shares have fallen 21.5% since the company raised its full-year outlook for the first time as an independent company, trailing the S&P 500 by roughly 20 percentage points. The November 3 release, due before the open, is therefore less about whether profits grow and more about whether the operating story underneath the expected cost spike is still intact.
The bar is low on earnings and modest on sales. Analysts expect profit of just $0.03 a share on revenue of about $1.55 billion, a sharp step down from the $1.49 per share and $1.64 billion delivered last quarter. That drop largely reflects what management flagged in advance: heavier programming and sports rights expenses from extra NASCAR races, the first WNBA season and a slate of golf events, along with the return of the Premier League and NASCAR Cup on USA. Executives said third and fourth quarter adjusted EBITDA were unlikely to grow year over year, so a flat-to-lower profit comparison should not by itself rattle anyone. A deeper-than-expected decline, or any hint that the cost ramp is running hotter than planned, would be another matter.
The full-year frame matters more. Versant now guides 2026 revenue to $6.20 billion to $6.45 billion, up from a range it had held through two prior reports, and lifted adjusted EBITDA guidance to $1.9 billion to $2.05 billion. Consensus revenue of $6.39 billion sits in the upper half of that range, meaning the Street is already leaning toward the optimistic end. Reaffirming the outlook would be adequate; trimming it, particularly on EBITDA, would undercut the credibility the company just started building. Free cash flow guidance of $1.0 billion to $1.2 billion was left unchanged last time, with management warning that second-half cash generation would trail the first half on New York facility spending and working capital timing, so any drift toward the bottom of that range deserves attention given the company's capital return ambitions, including a $100 million accelerated buyback slated for this quarter.
The most important validation point is advertising. The decline narrowed from 9% in 2025 to 5% in the first quarter and just 0.6% in the second, helped by broad demand for news and sports. Fresh live sports inventory this quarter gives Versant a real shot at tipping advertising into growth. If that happens, it supports the idea that the rights spending is buying revenue, not just audience. If the trend stalls or reverses, the sports cost surge looks far less defensible. Platforms, which grew 9% excluding a divestiture in each of the first two quarters, is the other pillar; holding that pace would suggest the Fandango AVOD launch, its exclusive Bundesliga matches and the newly acquired Full Swing golf simulation business are adding momentum. Linear distribution, down 6% last quarter on cord-cutting, is the known drag, and investors will want confirmation that the recently completed U.S. and Canadian pay TV renewals keep that erosion orderly.
Sentiment has soured noticeably, with bearish readings roughly doubling from the prior quarter. The stock trades near $31.43, well below its 200-day moving average of $36.42 and only about 6% above its post-report low of $29.75, a range that has shifted lower than last quarter's. That positioning suggests skepticism is already priced in to a meaningful degree.
Ultimately, this report hinges on whether Versant can show that rising sports costs are paying for themselves. Positive or near-positive advertising, steady platforms growth and an intact full-year outlook would affirm the improving narrative and make the selloff look overdone. Weak ad trends paired with a softer guide would suggest the market's pessimism was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-26 | |
| Oct-21 | |
| Oct-06 | |
| Oct-02 | |
| Oct-01 | |
| Sep-25 | |
| Sep-03 | |
| Aug-31 | |
| Aug-31 | |
| Aug-17 | |
| Aug-06 | |
| Aug-06 |
