Versant Clears A Low EPS Bar As Cash Flow And Platforms Growth Outrun A Shrinking Core
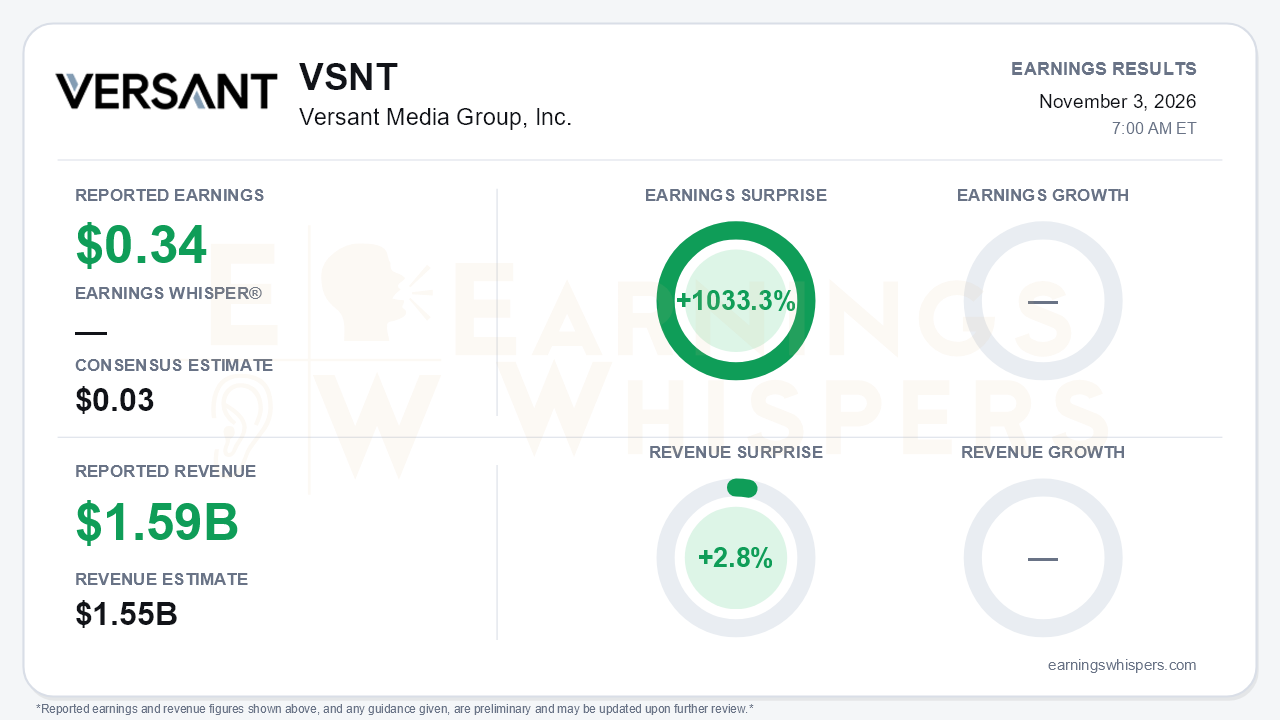
Versant Media Group reported third-quarter earnings of $0.34 per share on revenue of $1.594 billion. That cleared a $0.03 consensus estimate by 1033.3% and topped the $1.55 billion revenue forecast by 2.8%. The size of the EPS beat says more about how low the bar was than about how strong the quarter was. GAAP EPS fell from $0.56 a year ago, net income dropped to $47 million from $80 million, and total revenue declined 4.2%. The central tension is that Versant's legacy TV economics are still eroding while its cash generation, carriage security and digital businesses are improving faster than investors expected. The stock's slide suggests the market has been weighting the first half of that equation much more heavily.
The quality of the quarter deserves scrutiny. Adjusted EBITDA fell 20.9% to $353 million on a reported basis, or 7.4% against the prior-year standalone figure. That is a clear deterioration from growth of 3% in the second quarter and 5% in the first, leaving nine-month EBITDA up only about 1% at $1.68 billion. Management attributed much of the pressure to sports-rights costs that concentrate in the back half of the year.
Below the operating line, Versant now carries $53 million of quarterly interest expense it did not have under Comcast, which explains why GAAP earnings fell harder than EBITDA. Long-term debt stands at roughly $2.8 billion against $1.05 billion of cash.
The revenue segments split sharply:
- **Linear distribution:** down 5.8% to $935 million, as subscriber losses outpaced rate increases.
- **Advertising:** down 5.3% on the prior-year Ryder Cup comparison, a sharp step down from the 0.6% decline in the second quarter.
- **Content licensing:** down 24% to $41 million.
Platforms is the bright spot. Revenue there grew 9.6% to $245 million, or 17.4% excluding the SportsEngine divestiture and Full Swing acquisition. That is the fastest organic growth of the year, up from 9% in each of the first two quarters. Fandango ticketing hit a post-pandemic high, and GolfNow and Fandango1 also contributed. The segment is growing quickly but remains too small to offset linear decline. Revenue declined at the same roughly 4% pace as the second quarter and was worse than the first quarter's 1% dip.
The call was more assertive than the numbers alone would justify, but it delivered substance on the issues that matter most for a spun-off cable network company:
- **Carriage:** All four 2026 distribution renewals are complete, and 75% of subscribers are now contracted into 2028 or later, compared with "more than half" at the fourth quarter of 2025. Management said of carriage risk, "we've now answered that question." That removes a major overhang.
- **Audience:** MS NOW viewership rose about 20% year over year, accelerating from 14% in the second quarter, with eleven straight months of growth.
- **Digital:** The network launched a $7.99 monthly direct-to-consumer membership, and CNBC's digital product is slated for early 2027.
Cash flow is the strongest part of the release. Free cash flow was $302 million in the quarter and $1.21 billion through nine months, already at the top of the prior $1.0 to $1.2 billion full-year range. Management now expects to exceed that range. Revenue guidance of $6.2 to $6.45 billion and adjusted EBITDA guidance of $1.90 to $2.05 billion were reaffirmed after being raised in the second quarter. Capital returns reached $457 million year to date, and another $100 million accelerated repurchase is planned for the fourth quarter, with about $700 million of authorization remaining.
Bears still have legitimate ammunition:
- The fourth quarter absorbs four extra NASCAR races, which management called a one-off.
- SG&A is expected to rise as the company funds its direct-to-consumer and ad-supported streaming push.
- News viewership could normalize after the midterms, a fatigue risk a competitor has already flagged.
- AI and automation savings are targeted for 2027 and beyond, not the near term.
- Nine-month EBITDA of $1.68 billion means the fourth quarter must carry a meaningful share of the full-year target despite those added sports costs.
Investors were not positioned for good news. Earnings Whispers sentiment turned more negative heading into the report, falling from -0.13 to -0.28. That is a meaningful but not extreme deterioration. Shares at $32.34 were down 19.3% since the opening after the August report and sat about 11% below the 200-day moving average of $36.35. The stock peaked at $42.36 in early September and hit an inter-earnings low of $29.75 on October 1, so it entered the report closer to the bottom of its range than the top. The trend readings are mixed: momentum has turned positive, while AVWAP remains negative, consistent with a stock attempting to stabilize after a steep decline.
The bottom line is that Versant delivered a quarter that looks far better against a depressed EPS estimate than against its own history. Shrinking EBITDA, a renewed advertising decline and steady linear erosion are real. However, locked-in carriage, accelerating Platforms growth, rising MS NOW engagement and free cash flow already at the top of the prior full-year range give the company more financial flexibility than its share price implies. Whether the stock can rerate likely depends on the fourth quarter showing that the EBITDA decline reflects sports-cost timing rather than a new baseline.
Read our earnings preview for Versant Media Group, Inc.: https://www.earningswhispers.com/article/VSNT/21528
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-26 | |
| Oct-21 | |
| Oct-06 | |
| Oct-02 | |
| Oct-01 | |
| Sep-25 | |
| Sep-03 | |
| Aug-31 | |
| Aug-31 | |
| Aug-17 | |
| Aug-06 | |
| Aug-06 |
