Talen's First Full Cornerstone Quarter Tests A Freshly Raised 2026 Outlook
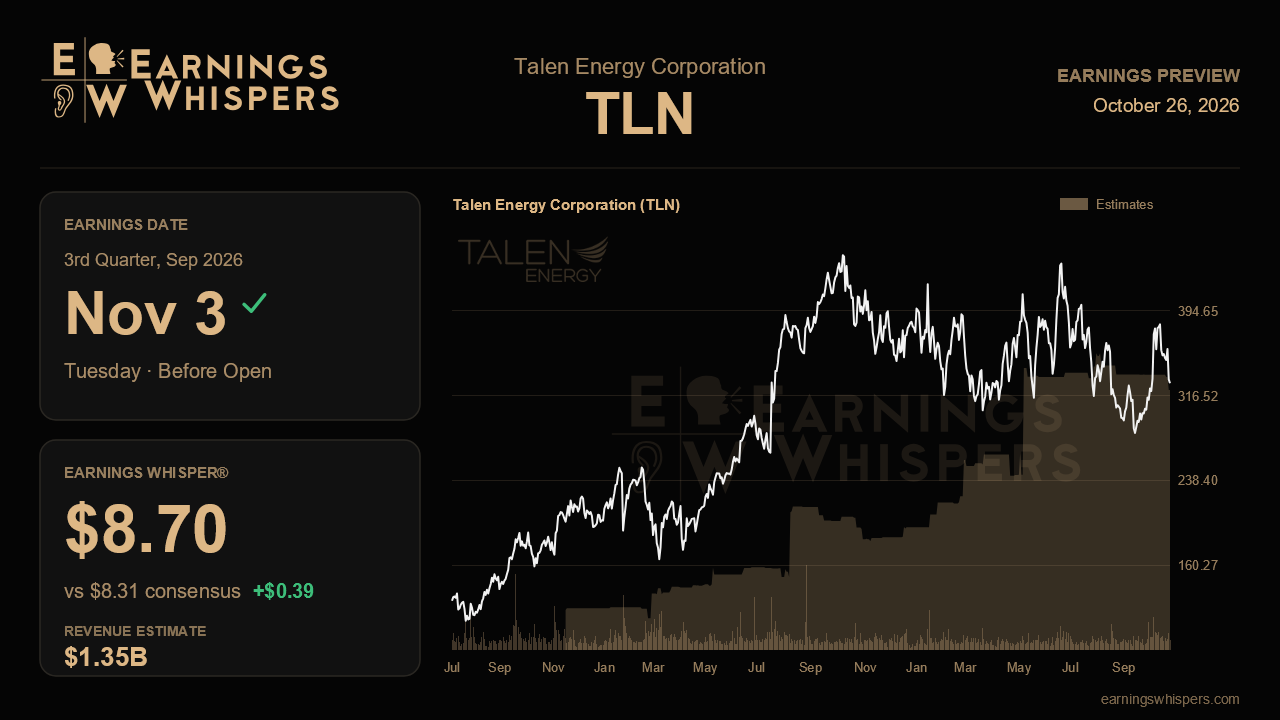
Three months ago, Talen Energy delivered the kind of quarter power bulls had been waiting for: the Cornerstone acquisition closed, full-year guidance moved sharply higher, and management argued that forward power prices had finally caught up with its long-standing view of a tightening grid. The September quarter, reported before the open on November 3, is the first to carry a full three months of the Waterford, Darby and Lawrenceburg plants during peak summer demand. That makes it the cleanest early read on whether the raised outlook was conservative, about right, or a stretch.
The Street is looking for a big number. Consensus calls for earnings of $8.31 a share on revenue of $1.35 billion, which would be roughly 249% growth in EPS and 66% growth in revenue from the year-ago quarter's $2.38 and $812 million. The sequential jump is even starker against last quarter's $0.16 and $747 million. The whisper number sits at $8.70, about 5% above consensus, so the informal bar is meaningfully higher than the published one. A result that merely matches the official estimate could still land as a mild disappointment.
The more useful yardstick is management's own math. Talen lifted its 2026 adjusted EBITDA range to $2.025 billion to $2.225 billion from $1.75 billion to $2.05 billion, and raised adjusted free cash flow guidance to $1.2 billion to $1.35 billion. With $847 million of EBITDA and $562 million of free cash flow banked in the first half, the back half needs roughly $1.18 billion to $1.38 billion of EBITDA. Because the third quarter is typically the fleet's strongest stretch, a figure that puts Talen on pace for the upper half of that range would validate the raise. A quarter that leaves the company leaning on a heavy fourth quarter to reach the midpoint would invite questions about how much of the improvement in forward spark spreads is truly flowing into realized margins.
Operating detail matters as much as the headline. Last quarter's 51% fleet capacity factor and 13% pro forma generation growth showed the plants running harder; the question now is whether that held through the summer with Cornerstone fully integrated. The main known drag is PPL zonal basis, which had widened to about $20 per megawatt-hour from a historical norm near $9 because of transmission work. Management framed that as temporary and said every dollar of basis improvement is worth roughly a dollar of 2028 free cash flow per share. Any sign of narrowing would support the upside case, while persistent or wider basis would chip at realizations in the near term. Investors should also look for an update on the pending Keystone sale, which modestly offsets 2026 EBITDA, and on the $2.8 billion buyback plan that underpins the lifted 2028 target of $48 per share in free cash flow after repurchases.
Regulation is the wild card. Management had targeted finalization of PJM's reliability backstop filing around the end of September, ahead of a compressed runway to the December capacity auction, while connect-and-manage rules on load curtailment remained unresolved. Clarity on either front, along with color on bilateral capacity bids reportedly reaching cap levels for early 2030s tenors, could shift the long-dated story more than the quarter itself.
Sentiment has warmed but not turned bullish, with bearishness easing to 18.4% from 37% before the last report. The stock has barely moved since then, slipping 0.6% while edging past a 1.3% decline in the S&P 500. At about $328 it trades below its 200-day average near $350 and in the middle of its post-earnings range, well beneath last quarter's peak near $450. The market, in other words, has not fully priced the raised outlook. The verdict will hinge on whether summer results show Cornerstone and stronger spark spreads translating into cash at a pace that keeps the upper end of 2026 guidance, and the ambitious 2028 per-share targets, credibly within reach.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Sep-30 | |
| Sep-29 | |
| Sep-21 | |
| Aug-27 | |
| Aug-22 | |
| Aug-19 | |
| Aug-19 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 |
