Talen Energy Misses The EPS Bar By A Wide Margin, But Doubled Cash Flow, 2027 Guidance And A $1.5 Billion ASR Change The Story
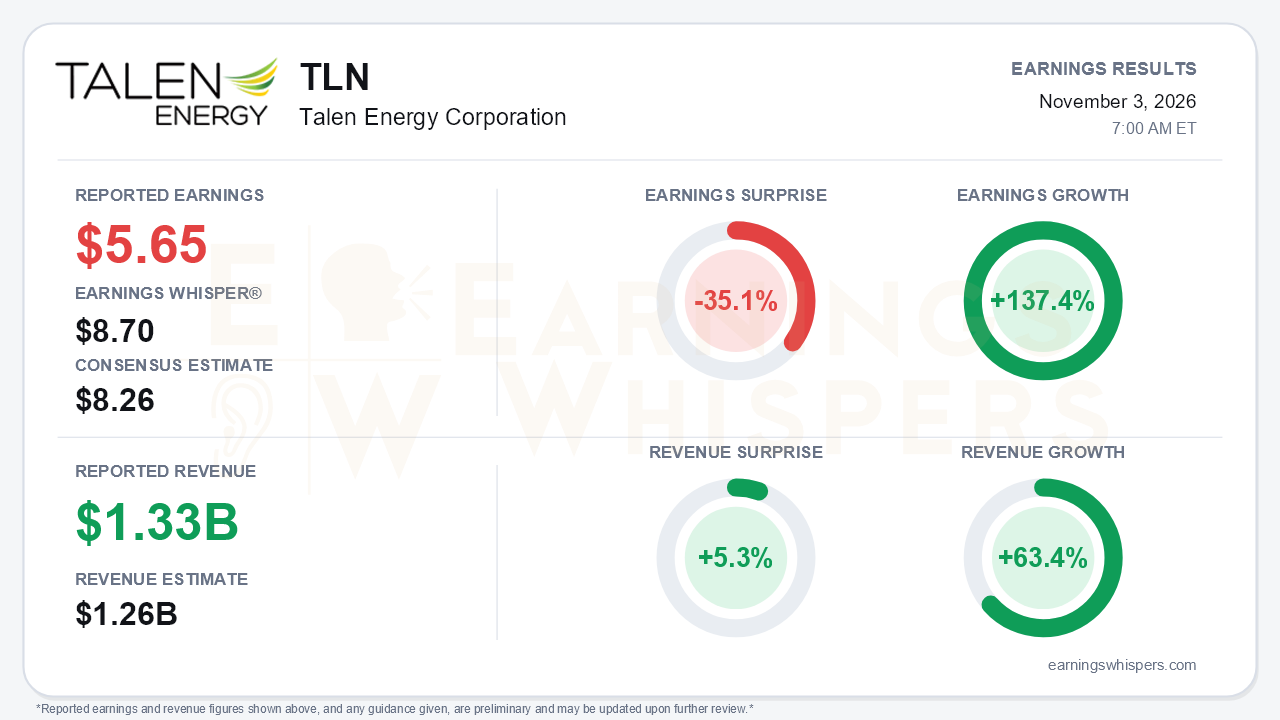
Talen Energy (NASDAQ: TLN) reported third-quarter earnings of $5.65 per share, well short of the $8.26 consensus and the $8.70 Earnings Whisper number, a 35.1% miss. Revenue of $1.327 billion beat the $1.26 billion consensus by 5.3% and grew 63.4% year over year. Earnings rose 137.4% from the prior-year quarter. The miss is real, but it is not the most important development in the report. Talen nearly doubled quarterly cash generation, introduced 2027 guidance more than 25% above 2026, and committed $1.5 billion to an accelerated buyback. The market setup is more complicated than the surprise implies.
The quality of the quarter depends heavily on which line investors focus on. On a GAAP basis, net income attributable to stockholders fell to $138 million from $207 million. Diluted GAAP EPS fell to $2.88 from $4.25. Two items drove the decline. First, unrealized mark-to-market losses on commodity derivatives reached $190 million, compared with a $36 million gain a year ago. Second, interest expense more than doubled to $148 million because of acquisition financing. Operating results moved the other way. Adjusted EBITDA rose to $669 million from $363 million, and Adjusted Free Cash Flow climbed to $433 million from $223 million. Generation more than doubled to 23.9 TWh, and the capacity factor jumped to 75.4% from 56.6%, with acquired assets, higher realized power prices and capacity revenues of $323 million (versus $166 million) all contributing. Sequentially, EBITDA and free cash flow also rebounded sharply from second-quarter levels of $374 million and $212 million. The underlying cash engine strengthened; the derivative marks and financing costs of the Cornerstone deal obscured it at the bottom line.
The call preserved, and arguably extended, a credible growth story. Management reaffirmed the 2026 midpoints of $2.125 billion in EBITDA and $1.275 billion in free cash flow, and narrowed both ranges. Those midpoints were already raised earlier in the year. The new 2027 midpoints of $2.675 billion in EBITDA and $1.625 billion in free cash flow come in above the roughly $2.6 billion pro forma figure flagged when Cornerstone was announced. About 70% of 2027 volumes are already hedged. The bigger revisions came further out: 2028 base free cash flow per share rose to about $48 from $40 last quarter, or $53 including buybacks, and management initiated a 2029 outlook of $56 to $60 per share with buybacks. Cumulative free cash flow through 2029 is now framed near $6 billion. Management's tone was notably more confident; it described the company as in a fundamentally stronger position than at any point. The new-capacity pipeline grew to more than 3 GW.
Bears have legitimate ammunition, however. Base free cash flow per share for 2029, at $46 to $50, is roughly flat with 2028. Two factors explain the stall: backwardated forward curves, with 2029 prices down more than $2/MWh year over year, and Brunner Island's shift to gas-only operation. PPL zonal basis kept widening after the September 30 marks. After four calls of pipeline discussion, there is still no second data center contract, and management flagged rising hyperscaler price sensitivity. The buyback itself carries a trade-off. It was funded by monetizing about $1.5 billion of future PJM capacity cash flows, which keeps leverage above the 3.5x target until the second half of 2027. Other risks include a possible additional PJM capacity price cap and the CEO transition from Mac McFarland to Terry Nutt. On the positive side, potential acceleration of the AWS campus load ramp could add roughly $2 per share for each year it runs ahead of schedule.
Investor sentiment improved only slightly, moving from -0.37 to -0.35, and it remains clearly negative. The stock's path explains some of that caution. Shares hit a 52-week low of $279.77 in mid-September, rallied to $390.54 by October 12, and gave back much of that move to enter the report at $332.99. That price is only 1.0% above the open following the August report and 4.7% below the 200-day moving average. Momentum and AVWAP trend readings are positive, while price trend is neutral, consistent with a stock that has stabilized but not reclaimed its longer-term trend.
The bottom line is that the headline EPS miss understates the quarter. Talen's cash flow nearly doubled, forward targets moved meaningfully higher, and the share count is shrinking quickly. The skeptics' concerns are about durability rather than the current quarter: flattening 2029 economics, widening basis, borrowed-forward capacity cash and an elusive second data center deal. Until those questions are answered, the gap between the improving cash-flow outlook and still-negative sentiment is likely to persist.
Read our earnings preview for Talen Energy Corporation: https://www.earningswhispers.com/article/TLN/21522
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 12 hours | |
| 13 hours | |
| Oct-26 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Sep-30 | |
| Sep-29 | |
| Sep-21 | |
| Aug-27 | |
| Aug-22 | |
| Aug-19 | |
| Aug-19 |
