Yum China's First Quarter Owning Pizza Hut Tests Whether Margin Gains Can Outrun Delivery Costs
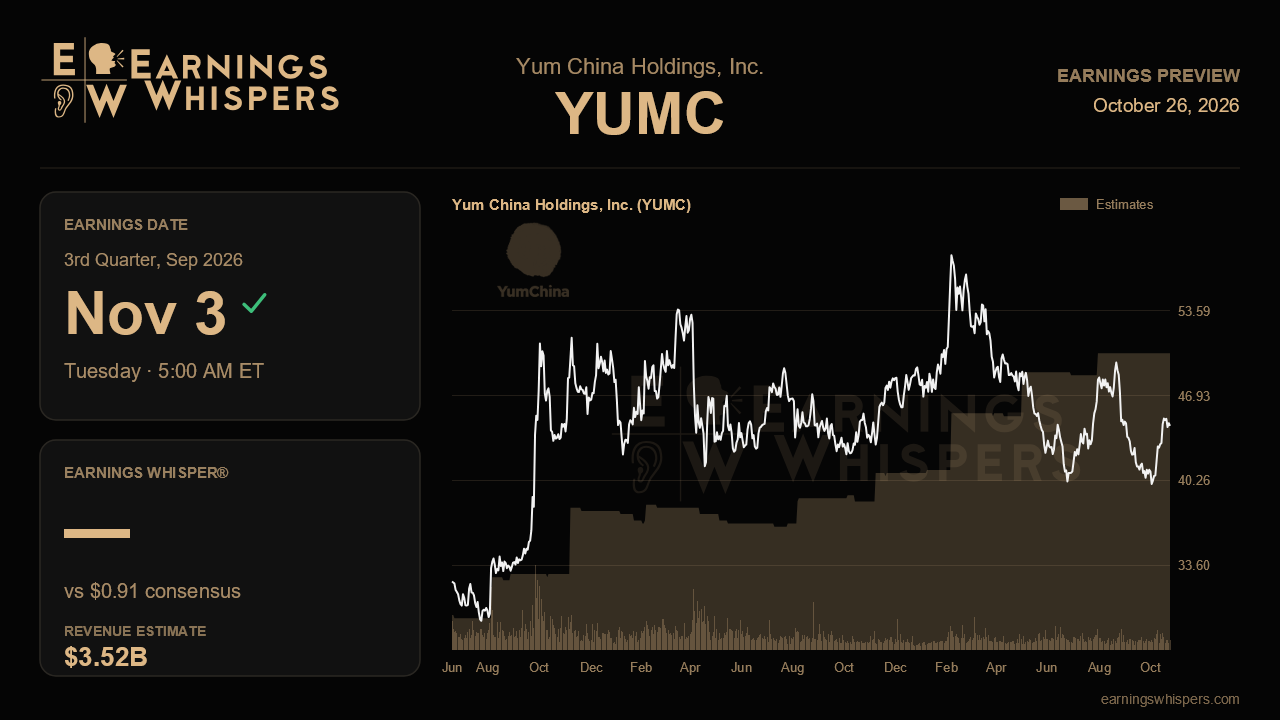
Yum China heads into its third-quarter report with a fresh asset on the books and a stock that has gone the wrong way. The company closed its acquisition of the Pizza Hut brand in mainland China in August. That makes this the first quarter in which investors can start checking management's claim that dropping the 3% license fee will add 2.8 percentage points to Pizza Hut restaurant margins. Yet shares have fallen 6.2% since the last report while the S&P 500 gained 3.3%. The market is clearly waiting for proof rather than paying for promises.
The bar is not low. Analysts expect earnings of $0.91 per share, up nearly 20% from $0.76 a year ago, on revenue of $3.52 billion, up almost 10%. That would be a meaningful acceleration from the 14% EPS growth posted in the second quarter. The revenue estimate is also notable. Second-quarter system sales grew 6% excluding currency, so a near 10% top-line gain implies the Street is counting on some combination of faster unit growth, steadier same-store sales and help from currency. Management reaffirmed its full-year group outlook last quarter rather than lifting it outside the deal, so the consensus appears to be pricing in more momentum than the company has formally committed to.
The operating story from last quarter was broad-based. Same-store sales turned positive at both KFC and Pizza Hut, roughly 1,200 stores opened in the first half, and management raised targets almost everywhere it could. The K-Pro rollout goal climbed to about 800 locations, the Pizza Hut Burger Bar target rose to 500 to 600 sites by year-end, and K-Coffee sales are expected to roughly double. The third quarter should show whether those modules are lifting traffic and sales per store or simply adding locations. Continued positive same-store sales at both brands, especially against tougher comparisons, would validate the upbeat tone. A slip back to flat or negative would suggest the first half benefited from a temporary delivery surge.
That delivery dynamic is the biggest swing factor. Delivery reached 54% of sales in the second quarter versus 45% a year earlier, costing about 140 basis points of margin, an improvement from 190 basis points in the first quarter. Management flagged that the second half laps a heavier delivery base starting in June. In practice, that cuts both ways: sales comparisons get harder, but the year-over-year rider-cost drag should shrink. If KFC margins hold near last quarter's 17.1% and the delivery drag keeps narrowing, the margin story gets stronger. Pizza Hut deserves particular scrutiny after its margin slipped 40 basis points on Burger Bar launch costs. Even a partial quarter of license-fee savings should start to show up there. Steady declines in average ticket, down 3% at KFC and 11% at Pizza Hut, also need to be offset by higher transaction counts.
Below the operating line, financing could matter as much as burgers. The roughly $1.2 billion bridge loan carries a low rate but runs only about a year, and management has floated a convertible bond as one possible long-term solution. Any update on that take-out, along with the effect of lower interest income from a smaller cash pile, will shape how much of the promised mid-single-digit accretion in 2027 and 2028 actually reaches shareholders.
Sentiment has cooled from mildly bullish before the last report to mildly bearish now. The stock sits at $44.54, below its 200-day average of $46.90 and roughly mid-range between its post-earnings low near $39.72 and high near $49.73. That leaves room for a rerating if the numbers cooperate. The central question is simple. Can Yum China show that brand ownership and narrowing delivery drag are expanding margins while traffic holds up? If it can, the case for a raised multi-year growth outlook stays intact. If not, the recent skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-06 | |
| Oct-02 | |
| Sep-24 | |
| Sep-11 | |
| Sep-03 | |
| Sep-03 |
Will Wendy's shakeup right the ship? Is Pizza Hut's split from Yum a blessing in disguise?
YUMC
Nation's Restaurant News
|
| Sep-02 |
