Yum China Matches EPS Estimates As Faster Store Growth And Margin Gains Offset A 3% Same-Store Sales Decline
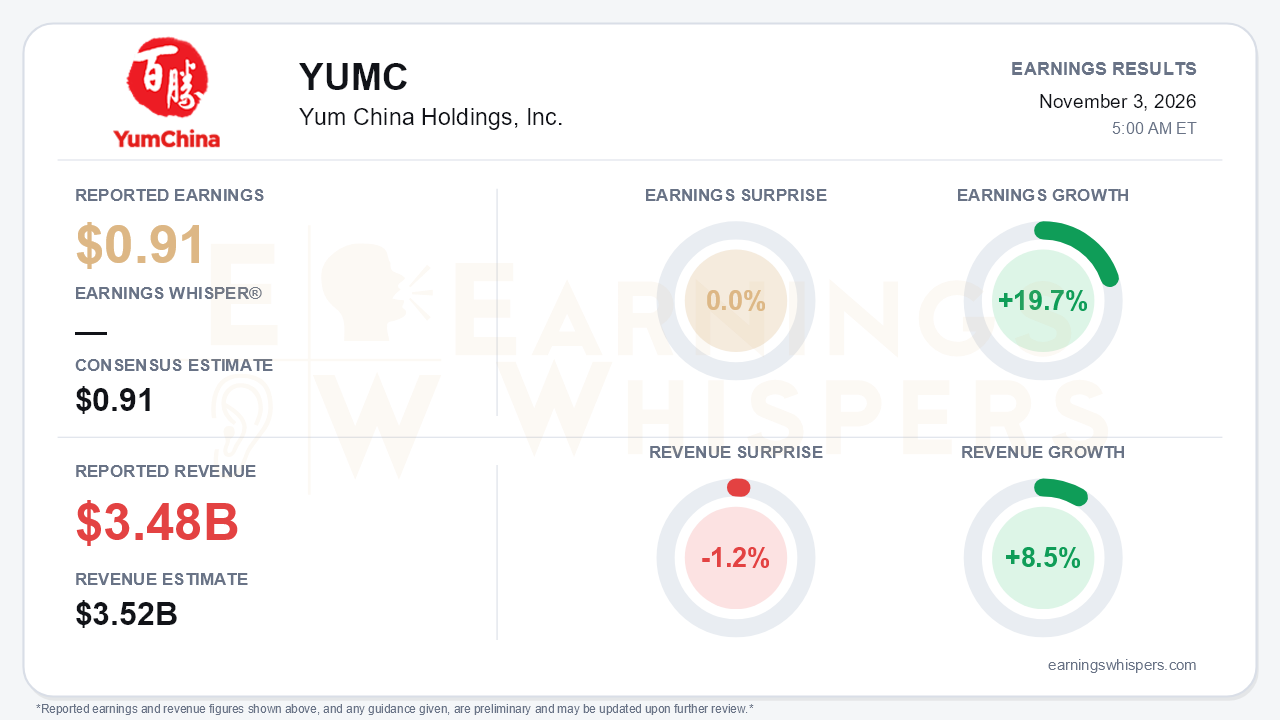
Yum China (NYSE: YUMC) earned $0.91 per share in the third quarter, exactly matching the consensus estimate, while revenue of $3.477 billion missed expectations by 1.2%. On the surface the quarter looked strong: earnings grew 19.7% year over year and revenue grew 8.5%. The central tension is that much of that headline growth came from currency, buybacks and margin levers rather than demand. Same-store sales fell 3%, and management responded by raising its 2026 store-opening target sharply. Investors are being asked to trust that unit growth and cost discipline can carry earnings while existing restaurants tread water.
The quality of the earnings growth deserves scrutiny. Excluding foreign exchange, revenue rose only 2% and core operating profit grew 6%. Currency added 6 cents to EPS, and the diluted share count fell to 343 million from 369 million, a roughly 7% reduction that did meaningful work for per-share results. Below the operating line, net interest income dropped to $7 million from $23 million. That decline reflects the cash used and debt taken on for the $1.2 billion Pizza Hut brand acquisition, which lifted short-term borrowings to $1.55 billion. Even so, the operating story was respectable. Operating margin rose 50 basis points to 13.0%, the 10th straight quarter of expansion, and restaurant margin improved 50 basis points to 17.8%.
The top line is where the weakness shows. System sales growth slowed to 3% from 6% in the second quarter, and same-store sales swung from a 1% gain last quarter to a 3% decline. Management blamed tough comparisons against last year's delivery-platform subsidies and poor weather in August. Transactions still grew 3%, the 15th consecutive quarterly gain, but KFC's average ticket fell 5% as smaller orders from KCOFFEE, KPRO and solo diners diluted check size. Management argued that dine-in and takeaway improved sequentially. It also said it deliberately chose not to chase platform subsidies in food. That is a defensible strategy, but it means the company is buying traffic with value rather than pricing power.
The margin story improved more clearly on the call. The drag from delivery rider costs, which grew with a higher delivery mix, shrank to about 30 basis points from 190 basis points in the first quarter and 140 in the second. Management expects delivery mix to hold broadly stable in the mid-50s percent range in 2027, so labor-cost pressure should be much milder next year. Management was careful to say labor costs will not fall, only rise more slowly. Pizza Hut was the standout. Restaurant margin there jumped 190 basis points to 15.3% and segment operating profit rose 29% as removing the 2.8% royalty added roughly 160-170 basis points at the brand level and about 30 basis points for the group, in line with earlier guidance.
The biggest forward-looking change is the store pipeline. Yum China raised its 2026 net new store target from 1,900 to more than 2,400, about 13% of its prior-year store base, after a record 692 openings in the quarter. Management described this pace as multi-year. It noted that more than half of new stores target underserved "double white space" markets, which should limit cannibalization of existing locations, and that the royalty savings let more Pizza Hut sites clear its 2-3 year payback hurdle. Bears have legitimate ammunition, however. Faster expansion into lower-tier cities could weigh on comps and new-store productivity. The bridge loan still needs refinancing. And the shift to returning roughly 100% of free cash flow starting in 2027, about $900 million to over $1 billion a year, is a step down from the current $1.5 billion annual pace, even with a new $1 billion repurchase authorization.
Investor sentiment was roughly unchanged, slipping from 0.069 to 0.056 and staying only mildly positive. The stock has gone nowhere since the last report. Shares sit at $47.08, down 0.8% from the post-July open and just 0.5% above the 200-day moving average. That flat result hides a volatile quarter: shares fell from an August high of $49.73 to a 52-week low of $39.72 on October 2, then rebounded 18.5% into the print. Momentum and AVWAP trend readings are positive, but the recovery leaves the stock in the middle of its range rather than at an extreme.
The bottom line is that Yum China delivered an in-line quarter whose roughly 20% EPS growth relied heavily on currency, a shrinking share count and margin levers, while same-store sales turned negative. The call preserved a credible growth story built on accelerating store openings, fading rider-cost pressure and Pizza Hut royalty savings. Whether that story holds now depends on new-store productivity and a stabilization in comps that this quarter did not yet show.
Read our earnings preview for Yum China Holdings, Inc.: https://www.earningswhispers.com/article/YUMC/21535
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 |
