XPLR Heads Into Q3 With Steady Execution, A Sliding Stock And 2027 Funding Questions
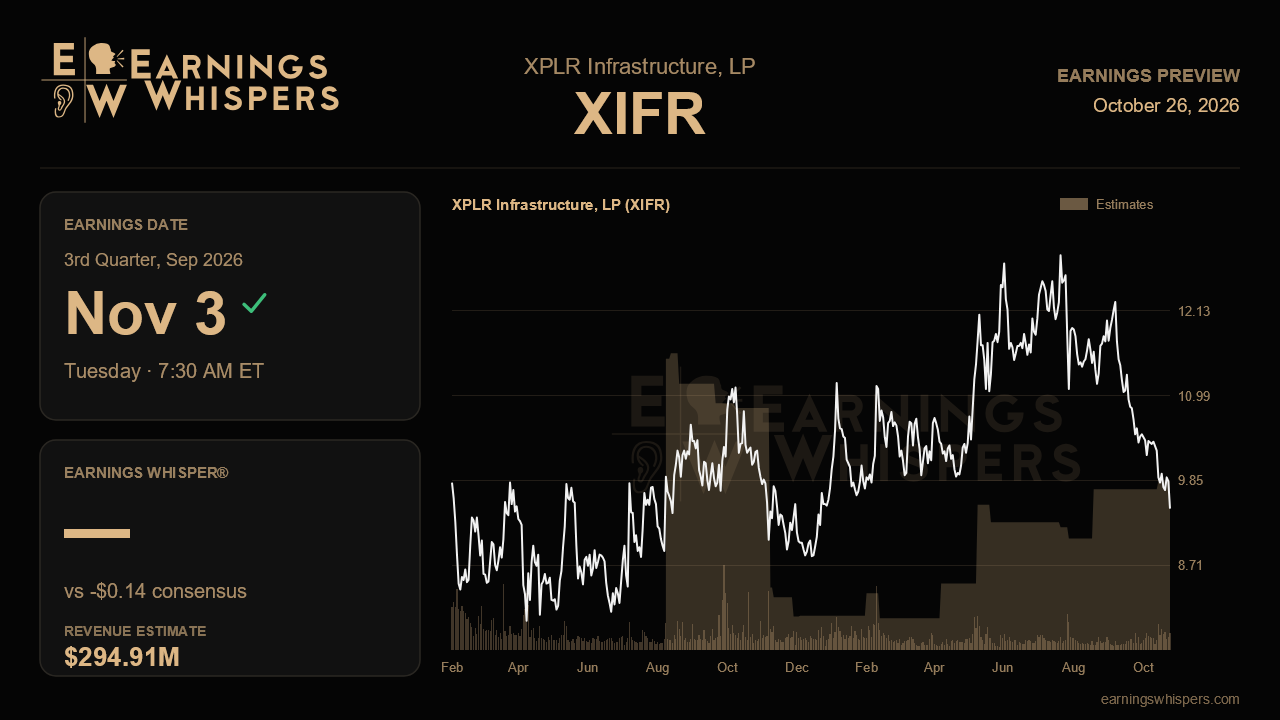
XPLR Infrastructure has spent the past year doing almost everything it said it would, and the market has responded by marking the units down roughly 21% since the last report while the S&P 500 edged higher. That gap between operational progress and share-price punishment is the defining feature of the third-quarter report due before the open on November 3. The question is no longer whether management can execute a de-risking plan. It is whether that execution is translating into enough cash flow to handle a crowded 2027 calendar without new strain on the balance sheet.
The Street is braced for a loss of about $0.14 per unit on revenue near $294.9 million. That would be a meaningful improvement from the $0.37 loss a year ago, but revenue is expected to slip about 6.4% from $315 million, and it would mark a sharp step down from the $363 million and $0.40 profit posted last quarter. Per-unit results at XPLR swing heavily on non-cash items and the accounting for its tax-equity and noncontrolling interest structures, so the EPS figure says less about the business than the reaffirmation, or not, of 2026 adjusted EBITDA guidance of $1.75 billion to $1.95 billion. That range already sits below 2024 levels after the Mead pipeline sale, so holding it is the baseline expectation rather than a win.
The operating checklist comes straight from last quarter's call. Management said the 2026 repowering program was about half complete, up from roughly 30% a quarter earlier, against an expanded plan of about 2.1 gigawatts through 2030. Another clear step forward, ideally with the 2026 program nearing completion, would confirm the cadence. The battery storage partnership with NextEra Energy Resources is another test: the Mammoth Plains and Carousel joint ventures were formed with construction slated to begin this quarter, and any slippage or cost pressure would matter because XPLR's equity stake exposes it to overruns. On the revenue side, the recontracting story gained credibility when about 90 megawatts of wind were re-signed at roughly $25 per megawatt-hour above the prior price on a 15-year deal. Additional contracts at similar uplifts would turn management's claim that about 80% of its output is priced below market into something more tangible.
The risks flagged last quarter remain live. Net operating expenses ran about $42 million higher year over year in the second quarter, largely because a roughly $45 million vendor credit from 2025 did not repeat, and full-year O&M is guided near $500 million. Costs tracking toward that figure would ease concerns; a further overshoot would undercut the efficiency narrative. Expiring tax-equity structures will also keep weighing on adjusted EBITDA optics. Most important, investors will want detail on how XPLR plans to fund the roughly $470 million SEPF 5 buyout and about $550 million of corporate debt maturing in 2027, after it repaid $500 million of convertible notes with cash last quarter.
Sentiment has improved from modestly bearish heading into the last report to modestly bullish now, yet the units sit at $9.47, essentially on the post-earnings low of $9.43 and well below the 200-day moving average near $10.98. The current range is also lower than the prior quarter's band of $10.51 to $13.25. That combination suggests a market that likes the story in principle but is unwilling to pay for it until the funding path is clearer.
The central issue is credibility on cash. Steady repowering, on-time storage construction and contained O&M would keep the improving narrative intact, but the report needs to show a believable bridge to the 2027 obligations. Without one, solid execution may continue to go unrewarded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-15 | |
| May-07 | |
| May-07 | |
| Apr-24 | |
| Mar-10 | |
| Mar-06 | |
| Feb-11 | |
| Feb-10 | |
| Feb-10 | |
| Feb-10 |
