XPLR Infrastructure Swings To A Big EPS Beat, But Trimmed 2026 Guidance And A Lower 2027 Outlook Define The Quarter
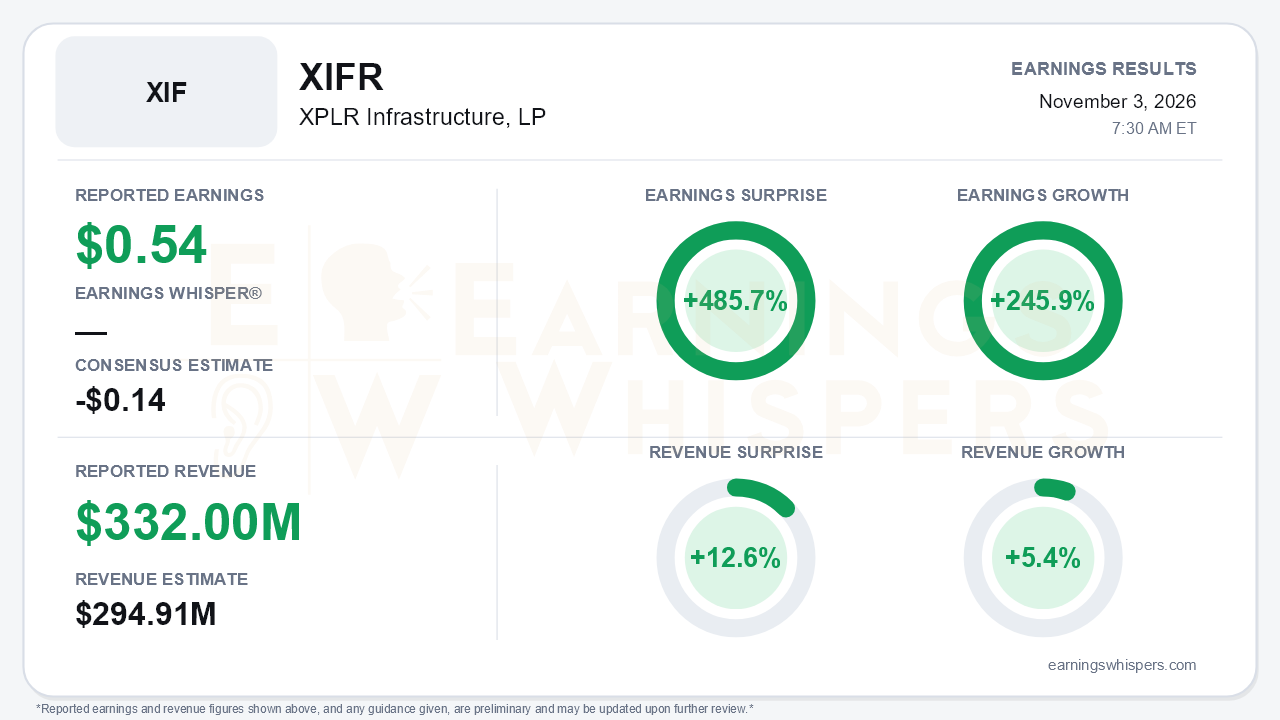
XPLR Infrastructure (NYSE: XIFR) delivered a headline beat on both lines in the third quarter. The partnership reported earnings of $0.54 per share against a consensus estimate calling for a loss of $0.14, a 485.7% surprise. Revenue of $332.0 million topped the $294.91 million estimate by 12.6%. Earnings grew 245.9% year over year and revenue rose 5.4%. The swing from an expected loss to a solid profit is the kind of print that normally changes a narrative. That is the central tension: the forward cash-flow outlook moved the other way. Management steered 2026 toward the weak end of its ranges and introduced 2027 targets well below this year's levels.
The quality of the beat deserves scrutiny. The posted release is only a notice directing investors to the company's website, so the supplied materials do not explain what drove the per-unit result. Investors in XIFR have long anchored on adjusted EBITDA and free cash flow before growth (FCFbG) rather than EPS. On those measures, the quarter was respectable rather than transformative. Q3 adjusted EBITDA was roughly $471 million and FCFbG about $164 million. Existing projects improved by $49 million and $24 million, respectively, year over year on a normalized-wind basis. Those numbers point to real operating improvement from repowered assets. Whatever lifted EPS above consensus, though, did not translate into a better full-year cash outlook.
The guidance shift is the real news. Through the fourth quarter of 2025 and the first two quarters of 2026, management reaffirmed 2026 adjusted EBITDA of $1.75 billion to $1.95 billion and FCFbG of $600 million to $700 million. Now EBITDA is expected in the lower half of that range, and FCFbG is expected at or near the low end, around $600 million. Management cited three causes:
- weak wind resource in the West, where the higher-priced PPAs sit;
- at least 3% lower fourth-quarter wind expected from El Niño;
- slightly higher net O&M costs.
The 2027 outlook is more consequential. Management introduced adjusted EBITDA of $1.56 billion to $1.70 billion, reflecting a roughly $170 million net step-down as production tax credit eligibility rolls off. FCFbG is guided to $525 million to $600 million. That includes about $25 million of tax-credit impact and roughly $20 million of higher net interest expense, and the low end embeds about 6% lower wind in Q1 2027. Guidance for 2028 FCFbG is flat with 2027, well below the $746 million generated in 2025. In other words, reported revenue grew this quarter, but the trajectory management laid out is lower and then flat.
Execution on the self-help plan continued, and the call preserved some credible positives. Repowering reached about 85% of the 2026 plan, up from roughly 50% at Q2 and 30% at Q1. XPLR sold about 400 MW of additional interconnection rights to NextEra Energy Resources in August and October:
- Half supports the roughly $80 million storage equity commitment, only about $45 million of which had been identified earlier in the year.
- About $12 million goes to project reinvestment.
The first two storage joint ventures, Mammoth Plains and Carousel, were formed in July. The partnership retired its remaining $33 million of 2026 unsecured notes, leaving no corporate maturities this year. Management said multiple gigawatts of surplus interconnection remain available to monetize. It also highlighted earlier-than-expected customer interest in contract extensions. That is a notable shift from Q2, when recontracting was framed mostly as a 2030s opportunity. It builds on the Q1 example of a 90 MW, 15-year contract at roughly a $25/MWh uplift.
The market had already been leaning bearish heading into the report. Shares opened at $11.95 after the July report. By November 2 they were at $9.65, down 19.2% and about 11.9% below the 200-day moving average of $10.96. The stock sat just 2.7% above its inter-earnings low of $9.40, set October 30, and 22.3% below its September 8 high of $12.43. Investor sentiment remained negative and weakened modestly, slipping from -0.196 to -0.253. The Earnings Whispers trend readings lean negative, with price and AVWAP trends negative and momentum neutral. The setup is more complicated than the surprise implies. A stock trading near its lows may have priced in some of the guidance disappointment, but bears have legitimate ammunition in a cash-flow profile that shrinks into 2027 and does not grow in 2028.
The bottom line is that XIFR's outsized EPS beat is the least important number in the report. Repowering, interconnection sales, storage JVs and deleveraging show management executing on what it controls. The trimmed 2026 targets, the PTC-driven step-down in 2027 and a flat 2028 leave the cash-flow story weaker than it was three months ago. Until recontracting and interconnection monetization visibly fill that gap, the guidance reset, not the headline beat, is likely to set the tone.
Read our earnings preview for XPLR Infrastructure, LP: https://www.earningswhispers.com/article/XIFR/21531
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-15 | |
| May-07 | |
| May-07 | |
| Apr-24 | |
| Mar-10 | |
| Mar-06 | |
| Feb-11 |
