Waters Heads Into Q3 With A Rallying Stock And A BD Turnaround To Prove
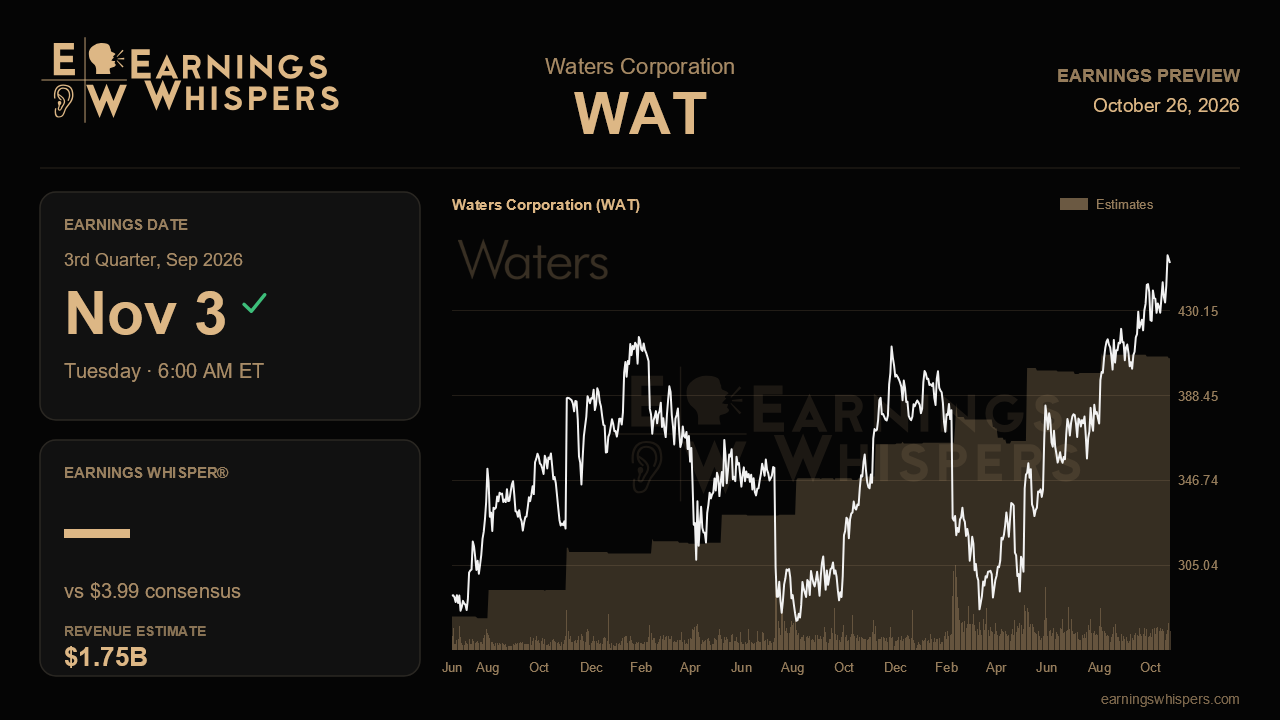
Three months ago, Waters delivered its most confident quarter since agreeing to absorb Becton Dickinson's biosciences and diagnostics businesses. Every piece of full-year guidance went up, the acquired units swung from decline to growth, and the stock has since climbed roughly 18% while the S&P 500 went nowhere. That combination makes the third-quarter report less about whether Waters can hit its numbers and more about whether the BD turnaround is durable enough to justify a share price that has already priced in a good deal of the recovery.
The Street is looking for adjusted earnings of $3.99 a share on revenue of about $1.75 billion. That EPS figure sits almost exactly at the midpoint of management's $3.95 to $4.05 range, while the revenue estimate leans toward the lower half of the company's $1.745 billion to $1.762 billion outlook. In other words, analysts have not gotten ahead of the company. The headline growth rates look dramatic, with revenue expected to more than double from the year-ago $799.9 million, but that is almost entirely the acquisition. The more honest measure of progress is the projected 17% rise in EPS from $3.40, which reflects legacy strength, synergy capture and the absorption of a large, lower-margin business at the same time.
The acquired BD operations are the swing factor. Last quarter they grew 4% on a reported basis and 6% outside China, a sharp improvement from flat results the quarter before and from steep declines when the deal model first disappointed. Management said it expects those businesses to exit the year growing faster than 6%, so this quarter should show the trajectory still pointing upward. Pricing is a second tell: realization reached 90 basis points versus a historical 50, with 150 as the target. Further progress would suggest Waters is bringing its own commercial discipline to BD, not just cutting costs. Investors should be aware, however, that BD's third quarter carries noise from the unwinding of a roughly $20 million trade inventory build in the prior year, which could make the reported growth rate look softer than the underlying demand.
On the legacy side, organic growth ran 9% in constant currency last quarter, about a point above the top of guidance, with pharma and academic and government customers both up 11% and GLP-1 testing revenue up more than 40%. Sustaining something close to that pace would validate the full-year organic outlook of 7% to 9%. Cost actions are also running ahead of plan, now targeted at about $75 million of 2026 benefit and a $200 million run rate. The catch is currency. A stronger dollar consumed about $0.25 of annual EPS last quarter and kept the full-year adjusted operating margin flat at 28.2% despite the extra savings. If the dollar stays firm, Waters could beat operationally and still post only modest upside to the bottom line.
Newer catalysts will offer early, if limited, evidence. The Bactec FXI blood culture system has FDA clearance and an installed base of roughly 12,000 aging units ripe for replacement, while the FACTS Discover A7 flow cytometer only launched in mid-September. Commentary on early order activity matters more than revenue contribution here. China flow research, which improved about 25 points last quarter, needs to keep healing, even as diagnostic pricing pressure there lingers.
Sentiment has shifted from mildly bearish before the last report to modestly bullish now, and the stock sits about 2.5% below its post-earnings high of $465.36, well above its 200-day average near $368. That puts shares close to a breakout but also leaves little cushion for a stumble. The real question is whether Waters reaffirms that BD is on track for a better-than-6% exit rate while defending the full-year guide against currency pressure and a prudent, roughly 4% implied fourth-quarter organic pace. Confirm that, and the turnaround story holds. Hedge on it, and a crowded rally could unwind quickly.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-23 | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Oct-01 | |
| Sep-14 | |
| Sep-11 | |
| Aug-26 | |
| Aug-24 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-27 |
