Waters Matches The Whisper As Legacy Growth Accelerates, But Thin Q4 EPS Growth And Weak Cash Flow Show The BD Integration Is Still Unfinished
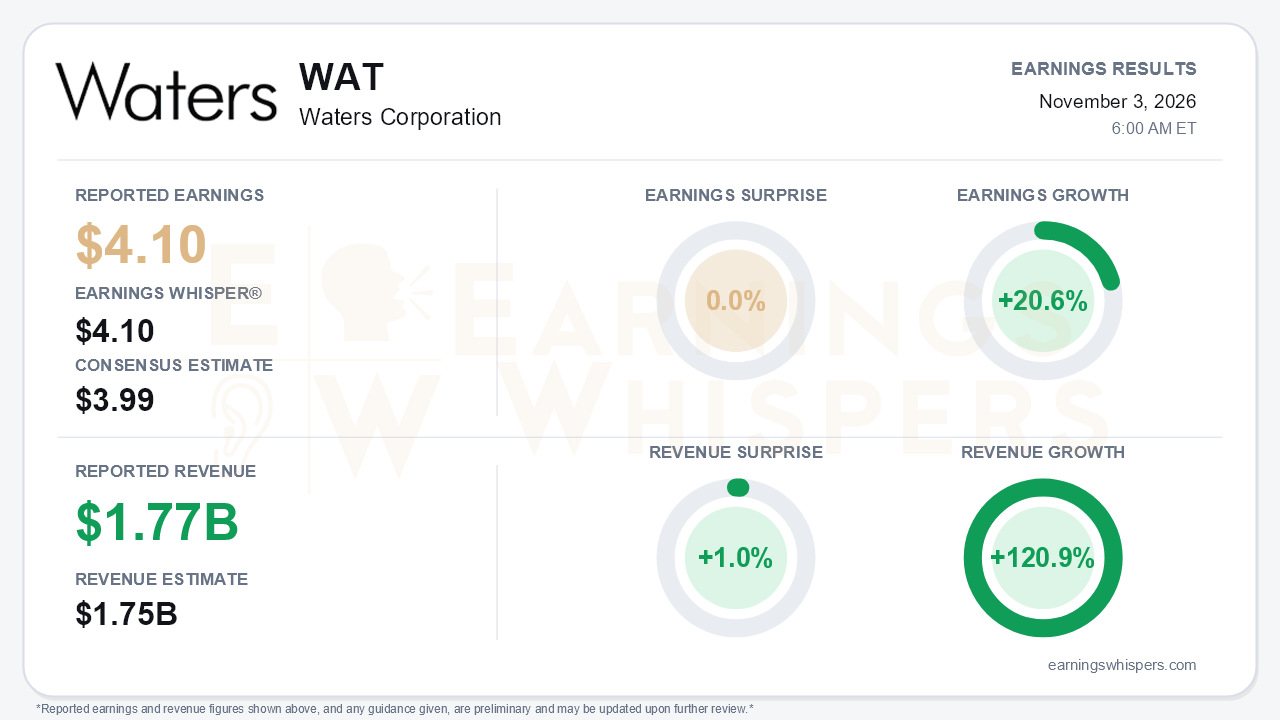
Waters Corporation delivered exactly what the market's more demanding expectations called for. Third-quarter adjusted EPS of $4.10 matched the Earnings Whisper number, topped the $3.99 consensus and the company's own $3.95-$4.05 guide, and grew 20.6% year over year. Revenue of $1.767 billion beat consensus by 1.0% and rose 120.9%, though that figure mostly reflects the February acquisition of BD's Biosciences and Diagnostic Solutions businesses. The more telling number is legacy organic growth of 10% in constant currency, up from 9% in the second quarter. Waters also raised full-year guidance for the fourth straight quarter. The central tension is that the legacy franchise is accelerating while the acquired businesses, cash conversion and near-term earnings growth still lag. The headline beat leans heavily on the core Waters engine.
The acquisition dominates the reported figures. Organic revenue rose to $871 million from $800 million. The acquired businesses contributed $896 million, only 1% above the $885 million prior-year comparable, a slowdown from 4% growth in the second quarter. GAAP EPS fell to $0.82 from $2.50, weighed down by $323 million of purchased-intangibles amortization and inventory step-ups plus integration and restructuring costs. On an adjusted basis, profitability rebounded sharply. Operating margin reached 30.1%, up from 25% in the second quarter and roughly in line with legacy Waters' 30.3% a year ago. Cost actions drove the improvement, and run-rate savings hit $200 million more than two years ahead of schedule.
The call showed broad momentum in the legacy business. Chemistry consumables grew 12% in constant currency, the sixth straight double-digit quarter. LC-MS instruments improved about 200 basis points to 10-11%, helped by replacement cycles, GLP-1 work, PFAS testing and India generics. Clinical mass spec rose 18%, and legacy China grew more than 20%. On the acquired side, flow reagents accelerated 400 basis points to 8%. Biosciences China returned to growth for the first time in 10 quarters, and BD net price realization climbed from a historical 50 basis points to 120. The soft spots were real, however. Molecular diagnostics and point of care fell 6% on channel inventory reduction and lighter respiratory testing, and China microbiology dropped more than 20% on DRG reimbursement pressure. Management characterized the acquired-business slowdown as planned, and the implied second-half constant-currency growth rate for those businesses is about 5%.
The forward story widened. Waters acquired MOBILion Systems, whose SLIM ion mobility technology gives the company an entry into a roughly $2.2 billion discovery proteomics market. Management also cited:
- HPV self-collection partnerships with Quest and LabCorp, with revenue beginning in 2027;
- dozens of new AI-native biotech customers;
- double-digit millions of reshoring-related orders already received.
The initial 2027 framework calls for mid-single-digit-plus organic growth, with a high-single-digit aspiration. It also targets 100 basis points of margin expansion to 29.2% and low-teens EPS growth. That margin target must absorb a roughly 70-basis-point headwind from adding back the first six weeks of BD costs.
Bears have legitimate ammunition on cash and near-term earnings. Free cash flow fell to $68 million from $202 million in the second quarter. Management attributed the drop to about $240 million of receivables and SAP-migration timing items plus $81 million of integration costs. Inventory sits near 160 days, against legacy Waters' 110-day target. Fourth-quarter guidance calls for revenue of $1.801-$1.819 billion but adjusted EPS of just $4.58-$4.68, only 1% to 3% growth. The quarter has four fewer selling days and requires a 14% sequential revenue step-up. The full-year EPS raise to $14.60-$14.70 was modest next to the $43 million revenue increase because of reinvestment.
Investors had largely positioned for strength. Sentiment moved from slightly negative (-0.06) to modestly positive (+0.13), a meaningful but not euphoric shift. Shares rose 17.3% from the open after the August report to $449.53. That leaves the stock about 21.5% above its 200-day moving average and 18.5% above its inter-earnings low. Shares entered the report 6.8% below the 52-week high of $482.28 set October 28, so some of the run-up had already been given back. The Earnings Whispers trend readings are uniformly positive, consistent with a stock that has been rewarded for steady guidance increases.
The bottom line is that Waters produced a high-quality legacy quarter and a credible 2027 setup, but it met elevated expectations rather than surpassing them. Accelerating organic growth, expanding margins, rising BD pricing and early synergy delivery support the thesis. Still, a 1% acquired-business growth rate, weak free cash flow, bloated inventory and nearly flat fourth-quarter EPS growth mean the integration case remains a work in progress. With the stock well above its long-term average, execution on the Q4 ramp and on cash conversion now matters more than another headline beat.
Read our earnings preview for Waters Corporation: https://www.earningswhispers.com/article/WAT/21529
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Oct-01 | |
| Sep-14 | |
| Sep-11 | |
| Aug-26 |
