Amwell's Profit Turn Faces A Seasonal Test As DHA Contract And Q4 Cash Goals Loom
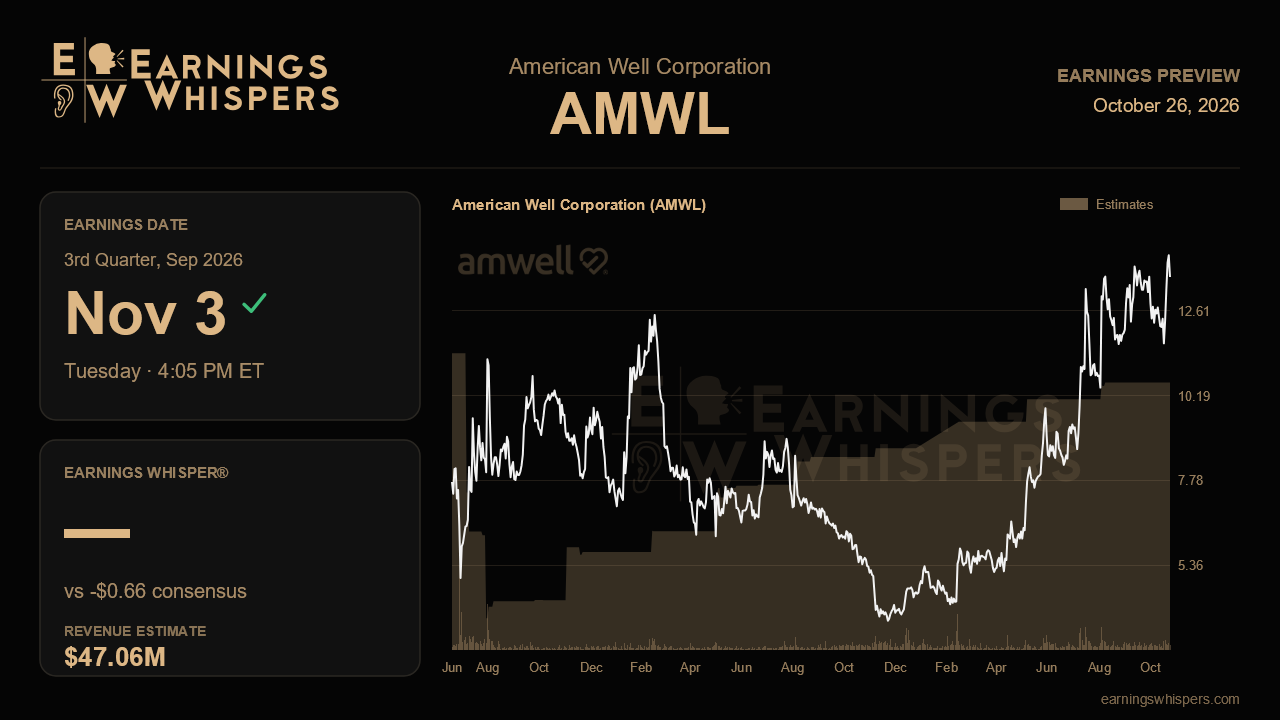
Amwell spent the past year persuading investors that a shrinking telehealth company can still become a healthier one. The third-quarter report, due after the close on November 3, is where that argument gets stress-tested. Management already warned that this quarter would step backward, with revenue and adjusted EBITDA both softer than the second quarter's best-ever showing. The question is whether the dip looks like the seasonal, one-time pause management described or the first crack in a profitability story the market has eagerly bought.
Wall Street is looking for a loss of $0.66 per share on revenue of $47.1 million. That revenue figure sits squarely in the middle of the company's $46 million to $48 million guide, so the Street is not demanding heroics. It would still mark a 16.4% decline from a year ago and a drop from the $52.0 million posted last quarter. The per-share loss is expected to be wider than the prior quarter's $0.59 but roughly 62% better than the $1.74 loss a year earlier, which captures the core trade-off here: a smaller business with a far leaner cost structure.
The more telling numbers sit below the top line. Management guided third-quarter adjusted EBITDA to a loss of $3 million to $5 million, blaming seasonality and the cost of wrapping up internal projects. Landing at or better than the top of that range would support the claim that the step-down is temporary. The full-year math matters too. Amwell raised its fiscal 2026 EBITDA outlook twice, most recently to a loss of $7 million to $9 million, and lifted the low end of revenue guidance to $200 million. With roughly $4.25 million in EBITDA losses through the first half, a midpoint third quarter implies a fourth quarter somewhere between a modest loss and slight profitability. A reaffirmed or raised annual outlook, along with a reiterated goal of positive operating cash flow in the fourth quarter, would keep the narrative intact. Any trimming would challenge it, since the stock's recent strength rests largely on that trajectory.
Quality of revenue is the other swing factor. Subscription revenue grew about 3% sequentially last quarter to $25.7 million and now makes up more than half of sales, a sign that earlier churn may be stabilizing. Another sequential gain would strengthen the case for the company's ambition of double-digit growth in 2027. A slide back would suggest the stabilization was a blip. Visit volumes, down about 28% year over year last quarter, and gross margin, which improved to 53%, are worth checking for confirmation that the mix shift is real rather than a product of divestitures flattering ratios.
Then there is the Defense Health Agency. Last quarter's intent to award Amwell a direct, sole-source contract, replacing its pass-through arrangement through Leidos, was the most important new catalyst in some time, potentially offering a multi-year relationship with broader scope. Yet the deal remains unsigned, the deadline stretches to July 2027, and management has not quantified the revenue. Progress toward signing, or any color on scope and economics, would make 2027 growth targets more credible. Silence would leave the market valuing a promise.
Expectations have clearly warmed. Sentiment has more than doubled from the prior quarter, and shares have climbed about 21% since the last report while the S&P 500 slipped, putting the stock well above its 200-day moving average near $8.69. At $13.57, it trades roughly 7% below its post-earnings high of $14.56, so it is not pressing against a breakout. The burden now is simple: Amwell must show that this quarter's weakness is planned and contained, and that the path to cash-flow breakeven and renewed growth remains on schedule.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-14 | |
| Sep-24 | |
| Sep-08 | |
| Sep-03 | |
| Sep-02 | |
| Aug-07 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-24 | |
| Jul-23 | |
| May-18 | |
| May-11 |
