Amwell Misses By A Penny But Raises Outlook And Targets First Positive EBITDA Quarter As 2027 Growth Timeline Slips
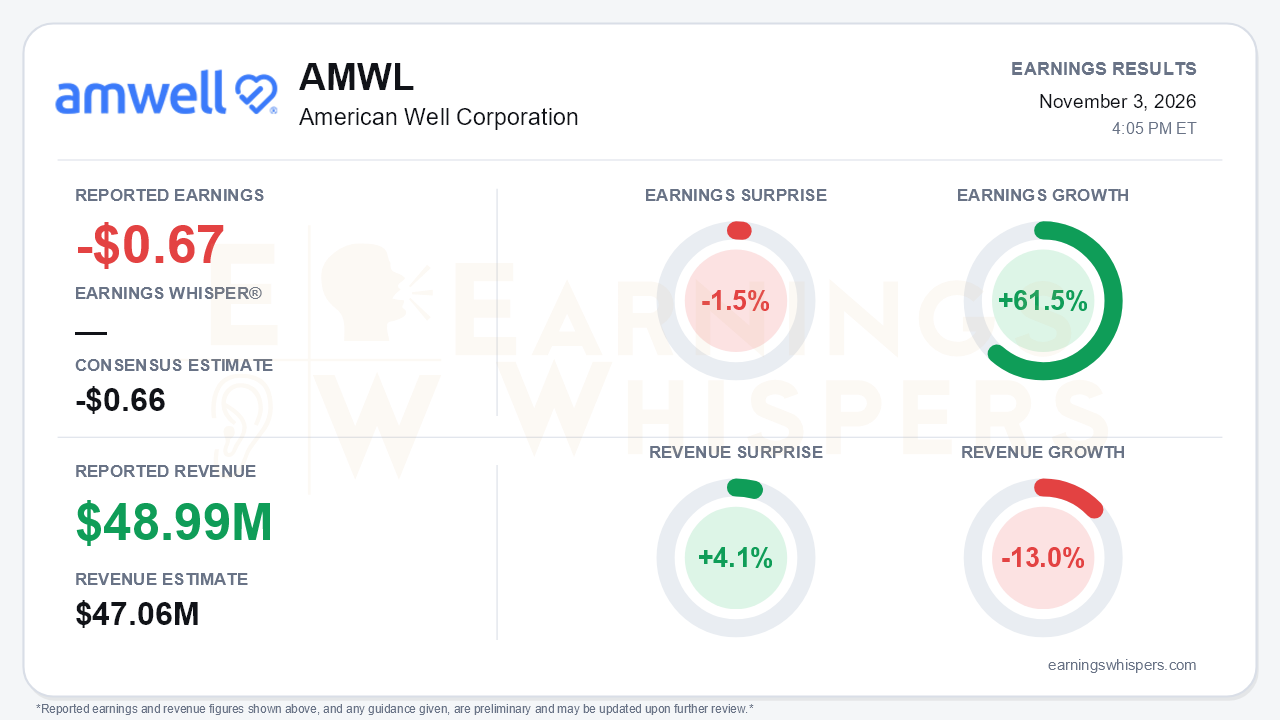
Amwell's third quarter was mixed on the headline numbers. The company lost $0.67 per share, a penny worse than the -$0.66 consensus and a 1.5% miss. Revenue of $48.99 million beat the $47.06 million estimate by 4.1% and topped management's own $46-48 million guide. The year-over-year comparison is more striking: earnings improved 61.5% as the per-share loss narrowed from $2.00 a year ago. Revenue still fell 13.0%, so the progress comes from restructuring rather than growth. That is the central tension. Amwell keeps delivering on cost and profitability targets and has now raised full-year guidance again, but the revenue base is still shrinking, and the top-line inflection investors were promised has moved further into 2027.
The quality of the quarter deserves scrutiny. Year over year, the improvement is dramatic:
- GAAP operating loss shrank to $11.7 million from $29.3 million.
- Research and development spending was roughly cut in half, to $9.6 million.
- G&A fell to $15.5 million from $21.7 million.
- Stock-based compensation dropped sharply.
- Adjusted EBITDA improved to a $3.6 million loss from a $12.7 million loss.
Sequentially, however, the picture went the wrong way. Net loss widened to $11.0 million from $9.6 million in the second quarter. Adjusted EBITDA slipped from a $1.2 million loss to $3.6 million, though it landed near the better end of the guided range. Operating expenses rose to 76.8% of revenue from 71.3%. Gross margin held near 53%, so mix did not provide any lift.
The most concerning detail beneath the headline is subscription revenue. At $23.9 million, it fell 6.8% sequentially and 22.5% year over year, reversing a 3.2% sequential gain in Q2. Management attributed the drop partly to residual churn in de-emphasized businesses. It guided to stability in Q4 but conceded some churn persists. The Amwell Medical Group (AMG) is the brighter spot:
- Visit revenue was $23.7 million.
- Revenue per visit rose to roughly $79, up 11% year over year and above $77 in Q2.
- Virtual primary care visits grew 41%, accelerating from 30%.
Total platform visits, however, fell 30.5% year over year to 0.8 million.
Guidance is where the bull case lives:
- **Full-year revenue:** raised to $204-206 million from $200-205 million.
- **Full-year adjusted EBITDA:** raised to a loss of $7-8 million. That is the fourth straight improvement from an initial range of -$18 million to -$24 million.
- **Fourth quarter:** revenue of $48-50 million and adjusted EBITDA of breakeven to +$1 million, which would be the company's first positive EBITDA quarter. Management is leaning toward the upper end.
- **Cash flow:** management reiterated its objective of positive operating cash flow in Q4.
Nine-month operating cash burn was just $1.9 million, versus $48.6 million a year ago. That figure was helped by a sizable build in accrued liabilities, however, and does not include $8.6 million of capitalized software development. Cash ended near $181 million, down from about $196 million at the end of Q2.
The forward catalysts are substantial, but they are not yet bankable. The Department of Veterans Affairs signed a non-binding letter of intent to deploy the Amwell platform enterprise-wide. The VA serves more than 9 million veterans, and 2.9 million used VA telehealth in fiscal 2025. Management framed the deal as potentially fully incremental and said it would not require material headcount additions. The definitive agreement is still under negotiation, with implementation targeted for early 2027. Timing, scope and economics are undisclosed and remain subject to federal procurement. The direct Defense Health Agency contract was described as in its "final throes" and is likely to close this quarter. The cost of the delays is the 2027 outlook. On the Q2 call, management floated mid-teens growth if pipeline deals closed. Now new government contract start dates have slipped later into 2027, so that growth will not cover a full year. Bears have legitimate ammunition here. Shrinking subscription revenue and delayed contract starts mean the near-term top line still depends on deals that are not yet signed.
The market entered the report leaning optimistic. Shares closed at $12.52 on November 2, up 12.0% from the open after the August report and about 40% above the 200-day moving average of $8.94. The stock had pulled back 17.4% from a 52-week high of $15.16, set on October 29 just days before earnings, suggesting some of the VA-driven enthusiasm had already cooled. Investor sentiment remained modestly positive and edged slightly higher, from 0.147 to 0.171, which is hardly a crowded bullish setup. The Earnings Whispers trend readings are mixed: momentum is positive while sequential growth and AVWAP remain negative.
The bottom line is that Amwell continues to execute on the part of the story it controls: costs, EBITDA and cash burn. The fourth-quarter breakeven guide and the VA letter give the turnaround narrative real substance. But the penny EPS miss, the sequential slide in subscription revenue and the softened 2027 growth framing show that the revenue inflection is still a promise rather than a result. Until the DHA and VA agreements are signed and recurring revenue stabilizes, the profitability progress is credible while the growth story remains provisional.
Read our earnings preview for American Well Corporation: https://www.earningswhispers.com/article/AMWL/21547
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-14 | |
| Sep-24 | |
| Sep-08 | |
| Sep-03 | |
| Sep-02 | |
| Aug-07 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-24 | |
| Jul-23 |
