AtriCure's 75% Rally Raises The Bar As Margins, Competition And MIS Face Third-Quarter Test
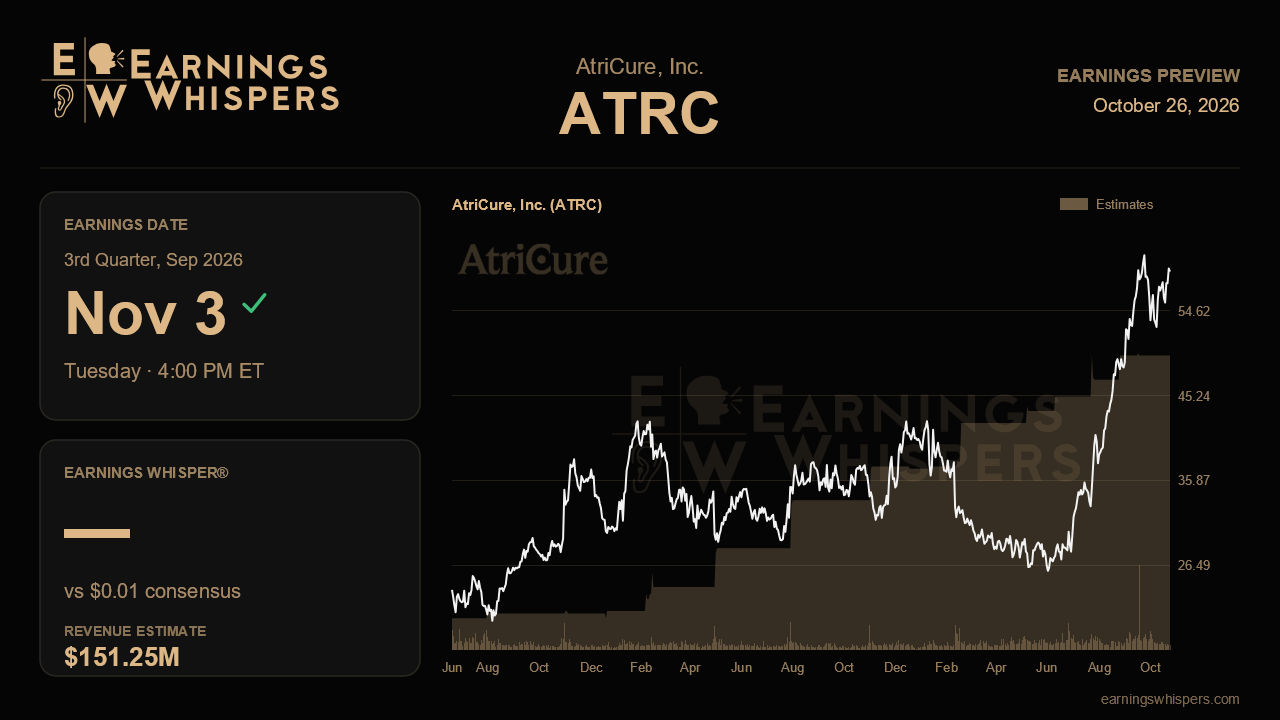
AtriCure enters its third-quarter report as a very different stock than it was three months ago. Shares have climbed about 75% since the company raised its full-year outlook in August, trouncing the S&P 500's roughly 3% gain. That move turns a quarter that might otherwise look like a seasonal breather into a referendum on whether the profitability breakout management described last time is durable, or merely a strong spring.
The Street's numbers look cautious. Consensus calls for earnings of about a penny a share on revenue of $151.3 million. That revenue figure would be up 12.7% from a year ago but slightly below the $153.6 million booked in the second quarter. The earnings estimate compares with a loss of a penny in the year-ago period, a swing that looks dramatic in percentage terms but is small in dollars. Management lifted its 2026 outlook to $0.24 to $0.32 a share on revenue of $602 million to $610 million. Full-year consensus sits at $0.13, well below the bottom of that range, while the $604.7 million revenue estimate is comfortably inside it, a bit under the midpoint. With the first half delivering roughly $0.18 a share, guidance implies meaningful second-half profit. The modest quarterly estimate suggests analysts either have not fully caught up or doubt the back half, which gives AtriCure room to clear the earnings bar if margins hold.
Margins are the crux. Gross margin ran above 77% in each of the first two quarters, up from 75% for 2025. Management argued this reflects a lasting shift in product mix rather than a temporary geographic tailwind. It also flagged a second-half headwind as a new manufacturing plant comes online. A gross margin that slips only modestly while adjusted EBITDA tracks toward the raised $85 million to $89 million target would support the structural story. A sharper drop would raise questions about how much of the first-half strength was sustainable.
The growth engine needs to keep firing too. Pain management has grown in the high twenties for four straight quarters, helped by the CryoSphere Max probe, which now accounts for about three-quarters of U.S. pain revenue. The new Cryo XT amputation probe was expected to contribute more in the second half, so early traction there would be welcome. Appendage management, up 14% last quarter, is the segment most exposed to change. Edwards is entering alongside Medtronic, and management built some customer trialing of the newcomer into its outlook. Growth that holds near double digits would ease shareholder anxiety about share loss; a noticeable slowdown would make competition the dominant narrative. Open ablation, which grew 11%, carries an extra storyline because a new quality metric on concomitant atrial fibrillation treatment takes effect in 2027 and could spur adoption.
The soft spots remain familiar. U.S. minimally invasive and hybrid ablation sales have slid for several quarters, and management has not yet called a bottom. International growth cooled to about 7% in constant currency, with weakness in the UK and Germany and lost UK reimbursement for a cryo probe. Signs of stabilization in either would be a bonus. On the pipeline, the Box NOAAF trial passed 500 patients and remains aimed at full enrollment by year-end ahead of a first-half 2027 data readout, so an update on pace matters for the stock's longer-term thesis.
Sentiment has turned from clearly bearish heading into last quarter to slightly positive now, a shift that pales next to the price action. At about $59, the stock sits far above its 200-day average near $37.50 and a few percent below its post-earnings high of $61.70. The question that will define this report is whether AtriCure can absorb plant-related margin pressure and new appendage competition while keeping its full-year profit guidance intact. Doing so would validate the rerating; wavering on either would leave a richly priced stock exposed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Sep-11 | |
| Sep-04 | |
| Aug-25 | |
| Jul-27 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-02 | |
| Jun-29 | |
| May-27 | |
| May-27 | |
| May-05 | |
| Apr-28 |
