AtriCure Delivers Third Straight Beat-And-Raise As U.S. Growth Accelerates, But A Softer Implied Q4 Meets A Stock Already Up 78%
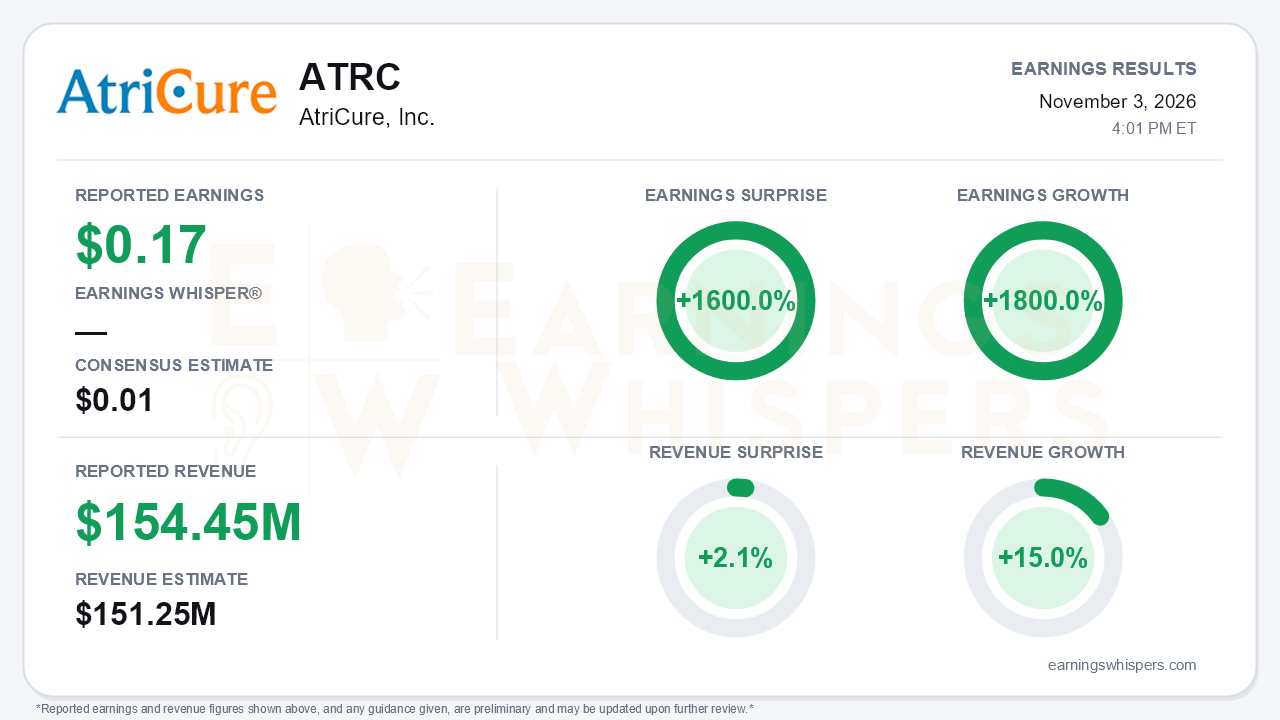
AtriCure (NASDAQ: ATRC) turned in another clean beat-and-raise for the third quarter. Adjusted earnings of $0.17 per share topped the $0.01 consensus by 1600.0% and compared with a loss a year ago, a 1800.0% improvement. Revenue of $154.45 million beat the $151.25 million estimate by 2.1% and rose 15.0% year over year. That growth rate accelerated from 12.8% in the second quarter and 14.3% in the first. On a GAAP basis, the company earned $0.08 per share, a swing from a $0.01 loss in the year-ago quarter. Management again lifted every major full-year target. The fundamental story is improving, but the market priced much of that improvement in before the report. That is the central tension.
The quality of the quarter holds up well. Gross margin expanded 180 basis points to 77.3% on favorable product and geographic mix. SG&A grew only about 6% against 15% revenue growth, and adjusted EBITDA jumped 51% to $26.8 million. The gap between GAAP and adjusted earnings comes almost entirely from a $4.5 million acquired IPR&D charge, which the call tied to a PFA milestone. That charge, along with a sharp rise in R&D spending to $32.1 million from $22.9 million, explains why GAAP net income fell to $4.1 million from $9 million in the second quarter. The underlying spending reflects investment, not deterioration. Cash rose $19.2 million in the quarter to $187 million, so the company is funding its clinical pipeline internally.
Beneath the headline, U.S. growth did the heavy lifting.
- **U.S. revenue:** rose 17.1%, up from 13.6% in the second quarter.
- **U.S. open ablation:** grew 20.8% to $43 million, compared with 12.1% growth last quarter. EnCompass now accounts for more than 70% of the category.
- **U.S. pain management:** surged 34.6% to $28.1 million. The newer cryoXT probe topped $1 million in a quarter for the first time, at roughly $1.5 million.
The softer spots are real, however.
- **Minimally invasive ablation:** U.S. sales fell to $5.4 million from $7.4 million a year ago, as PFA catheters keep eroding Hybrid procedures.
- **International:** growth slowed to 6.1% in constant currency from 7.1%, with Europe under funding pressure.
- **Appendage management:** worldwide growth eased to roughly 12%, down from 14% and 16% in the prior two quarters, as a new LAA competitor entered the market. Management flagged that a second entrant is possible.
The guidance raise deserves scrutiny. Full-year adjusted EBITDA guidance moved to $91 million to $94 million, up from $85 million to $89 million, and adjusted EPS guidance rose to $0.40 to $0.46 from $0.24 to $0.32. The revenue midpoint, however, rose only about $2 million, less than the roughly $3 million third-quarter beat. The updated range implies fourth-quarter revenue of roughly $157 million to $161 million, the smallest third-to-fourth-quarter sequential step-up in recent history. It also implies a step-down in adjusted EPS, partly because gross margin is guided lower as a new manufacturing facility carries a full quarter of costs. R&D is set to keep climbing in 2027 with a dual-energy EnCompass IDE trial and BoxX follow-up work.
The catalyst calendar is unusually dense and supports the longer-term story. BoxX-NoAF enrollment has passed 880 of 960 patients, up from about 500 last quarter. A readout is targeted for spring 2027, with PMA approval expected in 2028, and the company plans to expand sales territories ahead of that launch. Other developments include:
- 510(k) clearance for the 30mm AtriClip FLEX-Mini, with a December launch.
- LAX2 data showing a 56% stroke reduction in high-risk patients.
- TRAC AF registry results showing 91% one-year freedom from AFib with EnCompass.
- An STS concomitant AFib quality metric that goes live January 1, 2027.
The market setup is more complicated than the surprise implies. Shares have climbed 77.7% since the open after the July report, to $59.88. That puts the stock about 57% above its 200-day moving average and just 5% below the $63.00 52-week high set on October 28. Investor sentiment moved the opposite way, falling from -0.23 to -0.50 heading into the report. That is a meaningful shift deeper into negative territory and suggests skepticism about how much upside remains after the run. The Earnings Whispers price, momentum and AVWAP trend readings remain positive, while sequential growth is neutral. That neutral reading fits the softer implied fourth quarter.
The bottom line is that AtriCure delivered genuine acceleration in its core U.S. business, a materially higher profit outlook and a clinical pipeline approaching a major 2027 inflection. Bears still have legitimate ammunition: decelerating appendage growth amid new competition, continued MIS erosion, a modest revenue raise and a fourth quarter guided to a seasonal margin and earnings step-down. With the stock near its highs and sentiment souring, the hurdle now is sustaining momentum into BoxX-NoAF rather than simply beating a low bar.
Read our earnings preview for AtriCure, Inc.: https://www.earningswhispers.com/article/ATRC/21552
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Sep-11 | |
| Sep-04 | |
| Aug-25 | |
| Jul-27 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-02 | |
| Jun-29 | |
| May-27 |
