Community Healthcare Trust Faces First Proof Test Of Its Post-Dividend-Cut Turnaround Plan
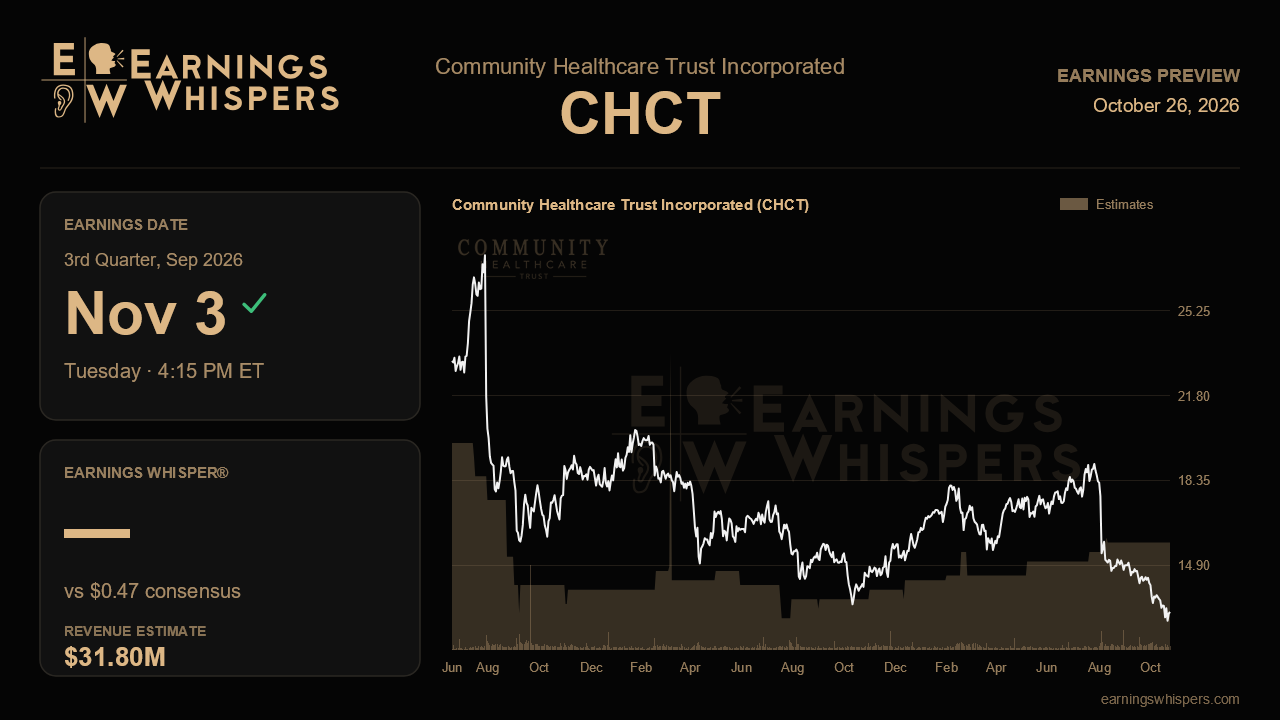
Three months ago, Community Healthcare Trust traded its long streak of quarterly dividend increases for a growth plan. The market's verdict so far has been harsh. The shares have fallen nearly 22% since that report, roughly 20 percentage points worse than the S&P 500, and now sit near $13, well below the 200-day moving average of about $16.49 and only a few percent above the post-earnings low of $12.58. The entire trading range since the last report sits below the prior quarter's floor of $16.67. When the outpatient healthcare landlord reports third-quarter results after the close on November 3, the question is simple: is the turnaround producing measurable progress, or did the dividend cut merely buy time?
The Street is not expecting a pretty quarter. Consensus calls for earnings of $0.47 per share, down about 16% from $0.56 a year ago, on revenue of roughly $31.8 million, up a modest 2.3%. That pairing matters. Revenue is inching higher, so the projected earnings drop points to per-share pressure rather than a collapse in the rent roll. Management cautioned that gaps between selling assets and redeploying the proceeds can create quarter-to-quarter drag, and per-share results had already been stuck at 55 to 56 cents for four straight quarters. If results come in at or near the consensus, a lower print will not by itself break the story. The bigger concern is whether the figure looks like a temporary dip or a new, lower baseline. No formal guidance is available to anchor the estimate, so the commentary around the number will carry unusual weight.
The most concrete test is occupancy. Management set a target of 90.5% by year-end, up from 89.8%, and outlined a path to 92% by the end of 2027, worth up to $6 million of incremental operating income. Leasing momentum supports the ambition: more than 100,000 square feet of new leases were signed in the first half, already ahead of all of 2025. Signed leases do not equal paying tenants, though. A move up from 89.8% this quarter would validate the plan. Another flat or lower reading would revive doubts, because occupancy drifted sideways for most of the past year.
Two specific catalysts should show up in this report. The Lafayette, Louisiana behavioral hospital joint venture was slated to begin paying rent early in the third quarter. Its contribution is a near-term check on whether reinvestment translates into income. The long-troubled geriatric behavioral tenant has lifted rent from about $200,000 a quarter to roughly $370,000, still far short of the roughly $800,000 it paid before its distress. Management targeted a signed purchase agreement for that operation's sale this quarter and a closing by year-end. Investors waiting more than a year since the original letter of intent will want evidence that state regulatory hurdles are clearing, not another slip.
Capital deployment is the third leg. The company raised its 2026 acquisition target to $85 million to $90 million, funded partly by the $25 million to $30 million the dividend cut frees up over two years. Yet the contracted pipeline had shrunk from $146 million to $99 million over several quarters. A weak share price also rules out accretive equity issuance, leaving asset sales as the main funding lever. Progress on closings and a replenished pipeline would ease fears that the target is aspirational.
Sentiment has soured: bearish readings deepened to about 45% from roughly 33% before the last report. That lowers the bar somewhat, but it also reflects a credibility gap. The new 33-cent dividend is meant to sit at 60% to 65% of cash earnings. A sustained per-share run rate well below last year's 56 cents would test that math. Ultimately, the report hinges on whether occupancy gains, the Lafayette rent and the behavioral sale show the reset is turning into growth, or whether flat results simply look like a lower ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-14 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-17 | |
| Jun-24 | |
| May-05 | |
| May-05 | |
| Apr-30 | |
| Apr-13 | |
| Feb-23 | |
| Feb-18 | |
| Feb-18 | |
| Feb-17 |
