Community Healthcare Trust's AFFO Beat Shows The Reset Is Working, But Slipping Deals And A Stalled Hospital Sale Keep The Stock Down
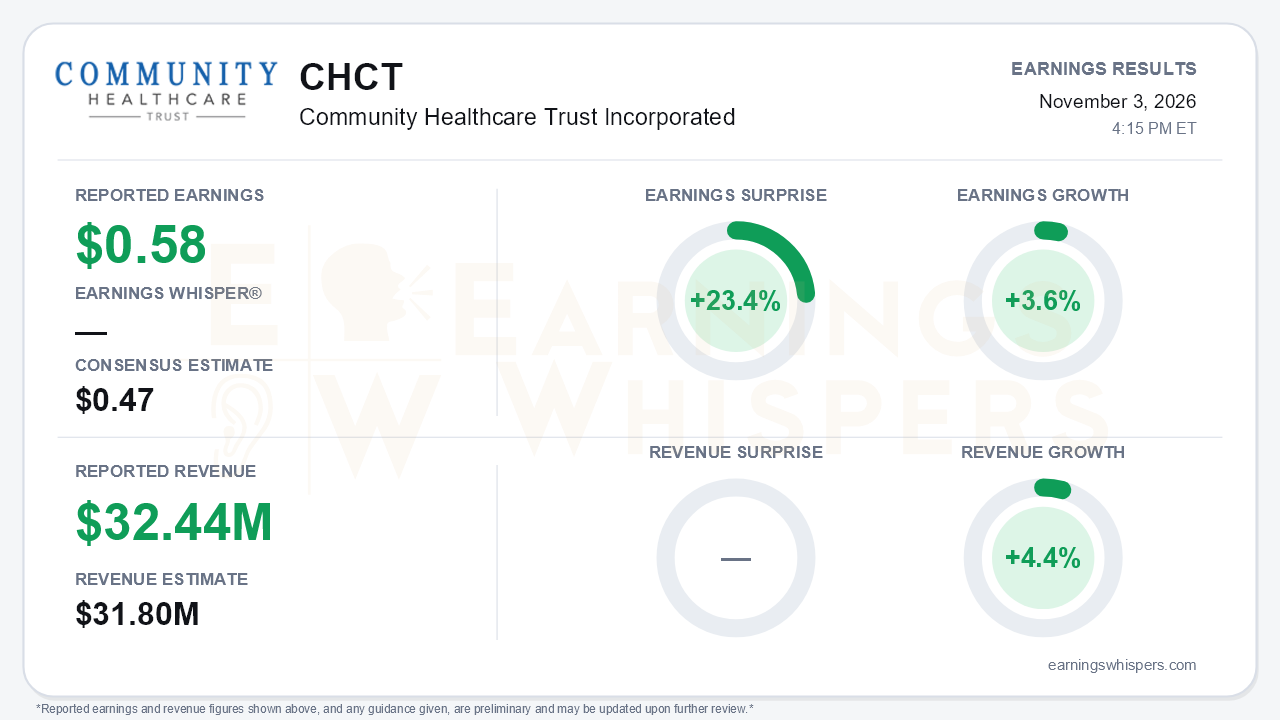
Community Healthcare Trust delivered the first clear financial evidence that its August strategic reset is gaining traction. AFFO of $0.58 per share beat the $0.47 consensus by 23.4% and grew 3.6% year over year. Revenue of $32.44 million topped the $31.8 million estimate by 2.0% and rose 4.4% from a year ago. The beat was broad: FFO of $0.54 also cleared consensus, and GAAP net income rose to $0.09 per share from $0.03. The central tension is that the improving income statement sits beside a deal calendar that keeps slipping. That is a large part of why the stock has not been rewarded.
The quality of the beat deserves scrutiny. The biggest sequential swing came in G&A, which fell to $4.2 million from $4.9 million in the second quarter and $5.1 million in the first. Much of that drop came from deferred compensation. Fully amortized restricted stock and forfeited performance units at June 30 reduced expense by about $0.9 million versus the prior quarter. That is a major reason FFO per share jumped to $0.54 from $0.48 in the second quarter and $0.49 in the first. AFFO adds back stock-based compensation, so it tells a more measured story. It rose to $0.58 from $0.56 in both of the prior two quarters, a real but modest step up after a flat stretch. Interest expense continues to work against the company. It reached $7.5 million versus $7.1 million a year ago, and debt climbed to $558 million from $532 million at year-end.
Underneath the headline, the operating trends moved in the right direction. Occupancy edged up to 90.1% from 89.8%, its first improvement after holding flat for two quarters. That keeps it on track toward management's 90.5% year-end 2026 and 92% end-2027 targets. Revenue grew 3.9% sequentially. Leverage fell 0.2 turns to 5.8x. Management guided G&A to stay lower year over year for the next few quarters. Lafayette behavioral redevelopment rent has commenced, and three more redevelopments are slated to start leases in the first half of 2027. The speculative suite program has also expanded to one project under construction, one in permitting and three in design. Rent from the troubled geriatric behavioral hospital tenant rose to about $540,000 from roughly $370,000 in the second quarter and $200,000 in the fourth quarter of 2025.
The bears have legitimate ammunition on execution. The $99 million, four-property acquisition pipeline, priced at 9.1% to 9.75% expected returns, slipped again. The first closing moved from the third quarter to the fourth, the second to the first quarter of 2027, and the last two out to mid-2027 through early 2028. That puts the company's earlier 2026 acquisition target at risk and creates earnings leakage between asset sales and reinvestment. The behavioral hospital sale is the bigger disappointment, and the two sources describe it differently:
- **Press release:** characterizes the prospective buyer as finalizing diligence and drafting definitive agreements.
- **Call:** management acknowledged that buyer exclusivity has lapsed, called itself "frustrated," and said it is now engaging alternative buyers.
The call commentary is more current and more candid, and it suggests the deal is less certain than the release implies. The marketed disposition pool also shrank to more than $30 million from more than $70 million. On the positive side, an inpatient rehab sale will generate a $9.1 million fourth-quarter GAAP gain, with proceeds being 1031-exchanged into a replacement facility expected to close late in the quarter.
The market has been unforgiving through the reset. Shares have fallen 21.6% from the $16.65 open after the August report, which carried the dividend cut from $0.48 to $0.33. At $13.06, the stock sits about 20% below its 200-day moving average. Earnings Whispers price and AVWAP trends remain negative. Investor sentiment slipped further into negative territory, from -0.33 to -0.40, a meaningful but not dramatic deterioration. The weak share price has a practical cost. The company issued no ATM equity because management views the stock as undervalued relative to private-market values. That limits its funding flexibility just as it hopes to step up acquisitions at 9% to 10% yields in 2027.
The bottom line is that CHCT's third quarter validated the cost and occupancy side of the reset. AFFO now covers the reduced $0.33 dividend comfortably, and the earnings beat was real even if lower compensation expense flattered FFO. Investors, however, are pricing the execution side, and there the news worsened:
- acquisitions keep sliding to later dates;
- the behavioral hospital sale has effectively reset;
- the disposition pipeline is thinner.
Until management converts its pipeline into closed deals, improving quarterly numbers may struggle to outweigh skepticism about timing.
Read our earnings preview for Community Healthcare Trust Incorporated: https://www.earningswhispers.com/article/CHCT/21556
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-14 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-17 | |
| Jun-24 | |
| May-05 | |
| May-05 | |
| Apr-30 | |
| Apr-13 | |
| Feb-23 |
