Avis Budget Faces Peak-Season Test As Shrinking Fleet Meets Fading Travel Demand
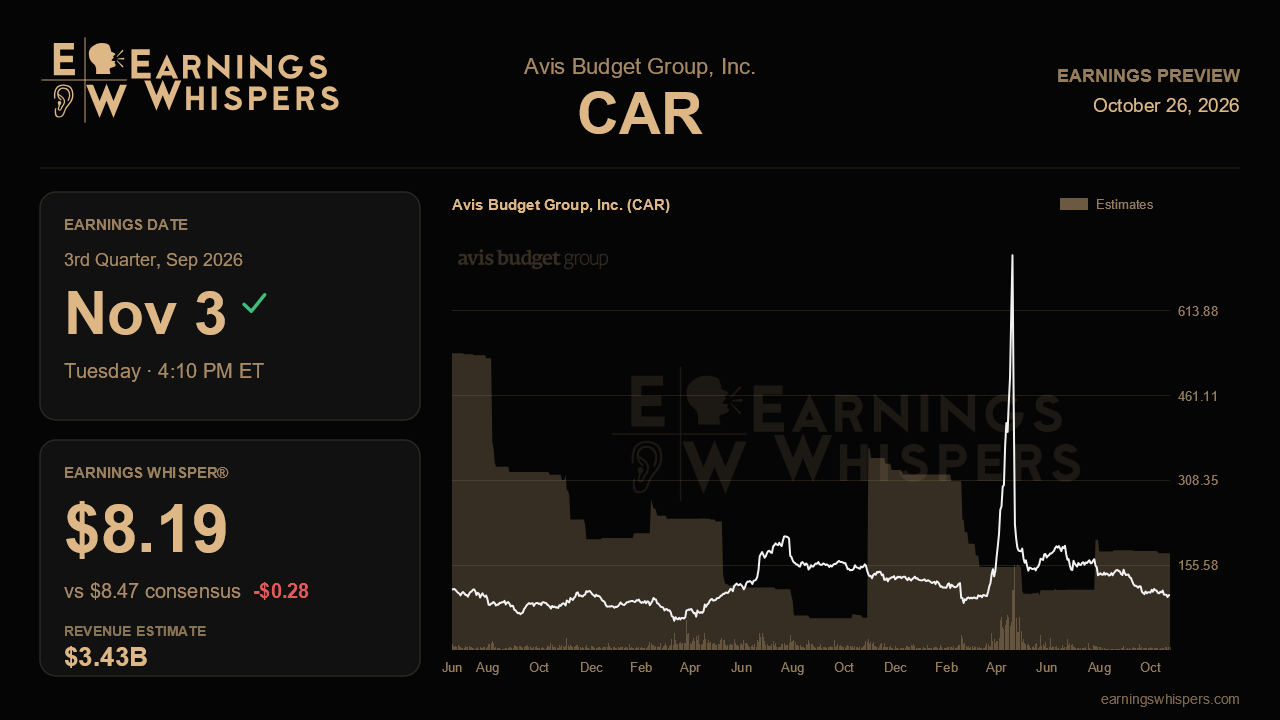
Avis Budget Group spent the second quarter proving it could make more money while renting fewer cars. The third quarter, which it reports after the close on November 3, is where that strategy faces its hardest test. Summer is the industry's profit engine, and management has already cautioned that this quarter will resemble the last one in its lower fleet and flat pricing, minus the one-time gains from selling vehicles that flattered second-quarter results. With the stock down roughly a third since the last report, the market has clearly decided the demand story matters more than the margin story.
The Street expects earnings of $8.47 per share on revenue of about $3.43 billion. That would be a 16.2% drop in earnings and a 2.5% revenue decline from a year ago, when the company earned $10.11 on $3.52 billion. This is a contraction quarter by design, not a recovery quarter. The whisper number sits at $8.19, a modest but meaningful notch below consensus, suggesting traders have already shaded expectations lower in light of management's warning not to extrapolate the prior beat. Clearing the whisper may matter more than clearing the published estimate.
The key reference point is the full-year adjusted EBITDA target of $850 million to $1 billion, reaffirmed for a second straight quarter. Management framed that outlook as not relying on a broad demand recovery, which was a notable retreat from the first quarter's more hopeful tone. That shift happened for good reason. Bookings softened in early May, the anticipated boost from the World Cup and America 250 celebrations never showed up, inbound international travel fell, and TSA check-ins slid from flat in April to about 2% below prior-year levels early in the third quarter. If summer traffic stayed that weak, holding the EBITDA range intact would require cost and fleet discipline to do nearly all the work.
That discipline is the bull case. Americas utilization hit a company record of 73.2% in the second quarter, segment EBITDA rose 7.7% on falling revenue, and pricing per day was positive for a second consecutive quarter, roughly 3% higher after adjusting for rental-length mix. Validation this quarter would look like utilization holding near record levels during peak season, revenue per day staying at least flat, and margins expanding again without help from fleet-sale gains. Per-unit depreciation is a critical tell: it dropped to an unusually low $301 last quarter as cars were sold early, and a sharp snapback toward the first quarter's roughly $380 would expose how much of the margin improvement was timing. Challenges would include deeper revenue declines than expected, renewed pricing pressure in an oversupplied European market, International EBITDA falling further after an 11% drop, and recall-grounded vehicles, already around 18,000, adding more cost.
The balance sheet is the other subplot. Management loosened its year-end leverage goal from below 6x to a reduction of at least a full turn, implying around 6.4x, while warning that refinancing costs are rising. Progress on court approval of the $650 million Pentwater settlement, partly earmarked to retire 2027 notes, would help offset that disappointment. The Waymo partnership in Dallas and the premium Avis First rollout are worthwhile updates but unlikely to move this quarter's numbers.
Sentiment remains bearish, though less so than heading into the last report, and the stock trades near $101, close to its post-earnings low of $97.23 and far below its 200-day average of $154. Expectations are low, but the stock's weakness reflects real fears. The decisive question is whether Avis can show that shrinking into soft demand protects profits at peak season, leaving the full-year EBITDA range credible without one-time gains. If it can, the selloff looks overdone. If not, the margin story starts to look like a shrinking business in disguise.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Sep-14 | |
| Aug-27 | |
| Aug-24 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Aug-03 | |
| Jul-29 | |
| Jul-29 |
