Avis Budget Misses Badly As Soft Travel Demand Overwhelms Record Utilization And Pushes Guidance To The Low End
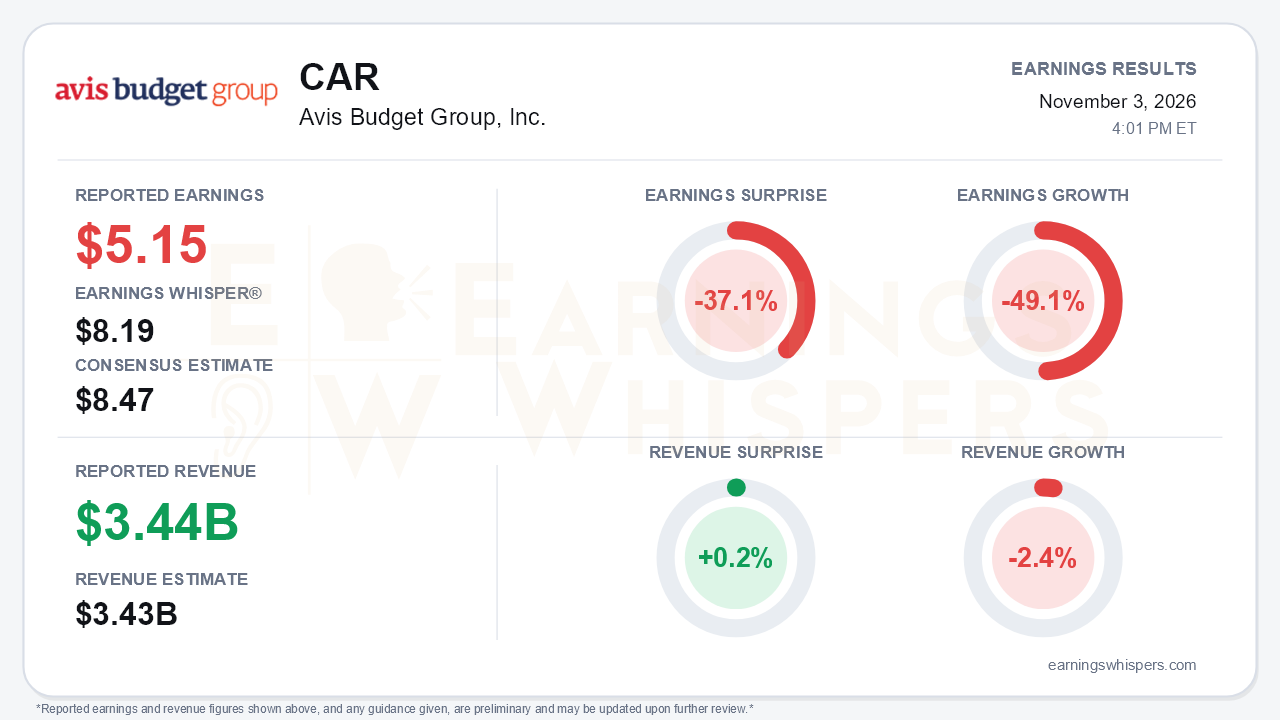
Avis Budget Group delivered a sharp third-quarter earnings miss, and the more important story is what it did to the year. Diluted EPS of $5.15 fell well short of the $8.47 consensus and the $8.19 Earnings Whisper number, a 37.1% shortfall, and earnings fell 49.1% from a year ago. Revenue of $3.436 billion edged past the $3.43 billion consensus by 0.2% but declined 2.4% year over year. Adjusted EBITDA fell 8% to $513 million, roughly $50 million below what management had signaled in July. Full-year adjusted EBITDA guidance was effectively cut to about $850 million, the bottom of the prior $850 million to $1 billion range. That is the central tension. Avis is running its fleet better than at any point in two decades, but softer travel demand and costs that did not flex with volume more than offset the operational gains.
The year-over-year EPS comparison needs some context. Last year's third quarter included $109 million of legal-matters income booked within operating expenses. Net income attributable to non-controlling interests also jumped to $16 million from $1 million, which widened the gap between the $199 million net income headline and the $183 million attributable to shareholders. Neither item rescues the quarter, though. Rental days fell 3% and total revenue per day was essentially flat at $71.54 excluding currency. Underlying operating expense stayed roughly level despite the lower volume, producing a modest decline in adjusted EBITDA margin. Americas per-unit fleet costs rose 7% to $330 a month as Q2's unusually low $301 reversed. Total fleet costs of $316 were up 4%, which management said was within expectations. Americas EBITDA fell 8% to $365 million and International fell 5% to $180 million.
The call explained why the promised growth turned into a decline. Demand deteriorated each quarter of the year. TSA volumes went from up 1.5% in Q1 to down 0.7% in Q2 and down 2.8% in Q3, the weakest reading since early 2021, with August down 4.4%. International inbound travel fell about 8%. Avis shrank its average fleet 5% and pushed utilization to 74.0%, with the Americas at 74.1%, a third-quarter record. But semi-variable costs failed to adjust, costing roughly $14 million of leverage in the Americas. International distribution costs also climbed as the mix shifted toward leisure. Management's tone turned noticeably more apologetic after confident Q1 and Q2 calls, which is uncomfortably reminiscent of the Q4 FY2025 miss.
The case for patience rests on pricing and cash. Americas revenue per day ran roughly 1% negative in August, then improved to about +4% in September and +4% in October. October produced positive revenue growth despite a fleet about 7% smaller, and October and November bookings point to mid-single-digit pricing gains. The Q4 guide of roughly $165 million in EBITDA compares with $5 million a year ago. Nine-month adjusted free cash flow reached $198 million, a $750 million improvement over 2025. Management also described $1 billion of EBITDA as a near-term floor and said it is 'not off the table' for 2027. It cited a revenue-management overhaul replacing its 15-year-old pricing system, with benefits targeted by summer 2027, along with tolling and claims-cost initiatives. Investors should treat those statements as aspirations, especially given the credibility cost of this quarter's reversal.
The balance sheet remains a real constraint. Net corporate leverage rose to 7.9x from 7.4x in Q2, or about 6.9x pro forma for the $650 million Pentwater settlement received October 5. The earlier goal of getting below 6x by year-end now looks out of reach. The sources disagree on the size of the debt paydown. The press release cites a redemption notice for the remaining $350 million of 5.750% 2027 notes, while the call analysis references a $250 million redemption bringing corporate debt to about $5.7 billion. Recalls also remain a drag, with roughly 14,000 vehicles grounded and $79 million of direct cost year to date.
The market had already priced in much of the damage. Shares fell 27.1% from the post-July open of $150.07 to $109.34 and sit 28.7% below the 200-day moving average. Price and AVWAP trend readings remain negative. Investor sentiment nonetheless improved meaningfully, moving from -0.23 to a roughly neutral +0.03. That suggests some investors were looking past the quarter toward the exit-rate pricing and settlement cash rather than bracing for further downside.
The bottom line is that Avis missed on earnings, gave back the upper end of its guidance range, and saw leverage move the wrong way, all while executing better operationally than it has in years. The turnaround thesis now depends on whether September and October pricing gains persist against a soft demand backdrop, and on whether management can make costs flex. After two consecutive guidance disappointments in four quarters, bears have legitimate ammunition. The deeply discounted share price and improving sentiment, however, show the market is already wrestling with how much bad news is left.
Read our earnings preview for Avis Budget Group, Inc.: https://www.earningswhispers.com/article/CAR/21554
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Sep-14 | |
| Aug-27 | |
| Aug-24 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 |
