Sterling Infrastructure (STRL): Time to Buy the Dip Before Q3 Earnings?
Sterling Infrastructure STRL stock has fallen more than 60% from its 52-week and all-time high of over $1,000 a share, putting the infrastructure construction company on investors' radars ahead of its Q3 results on Wednesday, October 28, after the market closes.
With STRL still up 400% in the last three years and trading near $360 a share, the steep selloff may present a compelling buying opportunity as Sterling continues to benefit from surging demand for AI data centers, advanced manufacturing facilities, and other critical infrastructure projects.
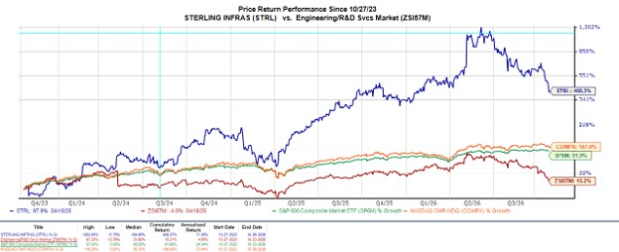
Image Source: Zacks Investment Research
Sterling's Q3 Expectations
Sterling is expected to deliver another quarter of impressive growth, with the Zacks Consensus Estimate calling for Q3 earnings of $6.07 per share, representing a 74% increase from EPS of $3.48 in the prior-year quarter.
Quarterly revenue is projected to climb nearly 70% to $1.17 billion compared to $689.02 million a year ago, largely driven by the company's E-Infrastructure Solutions segment, which supports the construction of data centers, semiconductor facilities, and other large-scale industrial projects.
Notably, Sterling has surpassed earnings expectations for 14 consecutive quarters, posting an impressive average EPS surprise of 27.21% in its last four reports.
Furthermore, Sterling ended Q2 with a record $4.33 billion backlog, up 116% year over year and providing considerable revenue visibility as demand for mission-critical infrastructure continues to accelerate.
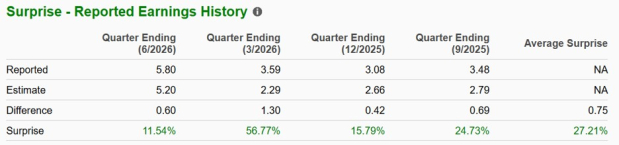
Image Source: Zacks Investment Research
STRL's Valuation Looks Much More Attractive
Following its dramatic pullback, Sterling stock trades at 18X forward earnings, a much more reasonable valuation considering the company's exceptional growth trajectory.
Encouragingly, STRL now trades at a discount to the benchmark S&P 500 and its Zacks Engineering - R and D Services industry average, while trading well below its decade-long peak of 49X forward earnings and closer to its median of 14X during this period.
Adding to the appeal, Sterling raised its full-year 2026 guidance following Q2, projecting adjusted EPS of $19.70-$20.30 per share, with the $20 midpoint representing an 84% increase from 2025.
Meanwhile, revenue is expected to reach $4-$4.15 billion, reflecting roughly 64% growth at the midpoint.
Although concerns about elevated AI infrastructure spending and the sustainability of hyperscaler capital expenditures remain risks, Sterling's rapidly expanding backlog and earnings outlook suggest the recent selloff may be excessive.
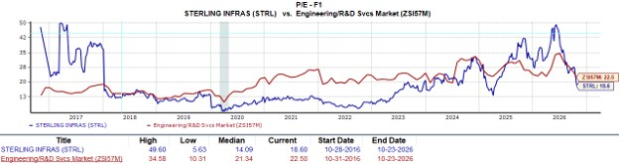
Image Source: Zacks Investment Research
Bottom Line
Sterling Infrastructure stands out as one of the more intriguing buy-the-dip targets ahead of its Q3 earnings, particularly for investors seeking exposure to the ongoing AI infrastructure buildout at a more reasonable valuation.
Supporting this outlook, STRL currently sports a Zacks Rank #2 (Buy), with its robust earnings momentum, substantial backlog, and increasingly attractive valuation suggesting meaningful upside potential if Sterling delivers another strong quarterly report.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sterling Infrastructure, Inc. (STRL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-20 | |
| Oct-15 | |
| Oct-05 | |
| Sep-04 | |
| Aug-27 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 | |
| Jul-27 | |
| Jul-23 | |
| Jul-22 | |
| Jul-20 |
