Sterling Infrastructure Crushes Estimates And Raises Guidance Again, But A Shrinking Signed Backlog, Mix-Diluted Margins And A 27% Slide Complicate The Setup
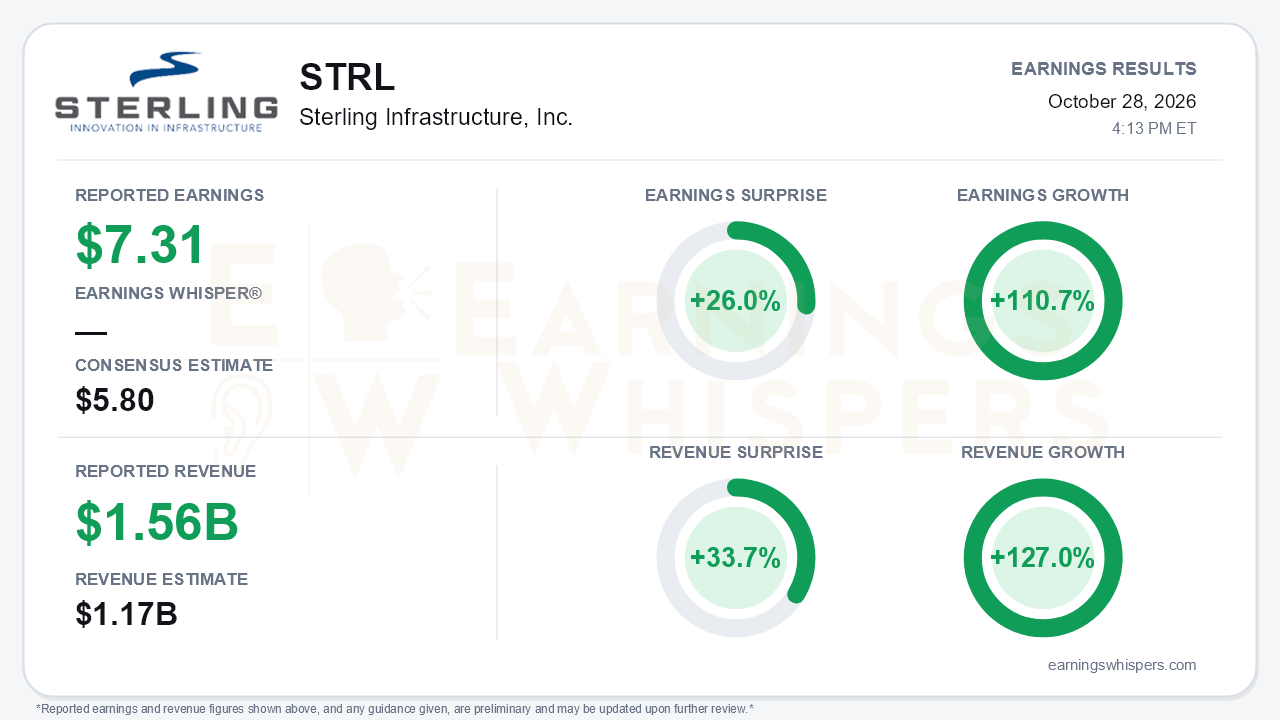
Sterling Infrastructure delivered another blowout quarter. On the Earnings Whispers basis, it earned $7.31 per share on revenue of $1.564 billion, beating the $5.80 consensus by 26.0% and the $1.17 billion revenue estimate by 33.7%. Earnings grew 110.7% year over year, and revenue jumped 127.0%. Management also raised full-year guidance for the third time this year. The company's own figures differ from the Earnings Whispers number: adjusted EPS was $7.58 and GAAP diluted EPS was a record $6.92. On any of these measures, the quarter was exceptional. The central tension is that the stock has been moving the other way. Shares sit roughly 27% below where they opened after the August report, while signed backlog and segment margins are showing the first signs of strain.
The quality of the beat is strong, though not flawless. Organic growth was 70%. The CEC electrical acquisition contributed $425.6 million, and management said CEC revenue roughly quadrupled on a pro forma basis. Total adjusted operating margin was essentially flat at 21.3%, compared with 21.2% a year ago, and that flat line hides offsetting moves underneath.
- **E-Infrastructure:** Adjusted margin compressed to 23.2% from 26.8% as lower-margin electrical work grew faster than high-margin site development. Site margins held at first-half levels, and CEC margins improved both sequentially and year over year.
- **Transportation:** Adjusted margin expanded 410 basis points to 19.7%, even as revenue slipped 3% while resources shifted toward data center work.
- **Building Solutions:** Adjusted operating income fell 39% on soft homebuilding demand, and management expects that weakness to persist through 2026.
The balance sheet shows the cost of this growth. Accounts receivable swelled to $1.23 billion from $501 million at year-end, and working capital consumed $204 million. As a result, nine-month operating cash flow of $427 million trailed net income. Cash fell to $217 million after Sterling repaid term debt, spent $107 million on buybacks and more than doubled capital expenditures.
The backlog data deserves scrutiny. Signed backlog rose 61% year over year to $4.14 billion, but the quarter's 0.9x book-to-burn means signed backlog shrank sequentially. That outcome matches the softer third-quarter awards management had flagged in the prior quarter. Combined backlog, which includes $2.0 billion of unsigned awards, booked at 1.4x, and management cited nearly $8 billion of total scoped work, up about 90% year over year. Bulls can point to that pipeline. Bears can point out that a growing share of visibility now sits outside signed contracts.
The guidance raise was substantial. The revenue range moved to $4.63-$4.73 billion from $4.0-$4.15 billion, adjusted EPS to $21.70-$21.96 from $19.70-$20.30, and adjusted EBITDA to $970-$981 million. The midpoint still implies fourth-quarter revenue of roughly $1.1 billion, a meaningful step down from the third quarter's $1.56 billion that investors will want explained.
The follow-up event on October 29 was a conference fireside chat rather than a full earnings call, so it added no new financial targets. Its tone, however, was markedly more emphatic. CEO Joe Cutillo described the following:
- Projects now spanning 10,000+ acres, with self-powered campuses discussed at 30,000-50,000 acres.
- Four campuses picked up this year that Sterling did not originally start.
- CEC growth of 140%, with the company hiring about 80 electricians a week in Texas.
- A tripled modular facility and an equipment-allocation arrangement with Caterpillar.
- Zero delays, pauses or cancellations despite political noise around data centers.
He framed long-term growth as 20-30% organic plus 20-30% from acquisitions and suggested even that may not meet demand. He also called the shares underpriced. The risks have sharpened, though. The 300-500 basis point CEC margin-expansion target slipped to 18-24 months from 12-18 months. Two loss-making legacy CEC units will weigh on results until an exit by the end of 2027. Constraints on electricians, project managers and equipment are expected to persist into 2027 and beyond.
Investor sentiment deteriorated meaningfully heading into the report, falling from a solidly positive 0.31 after the August release to slightly negative at -0.03. Price action tells the same story. At $388.87, shares were 26.6% below the $530 post-August open and 29.3% beneath the 200-day moving average of $550.32. The Earnings Whispers price and AVWAP trends are both negative. In short, the market has been discounting execution, cash-conversion and AI-capex durability concerns even as the reported numbers kept beating.
The bottom line is that Sterling's fundamentals remain exceptional, with triple-digit earnings growth, a third guidance raise and a demand narrative that management says is still understated. The report also showed a sequential dip in signed backlog, mix-driven margin dilution, a delayed CEC margin timeline and receivables growing faster than cash. A stock trading far below its 200-day average with souring sentiment suggests investors want proof that unsigned awards convert and margins re-expand, not just another beat.
Read our earnings preview for Sterling Infrastructure, Inc.: https://www.earningswhispers.com/article/STRL/20989
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-05 | |
| Sep-04 | |
| Aug-27 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 |
