Claros Mortgage Trust Heads Into Q3 Testing Whether Its $8.58 Book Value Holds
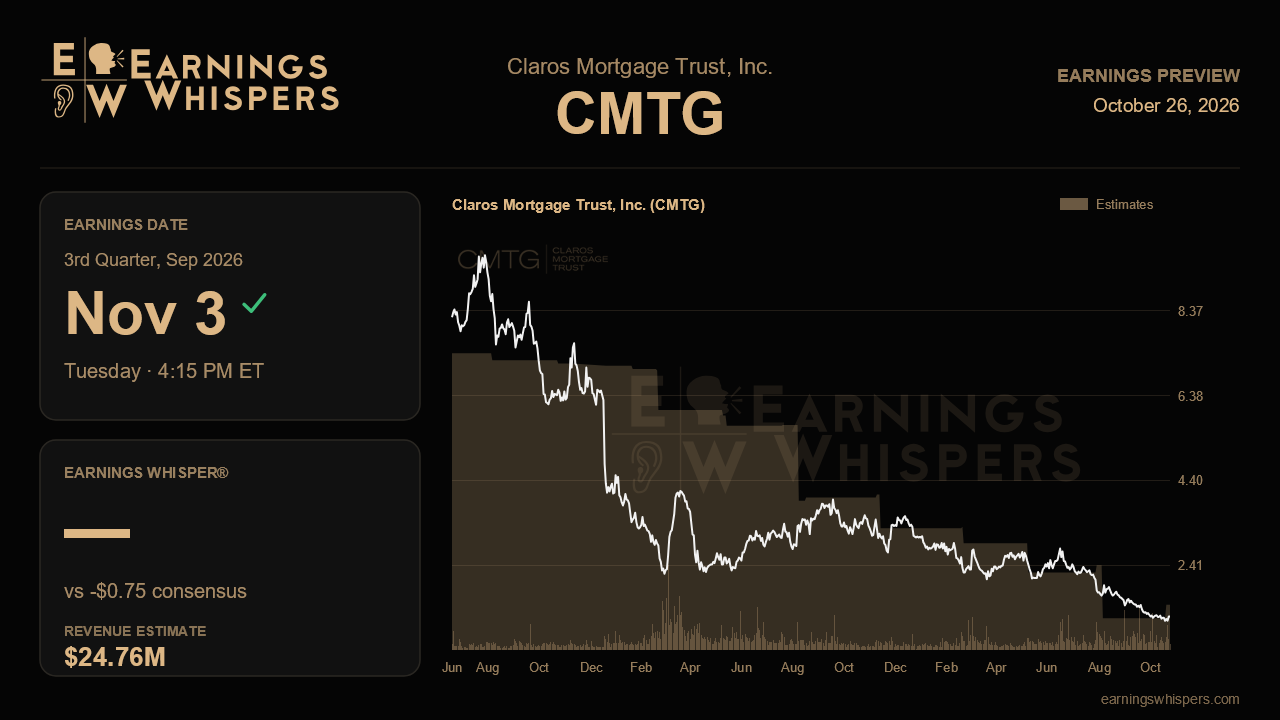
Claros Mortgage Trust enters its third-quarter report with a stock that trades as if its balance sheet were mostly fiction. Shares sit near $1.21, roughly one-seventh of the $8.58 book value management reported after last quarter's write-downs. That gap is the whole story. Last quarter management chose to mark troubled loans down to the prices buyers would actually pay, taking about $1.26 per share of specific loan-loss provisions plus a REO write-down. The question now is whether that reset was enough, or whether the market is right to assume more pain is coming.
The Street expects a loss of $0.75 per share, wider than the $0.64 loss last quarter and far worse than the $0.16 loss a year ago. Revenue is projected at $24.8 million, down from $29.7 million last quarter and 46.3% below the year-ago figure. This contraction is largely by design. Every loan resolved, sold or foreclosed shrinks the interest-earning book, and nonaccrual loans produce little income while they await resolution. Management offered no formal outlook, so the consensus figures stand on their own as the measure.
The prior call showed two trends moving in opposite directions. The cleanup was going well. Resolutions reached roughly $1 billion year to date, watch list loans fell to $1.1 billion from $2.7 billion at the end of 2024, and liquidity rose to $168 million by late July. Pro forma leverage improved to 1.7 times after July repayments. Management also said for the first time that the company was past the corner. It pointed to possible new loans, buybacks and eventually a dividend in late 2026 or early 2027. The cost of that progress was clear, though. Buyers raised their return requirements, and Sunbelt multifamily, once seen as the safe part of the portfolio, came in below expectations. The CFO would not say book value had bottomed.
This report should show which of those two trends is winning. Three things would support the recovery story. Book value should hold near $8.58 without another round of large specific reserves. The $509 million unencumbered pool should be sold for something close to the roughly $140 million of liquidity management expects. And sales should close near their carrying values, including multifamily, rather than below them. The San Francisco office loan sold in July for $70.7 million is an early test of whether the new marks are realistic. Further cuts to multifamily marks would challenge the story. So would new loans moving onto the watch list, or liquidity that fails to build despite the asset sales. Any of these would suggest the second quarter was another step in a longer decline rather than a final reset. The New York hotel REO, which added to distributable earnings last quarter, is a smaller item but would help steady operating results.
The market has already rendered a harsh preliminary verdict. Shares have fallen 36.3% since the last report, about 40 percentage points worse than the S&P 500. Sentiment has flipped from moderately bullish before the prior report to mildly bearish now. The stock trades well below its 200-day moving average of $2.18 and near the bottom of its post-earnings range of $1.09 to $1.99. By comparison, the entire range in the prior quarter sat above $2. Expectations are low, but a low price is not the same as a low bar. Investors seem to doubt the reported book value itself, not just the quarterly loss.
The headline loss number may matter less than what happens to book value. A wider loss caused by a smaller loan book is expected and largely priced in. If book value is stable and liquidity keeps building, the market's discount starts to look excessive, and management's talk of turning toward new lending and buybacks gains credibility. Another meaningful drop in book value would confirm what the share price already implies: the company has not yet found the bottom.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Jul-30 | |
| Jul-29 | |
| Jul-15 | |
| May-06 | |
| Apr-22 | |
| Mar-18 | |
| Feb-19 | |
| Feb-19 | |
| Feb-18 | |
| Feb-10 | |
| Feb-04 | |
| Feb-02 | |
| Nov-06 |
