Claros Mortgage Trust Crushes A Depressed Consensus As Credit Stabilizes, But Book Value And The Earnings Base Keep Shrinking
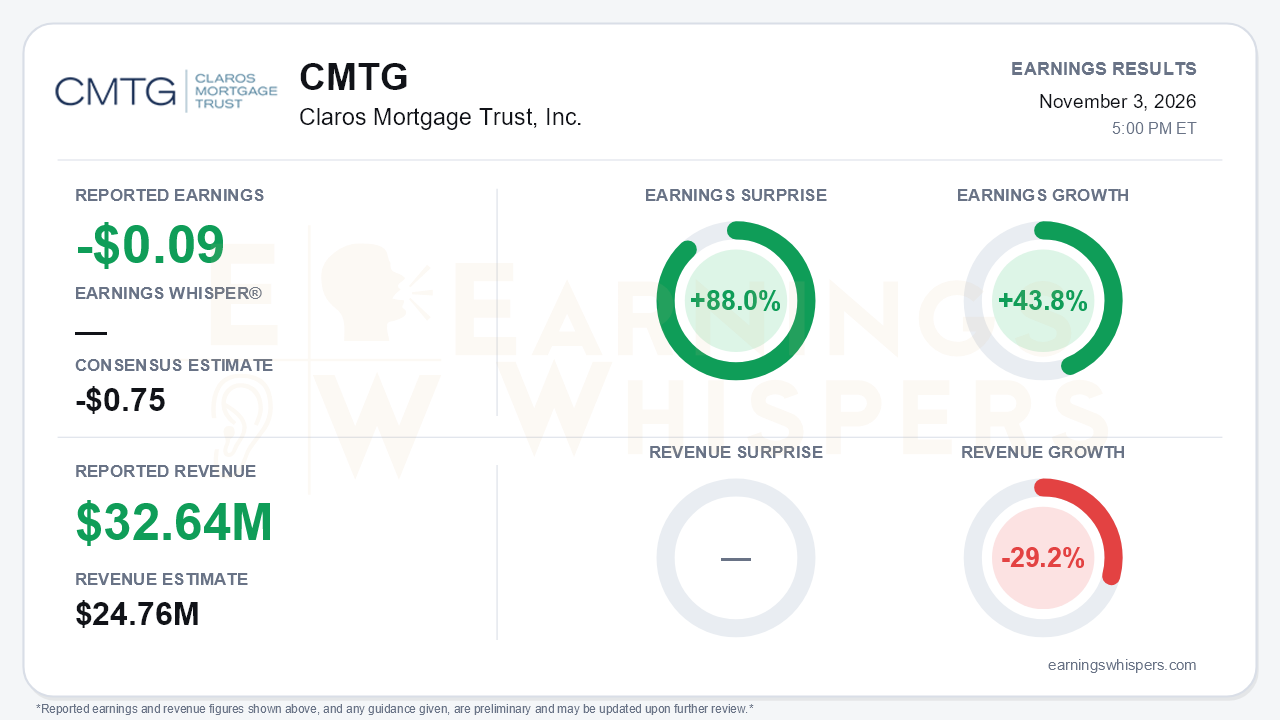
Claros Mortgage Trust (NYSE: CMTG) reported a third-quarter loss of $0.09 per share, far better than the consensus estimate for a $0.75 loss. That is an 88.0% earnings surprise. Revenue of $32.64 million beat the $24.76 million consensus by 31.8%. Earnings improved 43.8% year over year, while revenue fell 29.2%. Those two growth figures frame the quarter. Analysts had braced for another markdown-heavy period like the second quarter. Instead they got a stabilization quarter. Credit migration stopped, resolutions cleared near carrying value, and leverage fell. The revenue decline, however, shows the cost of that progress: the interest-earning base is shrinking as the company liquidates its way to a cleaner balance sheet.
The quality of the beat deserves context. The company's own measures differ slightly from the normalized figure. GAAP net loss was $14.3 million, or $0.10 per share. Distributable loss was $0.08, and distributable loss before realized gains and losses was $0.05. Every one of those measures improved sharply from the second quarter. That period produced a $255.4 million GAAP loss ($1.81 per share), a $208.8 million CECL provision and a $0.63 distributable loss. This quarter's provision was just $0.4 million, and principal charge-offs fell to $4.9 million from $44.0 million. The beat therefore reflects the absence of new damage more than any surge in earning power. The operating loss before realized items, at $0.05, was the same as in the first quarter. That is a meaningful distinction for investors extrapolating the surprise.
The operating story centered on execution. CMTG resolved four loans totaling $409.5 million of UPB, including a sale and a discounted payoff of two watchlist loans. It also sold a multifamily REO asset and cut financings by $330.1 million, compared with roughly $66 million of net paydown in the second quarter. Net debt-to-equity fell to 1.7x from 2.0x, and to 1.5x pro forma for $268.7 million of October repayments. No loans were added to the watchlist, which now stands at $1.1 billion, and none moved to non-accrual. Management's tone firmed noticeably. It argued that binding contracts with nonrefundable deposits validate the second-quarter marks:
- two risk-rated 5 loans selling for about $311 million, roughly 97% of carrying value;
- two New York REO hotels selling at a slight premium to carrying value.
Management also flagged a possible net interest income inflection. It quantified two removable drags: about $0.06 per share per quarter from leverage on non-accrual loans, and about $0.10 per share per quarter from the SOFR+675 term loan.
Bears still have legitimate ammunition:
- **Book value:** it slipped to $8.49 from $8.58, and the pending loan sales are expected to produce roughly $10.4 million (about $0.07 per share) of additional fourth-quarter losses.
- **Reserves:** the general CECL reserve rose to 3.4% of UPB from 2.9% in the second quarter and 2.3% in the first.
- **Liquidity:** it fell to $142.7 million on November 2 from $168 million pro forma in July.
- **Multifamily REO:** NOI weakened amid Sunbelt oversupply and workforce-renter stress.
- **Rates:** the CEO acknowledged that further rate increases could force more markdowns.
- **Outlook:** management again declined to give watchlist or loss guidance, citing choppy waters, and it did not reiterate its earlier goal of restarting originations in late 2026 or early 2027.
The market setup is more complicated than the surprise implies. Shares have fallen 41.6% since opening at $1.90 after the July report and now sit near $1.11. That is about 47.6% below the 200-day moving average of $2.12, and a fraction of the stated $8.49 book value. Investor sentiment swung from a modestly positive 0.287 to -0.125, a substantial deterioration that flipped expectations negative heading into the print. The Earnings Whispers trend signals are mostly negative, with price, momentum and AVWAP all pointing lower and sequential growth only neutral. The stock has been priced for continued erosion rather than stabilization.
That is the central tension. The balance sheet is demonstrably healthier: leverage is lower, credit migration has halted, and contracted sale prices are close to marks. Yet that same liquidation shrinks revenue, chips away at book value and pushes any return to originations further out. Management's disclosure that cash and performing loans account for about $4.97 of the $8.49 book value per share sharpens the debate. Investors must decide how much to trust the remaining $1.99 of REO value and the reserves on the watchlist.
The bottom line is that CMTG delivered the quiet quarter turnaround skeptics were not positioned for. It beat a deeply negative consensus by avoiding new losses, not by growing earnings. The next proof points are closing the contracted sales at their stated prices, retiring the costly term loan, and showing that net interest income can turn positive as the portfolio shrinks. Until then, falling book value, thinning liquidity and rate sensitivity will keep the stock's discount contested.
Read our earnings preview for Claros Mortgage Trust, Inc.: https://www.earningswhispers.com/article/CMTG/21557
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Jul-30 | |
| Jul-29 | |
| Jul-15 | |
| May-06 | |
| Apr-22 | |
| Mar-18 | |
| Feb-19 | |
| Feb-19 | |
| Feb-18 | |
| Feb-10 | |
| Feb-04 |
