Crexendo Needs Organic Growth Proof As ESI Boost Fades From The Spotlight
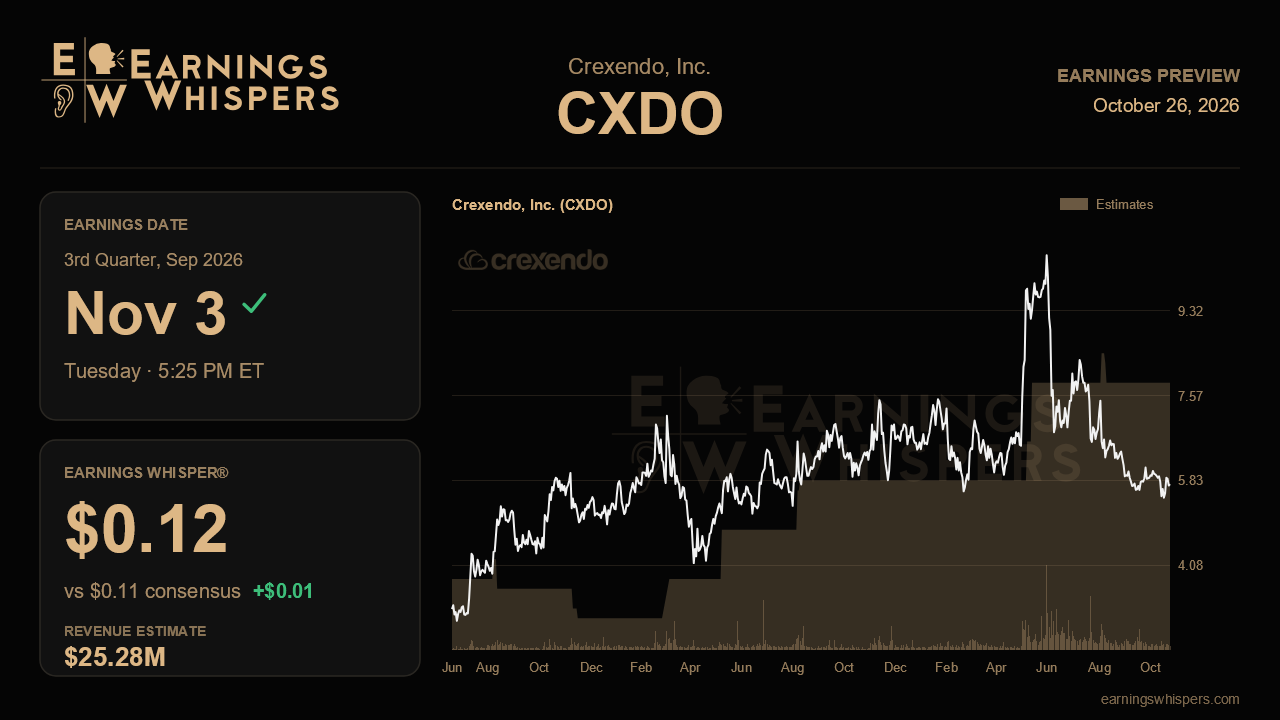
Crexendo heads into its third-quarter report with a split personality. On paper, the business has never looked bigger or more profitable. Revenue has climbed for four straight quarters, margins snapped back, and the ESI acquisition is outperforming. The stock, however, has fallen about 22% since the last report while the S&P 500 barely moved. That gap suggests the market has fixated on the one number management could not fully dress up last quarter: organic growth slipped to 7% from 16% in the first quarter.
Wall Street expects earnings of $0.11 per share on revenue of $25.3 million, a 44.5% jump from the $17.5 million reported a year ago. That headline growth rate is flattering, though, because ESI is still inorganic. Compared with the $24.6 million posted last quarter, the consensus calls for only about 3% sequential growth. If ESI holds its recent pace of roughly $2.3 million a month, the forecast implies the legacy business grows somewhere in the mid-single digits year over year, a touch below the second quarter's already softer rate. The Earnings Whisper of $0.12 sits a penny above consensus. That is a modest gap, but it hints that some investors expect last quarter's margin recovery to carry through to the bottom line. Crexendo does not provide formal guidance, so the closest thing to a target is its goal of reaching a $100 million annual revenue run rate by the end of 2026. Notably, the $25.3 million consensus already annualizes to roughly that level, which makes the goal less of a stretch and more of a floor.
The central question is whether management's explanation for slower organic growth holds up. Executives argued that new platform customers are signing smaller initial deals, averaging around $250,000, as they hedge against economic uncertainty, with the intent to expand later. They also pointed to a tough comparison against a record perpetual-license quarter. The land-and-expand story is plausible, especially with 11 new platform logos in the first half versus just two a year earlier. But it needs evidence. A steady flow of new logos, any sign that earlier wins are expanding, and remaining performance obligations holding at or above $139 million would support the thesis. A further slide in organic growth, particularly without a perpetual-license excuse, would make the reframing look more like a rationalization.
Margins are the second test. Consolidated gross margin rose 500 basis points to 66% last quarter, helped by retiring legacy data centers and a sharp recovery in product margins to 44% from 31%. Adjusted EBITDA margin returned to 17%. Product margins in particular can swing, so sustaining something close to those levels would show that the improvement was structural rather than a one-quarter bounce. Investors will also want an update on the balance sheet, where cash fell to $18.3 million after the ESI purchase, and on early AI efforts. The Cairo AI receptionist reportedly lifts average revenue per account by about 35%, but management itself said meaningful AI revenue is a 2027 story, so commentary from the October user group meeting may matter more than the dollars.
Sentiment has soured noticeably, with bearish readings rising to nearly 58% from about 39% ahead of the prior report. The stock trades at $5.75, well below its 200-day moving average of $6.91 and not far above its post-earnings low of $5.35, after a previous quarter that saw shares trade as high as $11.23. That pessimism lowers the bar somewhat, though it does not guarantee a favorable reaction.
Ultimately, this report comes down to whether the core business can stabilize its organic growth rate while ESI keeps delivering. Solid margins and the $100 million run rate are largely expected. A clear sign that smaller initial deals are starting to grow into larger relationships would restore credibility to the improving narrative, while another step down in organic growth would likely keep the stock's skeptics in charge.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-20 | |
| Oct-14 | |
| Oct-12 | |
| Oct-09 | |
| Sep-21 | |
| Sep-02 | |
| Aug-25 | |
| Aug-18 | |
| Aug-17 | |
| Aug-11 | |
| Aug-11 | |
| Aug-04 |
