Crexendo Matches The Whisper As ESI Drives 44% Growth, But Organic Growth Slows To 5% And Management Declines To Frame 2027
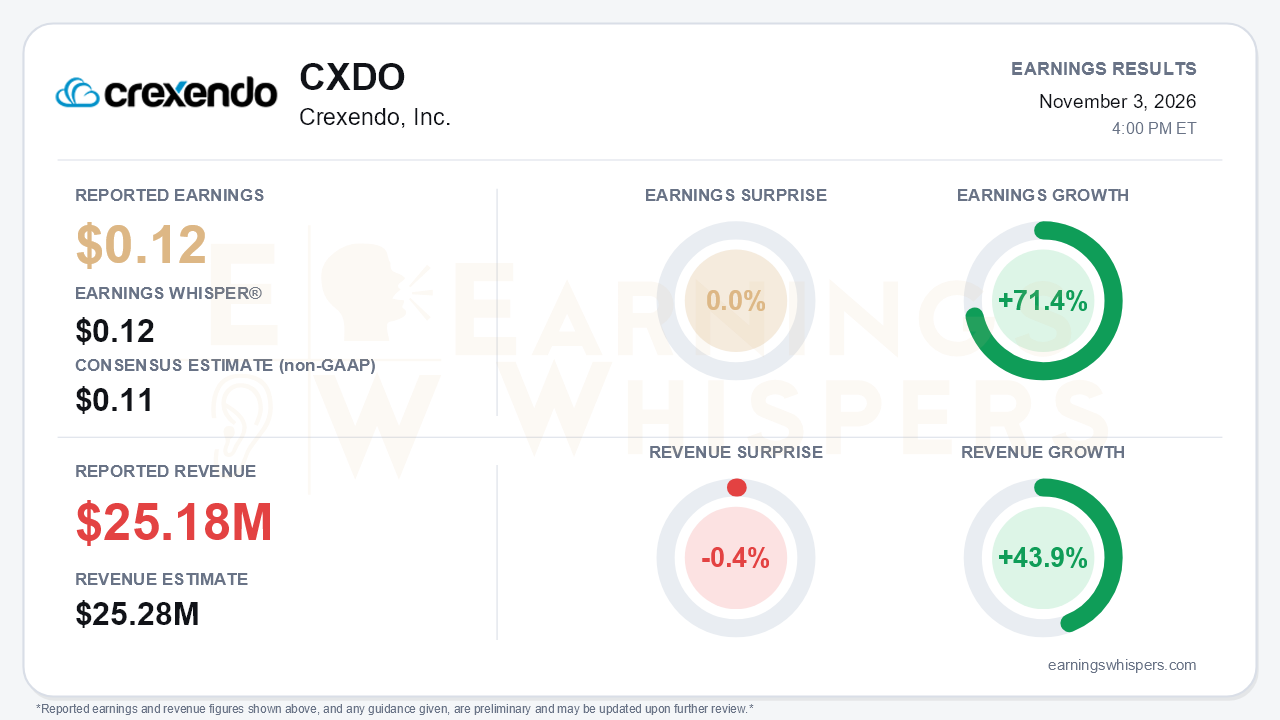
Crexendo (NASDAQ: CXDO) delivered a quarter that looks stronger at the headline than underneath. Non-GAAP earnings of $0.12 per share matched the Earnings Whisper number and topped the $0.11 consensus, for a 0.0% surprise against the Whisper. EPS grew 71.4% year over year. Revenue rose 43.9% to $25.18 million but missed the $25.28 million consensus by 0.4%. Management also said the company had reached its $100 million annualized revenue run-rate goal before year-end. The central tension is that the ESI acquisition is carrying the reported growth while the organic business is slowing. Organic growth fell to 5% in the third quarter, down from 7% in the second quarter and 15.9% in the first.
The quality of the beat deserves scrutiny. On a GAAP basis, net income fell to $1.1 million, or $0.03 per share, from $1.5 million, or $0.05, a year earlier. Operating income also declined, to $1.08 million from $1.31 million, even though revenue grew by $7.7 million. Operating expenses rose 49%, faster than revenue. Selling and marketing spending nearly doubled to $8.4 million. Amortization of intangible assets more than doubled to $1.8 million, which explains much of the gap between GAAP and non-GAAP results. Service revenue jumped 75% to $15.1 million, but that gain is largely acquired. Software solutions revenue, the core NetSapiens licensing business, grew just 2% to $7.7 million. That growth rate has slowed for several quarters, from 18% in the fourth quarter of 2025 to 12%, then 5%, and now 2%. Sequential profitability also slipped:
- Adjusted EBITDA was $4.0 million, a 16% margin, versus a 17% margin in the second quarter. Management had previously described the 17% level as maintainable.
- Product gross margin fell to 41% from 44%.
The call shifted the story more than the release did. Year-to-date organic growth of 9.1% now sits below the double-digit goal that management reaffirmed on each of the prior three calls. Leading indicators for the installed base also softened:
- Upgrade and add-on orders fell to 6, from 7, 9 and 14 over the prior three quarters, and the orders were smaller. Management blamed higher interest rates, since licensees finance their upgrades. In the second quarter, management had said upgrade order value was increasing.
- Remaining performance obligations were essentially flat at $139.6 million.
- ESI revenue edged down to $6.8 million from $6.9 million.
The tone turned more defensive. The CEO declined to offer a 2027 organic growth outlook, citing the economy, and said the company is limiting or deferring certain expenses and hires.
The call did preserve a credible long-term growth story. Crexendo has won 16 new NetSapiens platform logos year to date, already more than the 14 it signed in all of 2025. Average initial license contract value rebounded to more than $400,000, versus roughly $175,000 to $230,000 in the first half. That eases the deal-size concern raised on the second-quarter call. Other operating metrics improved:
- Software solutions gross margin rose to 71%, from 70% in the second quarter and 68% in the first.
- The partner ecosystem grew to 66 vendors, 22 of them AI-focused, from 57 last quarter.
- Revenue from the CAIRO product rose 20% sequentially.
- The company launched a conversational intelligence AI product with usage-based pricing.
The catch is timing. General availability of NetSapiens Flow is now targeted for mid-2027, and management framed meaningful CAIRO revenue for mid-to-late 2027. The new logos should feed future organic growth as providers migrate subscribers, but that conversion will take time.
The balance sheet gives management room to wait. Cash rose to $22.8 million from $18.3 million at the end of the second quarter. Operating cash flow was $4.9 million in the third quarter and $9.7 million over nine months. Cash remains below the $31.4 million at year-end 2025, after $26.2 million was spent on ESI, and the company now carries about $4.7 million in notes payable. Management said it is actively evaluating further acquisitions. That suggests acquired growth may keep doing the heavy lifting while the organic business works through a softer upgrade cycle.
The market had already turned skeptical before the report. Shares fell 22.6% from the $7.33 opening price after the August report to $5.67. They trade 17.6% below the 200-day moving average and only 6% above the 52-week low of $5.35 set on October 15. Earnings Whispers investor sentiment remained negative and weakened further, moving from -0.39 to -0.50. The trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP are negative. Bears have legitimate ammunition in the organic slowdown and the missed target. Still, a stock trading near its lows already prices in a good deal of that disappointment.
The bottom line is that Crexendo matched expectations on non-GAAP earnings but revealed a weaker organic engine. Organic growth slowed to 5%, software licensing barely grew, upgrade activity faded and management declined to frame 2027. Record logo wins, larger initial deals and an expanding AI roadmap support the long-term case, but their payoff appears to sit in the second half of 2027. Until organic growth re-accelerates, the acquisition-driven headline numbers are unlikely to resolve the skepticism already reflected in the stock.
Read our earnings preview for Crexendo, Inc.: https://www.earningswhispers.com/article/CXDO/21561
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-20 | |
| Oct-14 | |
| Oct-12 | |
| Oct-09 | |
| Sep-21 | |
| Sep-02 | |
| Aug-25 | |
| Aug-18 |
