Flotek Faces Proof Test As Raised Outlook Clashes With A 29% Stock Slide
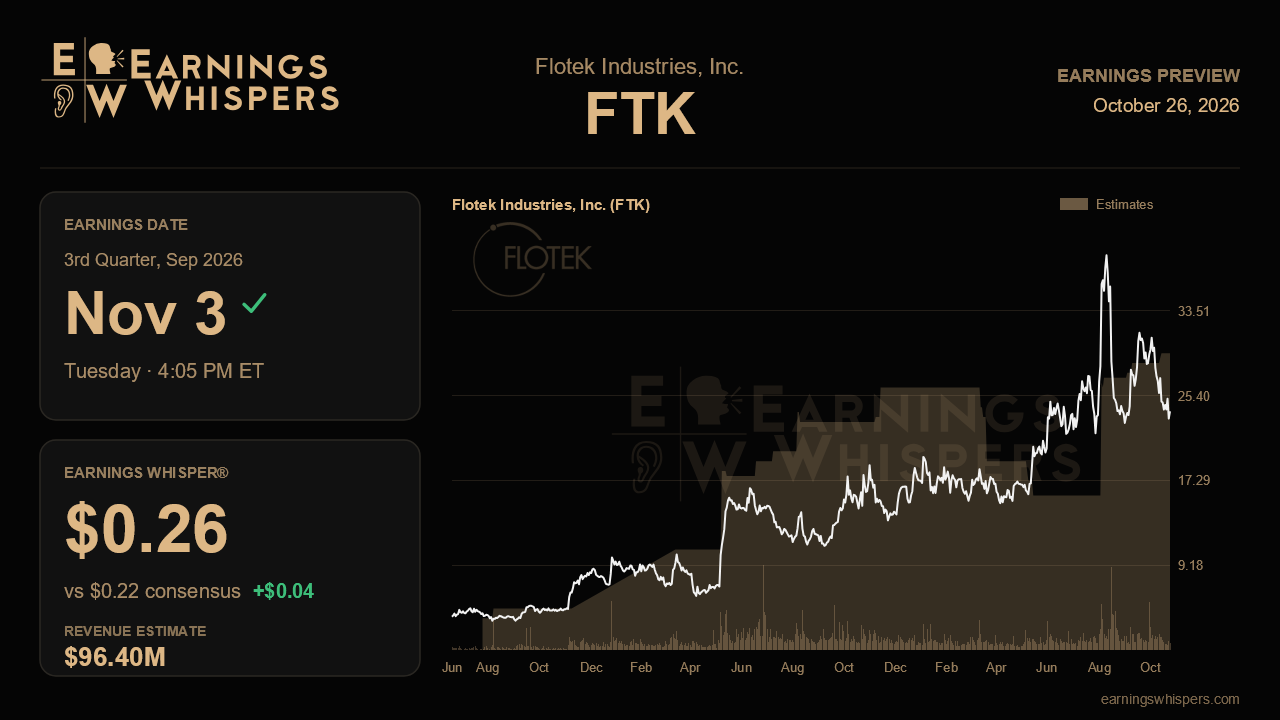
Flotek Industries heads into its third-quarter report with an unusual disconnect. Management has now raised its full-year revenue outlook twice in quick succession, booked a decade-defining power contract in Puerto Rico, and watched its data analytics business become the largest source of gross profit. Yet the shares have fallen nearly 29% since the last report, trailing the S&P 500 by more than 26 percentage points. The November 3 release, due after the close, is the first real chance to show whether that operating momentum is durable or whether the market was right to treat the second quarter as a high-water mark.
The Street is looking for earnings of $0.22 a share on revenue of about $96.4 million. That revenue figure would represent growth of roughly 72% from the $56.0 million reported a year ago, but it would also be a modest step down from the record $99.4 million posted last quarter. Earnings are expected to rise only about 10% from the year-ago $0.20, and to fall from last quarter's $0.26. The whisper number sits at $0.26, above consensus, suggesting that the more engaged crowd expects Flotek to roughly match its second-quarter profitability rather than slip back. That raises the effective bar.
Guidance makes the setup more interesting. After lifting its 2026 revenue outlook to $340 million to $350 million from $270 million to $290 million on the last call, Flotek raised it again to $360 million to $370 million. The full-year consensus of $345.4 million sits below even the low end of that new range, which implies analyst models have not fully caught up. If management reaffirms or nudges the range higher, estimates for the fourth quarter likely need to move up. Notably, the prior outlook excluded any contribution from the Puerto Rico power deal and assumed the Montana Power Services contract, worth about $6 million a quarter, would drop out in the fourth quarter absent a Phase II extension.
The operational questions follow directly from last quarter's narrative. Management expected second-half chemistry revenue to cool after a June surge that was partly pulled forward, so a sequential dip in domestic external chemistry would be consistent with the plan rather than a warning sign. What would challenge the story is weakness in the higher-margin data analytics segment, which grew 223% year over year last quarter. Investors should look for continued growth in digital valuation units beyond the 89 deployed or contracted, evidence that the contracted backlog above $500 million is converting into revenue, and progress toward the stated goal of supporting more than 5 gigawatts of power measurement and control by early 2027. Internationally, the Middle East business was running on four frac fleets with a path to six by year-end; confirmation of that expansion would support the case that the $10.6 million international quarter was not a one-off. Clarity on the margin profile and deployment timing of the Puerto Rico contract, any word on the Montana extension, and an update on the power pipeline management sized at more than $1 billion would all add substance. Working capital also matters after a roughly $36 million draw in the first half.
Sentiment has improved, moving to a mildly bearish 5.0% reading from 12.6% bearish ahead of the prior report, even as the stock retreated. Shares at $23.90 sit near the bottom of the post-earnings range between $22.15 and $39.67, though still above the 200-day moving average of $21.82. That positioning means the market is no longer pricing in perfection.
The central issue is whether Flotek can show that its data analytics and power services franchise is compounding on its own, independent of lumpy chemistry orders. If analytics growth and margins hold while guidance stays at or above $360 million, the recent selloff looks like a mispricing of a structurally changed business. If analytics stalls, the second quarter may come to look like a peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 7 hours | |
| 12 hours | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Sep-30 | |
| Sep-23 | |
| Sep-21 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 |
