Flotek Beats And Raises Again On A Saudi Chemistry Surge, But The Data Analytics Growth Story Lost Some Shine
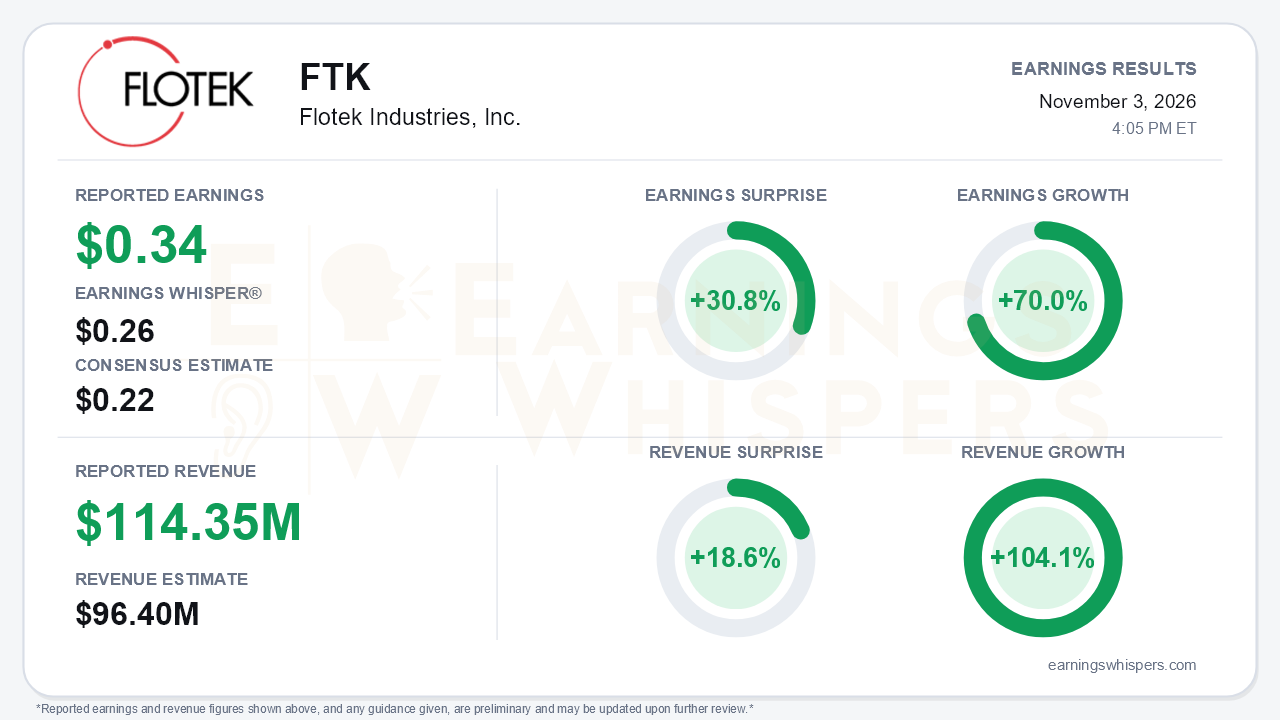
Flotek Industries delivered another clean beat. Third-quarter EPS was $0.34, against a $0.22 consensus and a $0.26 Earnings Whisper number, a 30.8% surprise. Revenue of $114.35 million topped the $96.4 million consensus by 18.6% and grew 104.1% year over year, the company's highest quarterly revenue since 2014. Management raised full-year guidance again, to revenue of $382-$390 million and adjusted EBITDA of $59-$62 million. The central tension is the source of the upside. It came mostly from lower-margin chemistry, especially in Saudi Arabia, while the higher-margin Data Analytics business that underpins Flotek's technology narrative slowed and lost a marquee contract.
The earnings headline needs context. Earnings Whispers shows 70.0% year-over-year earnings growth. GAAP diluted EPS, however, fell from $0.53 because the year-ago quarter included a $12.6 million non-cash tax benefit from a valuation-allowance release. Pre-tax income more than doubled to $16.4 million, and adjusted EBITDA rose 87% to $19.5 million from $16.8 million in Q2. Revenue, net income and adjusted EBITDA have now grown in every quarter of 2026.
Consolidated gross margin fell to 24% from 32%. Most of that drop came from a $7.8 million decline in no-cost minimum-purchase shortfall revenue from ProFrac, whose related-party chemistry purchases topped $50 million for the first time. Excluding that shortfall payment, management said gross margin improved about 400 basis points year over year. G&A also fell to 7% of revenue.
Cash flow is less flattering. Operating cash flow was negative $16.8 million year to date as receivables and inventory ballooned. External receivables jumped to $66 million from $19 million at year-end.
The call explained what changed under the surface. International chemistry reached $28.4 million, up from $10.6 million in Q2 and $1.9 million in Q1. It is concentrated in Saudi Arabia's Jafurah field and guided flat for Q4. Data Analytics revenue doubled, but that growth rate has decelerated sharply, from 295% in Q1 to 223% in Q2 to 104% now. The segment's gross margin slipped to 68% from 75% in Q1, and its share of company gross profit fell to 45% from 51%.
The bigger blow was to backlog. The 10-year, $400 million Puerto Rico PREPA contract touted on the Q2 call unwound after the consortium failed to post a performance bond, erasing most of the more than $500 million backlog management cited last quarter. Separately, the Montana power services contract, worth roughly $6 million a quarter, expired in September without renewal.
The guidance math also deserves attention. Subtracting year-to-date results from the new full-year range implies Q4 revenue of roughly $98-$106 million and adjusted EBITDA of about $14-$17 million, both below Q3. There is also a discrepancy on the prior range. The release lists it as $360-$370 million, while the call analysis references $340-$350 million from the Q2 call, which suggests an interim update between reports.
Management did offer credible forward catalysts. A $120 million term loan, with $75 million funded initially, backs a 2027 capex plan of $15-$20 million aimed at next-generation measurement and conditioning skids. Four skids are due by year-end, and three are already contracted. Other developments:
- **Power support:** Powertech is heading toward about 6 GW under measurement or control by Q1 2027, with 13-15 of its 41 skids deployed outside ProFrac, including early data center work.
- **Digital valuation:** units passed 135, up from 89 in Q2, and now account for 9% of Data Analytics revenue.
- **VeriCal:** a second EPA approval opens a refinery flare market management sizes at more than $40 million.
- **OEM engine program:** three more OEM prospects are evaluating the technology.
The risks are concrete. Management expects North American land activity to be flat to down in 2027. Customer concentration remains high, with heavy reliance on ProFrac and Saudi Arabia. Leverage is higher, though still under 1x.
The market had already priced in plenty of skepticism. Shares are at $24.84, down 25.8% from the $33.47 open after the August report, a slide that coincided with a period in which the Puerto Rico backlog story unraveled. The stock still sits 12.5% above its $22.09 200-day moving average, so the longer-term uptrend has not broken. Investor sentiment moved from mildly negative (-0.13) to mildly positive (+0.10), a meaningful improvement but hardly euphoric. Earnings Whispers trend readings lean positive on sequential growth and momentum, while AVWAP remains negative, consistent with buyers who entered after the last report still sitting on losses.
The bottom line is that Flotek's numbers keep outrunning expectations, with a third guidance raise and a 30.8% beat. The quality of that growth has shifted toward Saudi chemistry and ProFrac volume rather than the high-margin, diversified Data Analytics franchise that justifies a technology multiple. The lost Puerto Rico and Montana contracts, decelerating Data Analytics growth, an implied Q4 step-down and negative operating cash flow give bears legitimate ammunition. The newly funded skid build-out and power-market traction keep the growth story credible. Investors now need evidence that 2027 capex converts into contracted, high-margin Data Analytics revenue.
Read our earnings preview for Flotek Industries, Inc.: https://www.earningswhispers.com/article/FTK/21576
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Sep-30 | |
| Sep-23 | |
| Sep-21 |
