Fuel Tech's Record Backlog Faces A Margin And Data Center Test In First Report Under New CEO
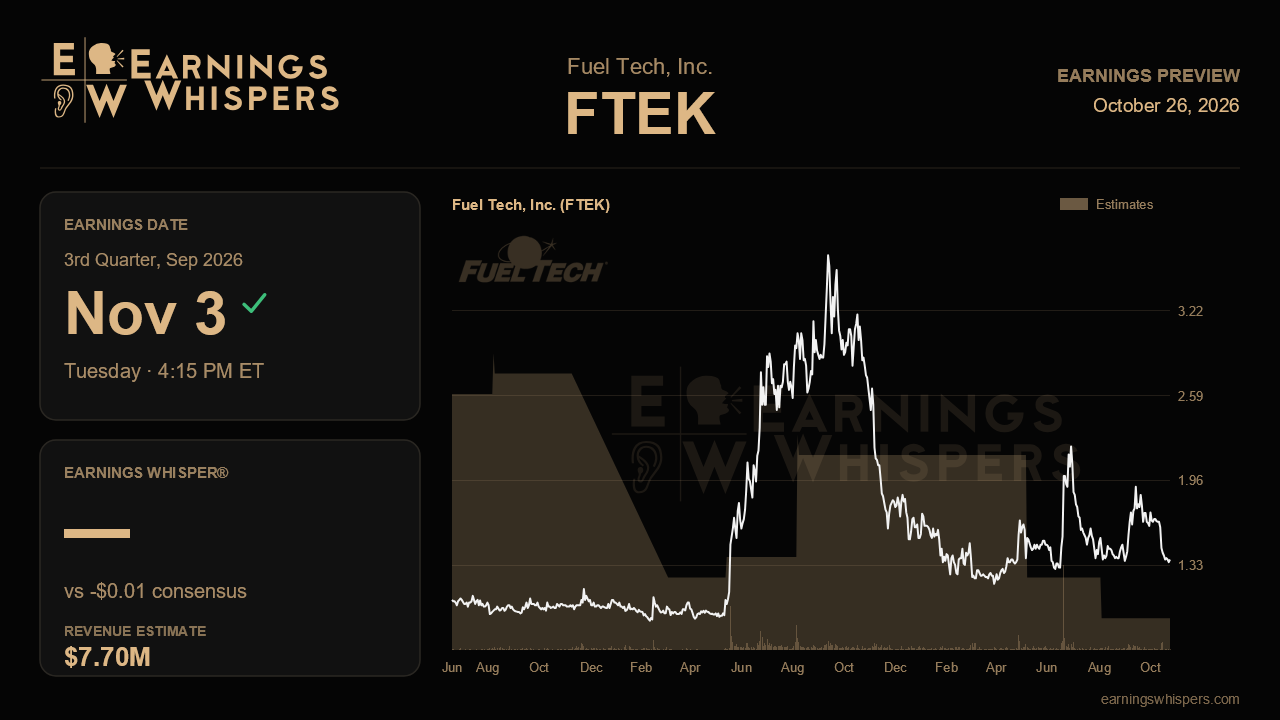
Fuel Tech heads into its third-quarter report with the healthiest order book it has carried since 2018, but it also faces an awkward question about what that book is worth. Backlog in air pollution control more than doubled last quarter to $14.3 million and stood near $17 million after fresh awards. Over the same stretch, gross margins slid for a fourth straight quarter and cash kept drifting lower. This report, the first under new chief executive Ramesh Nagahalli, should show whether the revenue revival can start carrying profits with it.
The Street expects a loss of about a penny a share on revenue of roughly $7.7 million. The year-over-year comparison looks unremarkable: sales up less than 3% and earnings swinging from a one-cent profit to a small loss. The sequential picture is more demanding. Revenue would need to climb about 18% from the $6.5 million booked last quarter, and the per-share loss would need to shrink from four cents to one. Management did not raise its outlook last time. It reaffirmed that FuelChem should land roughly in line with 2025, near $18 million, and that air pollution control should top last year. The consensus fits that framework, but only if backlog starts turning into recognized revenue at a faster pace.
Margins are the swing factor. Consolidated gross margin fell from 49% a year ago to 41% last quarter, and the pollution control segment dropped to 36% because of project mix and execution costs. Large engineered projects often carry thinner margins in their early stages. The roughly $10 million Midwest municipal utility award, now in engineering, will not deliver equipment until late 2027. A rising share of lower-margin project work could therefore lift revenue without lifting earnings. If segment margins steady in the high 30s and FuelChem holds near the mid 40s, the shrinking-loss story holds up. Another leg down would suggest the record backlog is buying volume at the expense of profitability.
FuelChem matters too. Strong summer dispatch at older plants drove 21% growth last quarter, and the third quarter usually captures the rest of that seasonal demand. The demonstration account that was halted is not expected back until the middle of the fourth quarter. Any upside in this segment will have to come from the existing customer base.
The data center pipeline remains the credibility problem. Management has put it at $75 million to $100 million for several quarters, yet nothing has converted, and last quarter one opportunity fell through while another slipped. Management also raised the possibility of a capacity reservation or long-lead procurement agreement closing before the end of the third quarter. A signed deal would give the pipeline its first real proof of value. Another delay would deepen the suspicion that it is more aspiration than backlog. Beyond that, investors will want to hear early thinking from Nagahalli, especially on acquisitions given the roughly $29.6 million in cash and investments, along with any progress on the fish hatchery proposal and the revived Mexico talks.
Expectations are modest. Sentiment has firmed slightly, from about 10% bullish to 14%. The stock has slipped less than 1% since the last report, a bit better than the broader market. At $1.37, though, it sits below its 200-day moving average of $1.48 and near the bottom of its post-earnings range of $1.30 to $1.96, well off the $2.35 peak of the prior quarter. The market has acknowledged the backlog without paying for it. What decides whether the recovery narrative survives is simple: Fuel Tech needs to show that higher revenue can arrive alongside stable margins and a slower cash drain, ideally with a first data center commitment on top.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Sep-11 | |
| Sep-09 | |
| Sep-08 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-29 | |
| Jul-21 | |
| Jun-24 | |
| May-05 | |
| Apr-28 | |
| Apr-23 |
