Fuel Tech Beats On Revenue And Builds Backlog, But New CEO's Strategy Reset Leaves Promised Catalysts Unaddressed
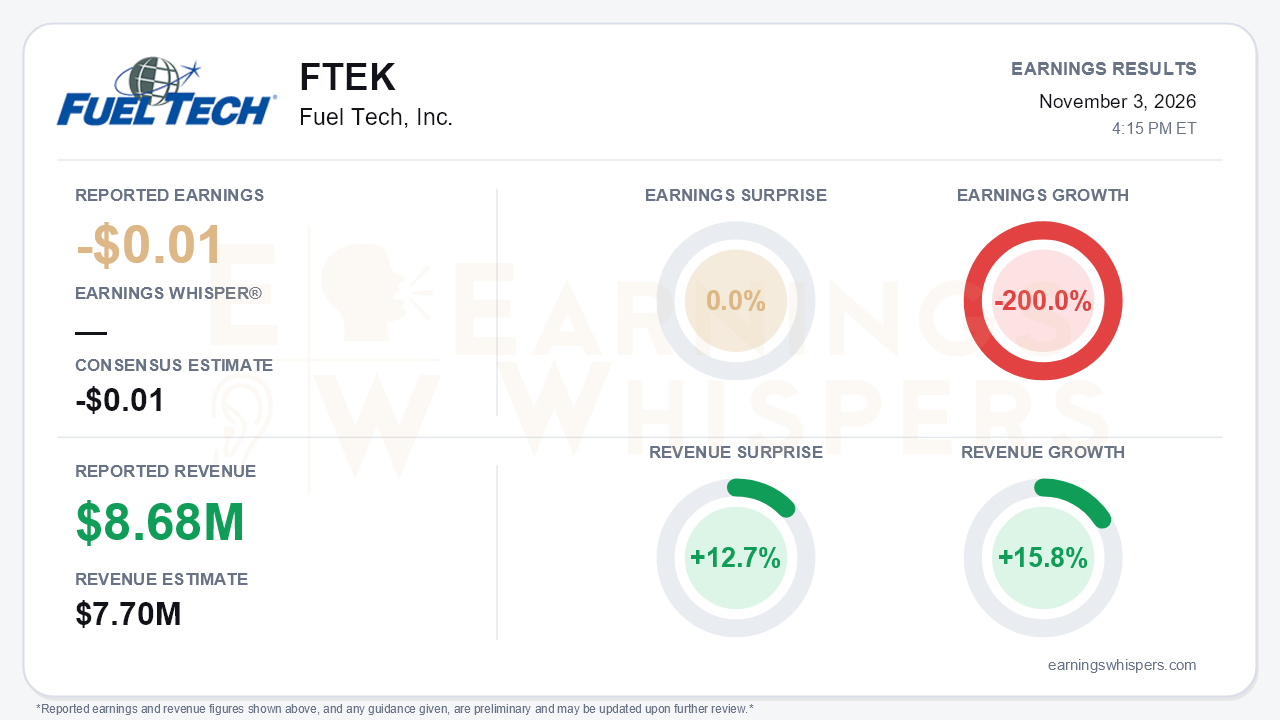
Fuel Tech (NASDAQ: FTEK) delivered its strongest top line of the year in the third quarter, but the more important development was a change in narrative. The company lost $0.01 per share, in line with the consensus estimate. That was a swing from a $0.01 profit a year ago, which Earnings Whispers records as a 200.0% year-over-year earnings decline. Revenue of $8.68 million beat the $7.7 million consensus by 12.7% and grew 15.8% from a year earlier. On the surface, Fuel Tech is gaining momentum. Beneath the surface, new CEO Ramesh Nuggihalli used his first call to pivot toward a strategy review and an M&A playbook. Several specific near-term catalysts that investors had been told to watch for went unmentioned. That is the central tension.
The quarter's quality is mixed but better than the year-over-year comparison suggests. Sequentially, revenue climbed from $6.1 million in Q1 and $6.5 million in Q2 to $8.7 million. The adjusted EBITDA loss narrowed to $249,000 from roughly $1.2 million in Q2 and $1.3 million in Q1, and the net loss shrank to $267,000 from about $1.2 million in Q2. Gross margin tells a two-sided story. At 45%, it was down from 49% a year ago, as APC margin compressed to 40% from 47% on project and product mix. However, it improved from 41% in Q2 and 43% in Q1. Costs also rose:
- SG&A increased $450,000, including roughly $175,000 of non-recurring CEO transition costs, which accounted for a large share of the quarter's net loss.
- R&D climbed to $771,000 from $450,000.
Underlying profitability is close to breakeven, but it is not there yet.
The operating engine is Air Pollution Control. APC revenue rose 38%, and backlog reached $16.6 million at September 30, up from $14.3 million at June 30 and $7.0 million at year-end 2025. A $3.3 million award after the quarter lifts pro forma backlog to roughly $20 million, compared with about $17 million cited on the Q2 call. Management described power demand as a durable tailwind, pointed to premium pricing on re-bid APC wins, and said margins should be stable or growing. FUEL CHEM was the weak spot. Growth slowed to 3% from 21% in Q2, and the geographic mix shifted heavily toward the U.S. as foreign revenue fell to $1.2 million from $1.9 million.
The forward-looking picture is where bears have legitimate ammunition. Prior calls had built anticipation around three items, and none received an update:
- a $75-100 million data center pipeline, including a capacity reservation award flagged for the third quarter;
- a FUEL CHEM demo restart worth an estimated $2.5-3 million annualized;
- a second coal-unit demonstration.
The DGI water business also retreated. Aquaculture adoption is now described as "slower than anticipated," and water R&D is under review, after earlier calls targeted a first commercial DGI sale in 2026. Management also did not explicitly reiterate full-year revenue expectations. In place of those items, investors received a formal strategy review with external advisors, due to the board in early 2027. They also got an M&A framework targeting product, market and business-model gaps, including a possible standalone service business. Both would be funded by $27.8 million of cash and investments with no debt. That balance sheet is real optionality, but it is also eroding. The total is down from $31.9 million at year-end, with $3.4 million of operating cash burned over nine months.
Investors appear to have priced in limited enthusiasm. Earnings Whispers sentiment remained slightly positive but weakened modestly, slipping from 0.098 to 0.064. Shares at $1.42 are up just 2.9% from the $1.38 open after the August report and sit about 4% below the 200-day moving average of $1.48. The Earnings Whispers price and AVWAP trend readings remain negative, while sequential growth and momentum are neutral. That pattern fits a stock that has gone essentially nowhere despite backlog expansion.
The setup has therefore shifted from "wait for the data center award" to "trust the new CEO's process." That requires more patience, and it removes near-term milestones investors could measure. A strategy reset can be healthy. Fuel Tech has struggled for years to translate technology breadth into consistent profits, and a disciplined acquisition plan could address its scale problem. But the timing is notable: the reset arrives just as previously promised catalysts went quiet.
The bottom line is that Fuel Tech's quarter improved on the metrics that are easiest to verify: revenue, backlog and a sharply narrower sequential loss. Meanwhile, it went silent on the catalysts that were supposed to transform the story. The APC backlog provides credible near-term revenue visibility. Still, the data center opportunity, FUEL CHEM conversions and DGI commercialization now sit behind a strategy review that will not be presented until early 2027. Until management reconnects that strategy with tangible awards, the stock's muted reaction and soft sentiment look like a reasonable reflection of the evidence.
Read our earnings preview for Fuel Tech, Inc.: https://www.earningswhispers.com/article/FTEK/21575
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Sep-11 | |
| Sep-09 | |
| Sep-08 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-29 | |
| Jul-21 | |
| Jun-24 | |
| May-05 |
